Home Inventory Checklist for Insurance Claims
By Josh Miner, licensed agent and owner of Miner Family Insurance in Edmond, OK. Updated October 2026.
A home inventory is a detailed list of your belongings, with photos or video, descriptions, approximate values and receipts where you have them. To make one, walk through your home room by room, record a video of every space, open closets and drawers, photograph serial numbers and high-value items, and store everything in the cloud. A good inventory speeds up claims and helps you choose the right personal property coverage.
Key takeaways
- Video every room, including closets, drawers, the garage, attic and shop.
- Photograph serial numbers, model numbers and receipts for expensive items.
- Store your inventory in the cloud or off-site, not only on a device at home.
- Update it once a year and after major purchases.
- Jewelry, firearms, art and collectibles may need to be scheduled separately.
Why do you need a home inventory for insurance?
- Faster claims: After a fire, tornado or burglary, it is hard to remember everything you owned. An inventory gives your adjuster proof.
- Bigger settlements: Items you forget to list do not get paid.
- Right coverage limits: Adding up your belongings shows whether your personal property limit is high enough.
- Easier taxes: Documentation can help if you claim a casualty loss.
How to make a home inventory, step by step
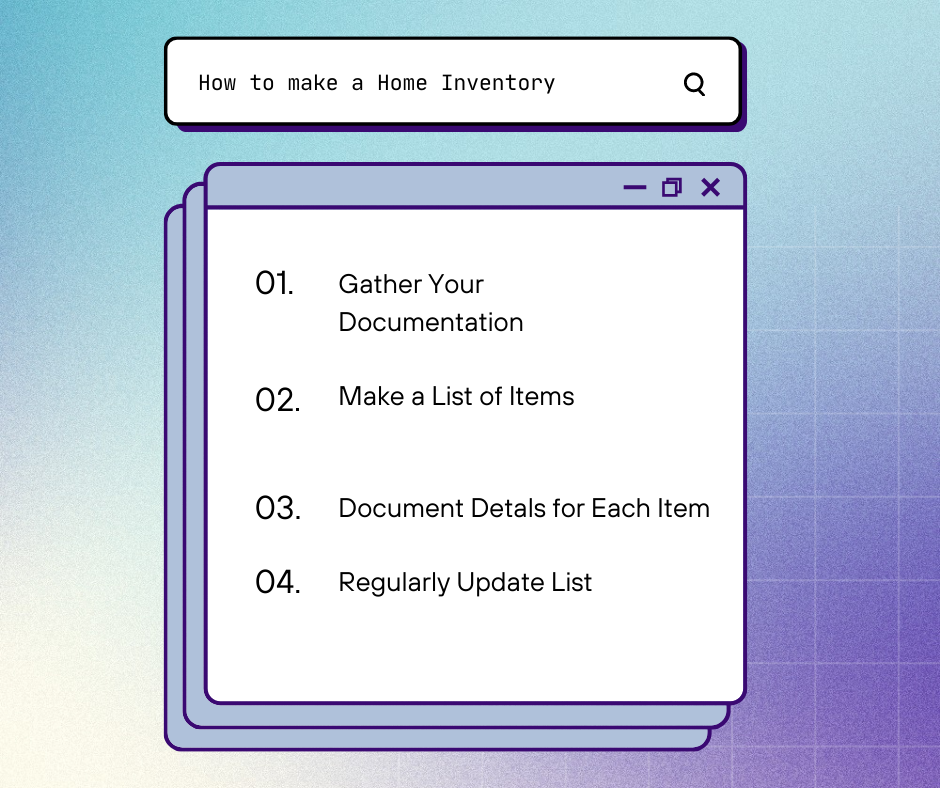
- Pick a tool. A phone video, a spreadsheet or a free home inventory app all work.
- Go room by room. Start at one corner and move clockwise. Narrate what you are filming, including brand names and approximate age.
- Open everything. Film inside closets, cabinets, drawers and storage bins.
- Capture details on valuables. Photograph serial numbers, model numbers and receipts for electronics, appliances, tools, jewelry and firearms.
- Do not skip the extras. Garage, attic, basement, storm shelter, shop, sheds and outdoor furniture.
- Estimate values. Note what you paid and when, or what it would cost to replace today.
- Back it up. Save to cloud storage or email it to yourself so it survives if your home does not.
- Update it. Review once a year and after big purchases, gifts or holidays.
Home inventory checklist by room
- Living room: TVs, sound systems, furniture, rugs, lamps, decor, game consoles.
- Kitchen: Appliances, cookware, small electrics, dishes, glassware.
- Bedrooms: Furniture, mattresses, clothing, shoes, handbags, jewelry, electronics.
- Office: Computers, monitors, printers, furniture, important documents.
- Garage and shop: Tools, lawn equipment, bikes, sporting goods, freezers.
- Outdoor: Grills, patio furniture, playsets, hunting and fishing gear.
- Storage: Holiday decorations, keepsakes, seasonal clothing.
Do high-value items need extra coverage?
Usually, yes. Standard policies cap theft coverage on categories like jewelry, watches, firearms, silverware and collectibles. Scheduling those items lists them at an appraised value and often covers accidental loss too. Learn more in our guide to
insuring higher-value homes and valuables.
Frequently asked questions
What is the easiest way to make a home inventory?
Record a slow video walkthrough of every room on your phone, narrating brands and ages, then upload it to cloud storage. You can add photos of receipts and serial numbers later.
Where should I store my home inventory?
Somewhere outside your home, like cloud storage, email or a safe deposit box, so it is available after a total loss.
How often should I update my home inventory?
At least once a year, and after major purchases, remodels, holidays or moving.
Do I need receipts for an insurance claim?
Receipts help but are not always required. Photos, videos, bank statements and credit card records can all support your claim.
How much personal property coverage do I need?
Total the replacement cost of everything in your inventory. Many policies set personal property at 50% to 70% of the dwelling limit, which may be too low or too high for your home.
Make sure your belongings are fully covered
Once your inventory is done, Miner Family Insurance can review your personal property limit and schedule valuables. We compare 50+ carriers and are rated 5.0 stars by 322 Google reviewers. Call (405) 724-2389 or
request a home insurance quote.