How to File a Homeowners Insurance Claim After a Disaster
By Josh Miner, a licensed agent and the founder of Miner Family Insurance in Edmond, OK. Updated October 2026.
Oklahoma sees it all: tornadoes, hail, straight-line winds, ice storms, and flash floods. When one hits your home, the first few days matter most.
This guide walks you through what to do right away and how to file a homeowners insurance claim. It also covers the mistakes that can slow down or shrink your payout.
What Should You Do First After a Disaster?
Safety comes before paperwork. Start here:
- Leave the home if it looks unstable, you smell gas, or power lines are down.
- Call 911 for emergencies and your utility company for gas or electric problems.
- Wait until it's safe before going back inside. Wear sturdy shoes and gloves when you do.
How to File a Homeowners Insurance Claim, Step by Step
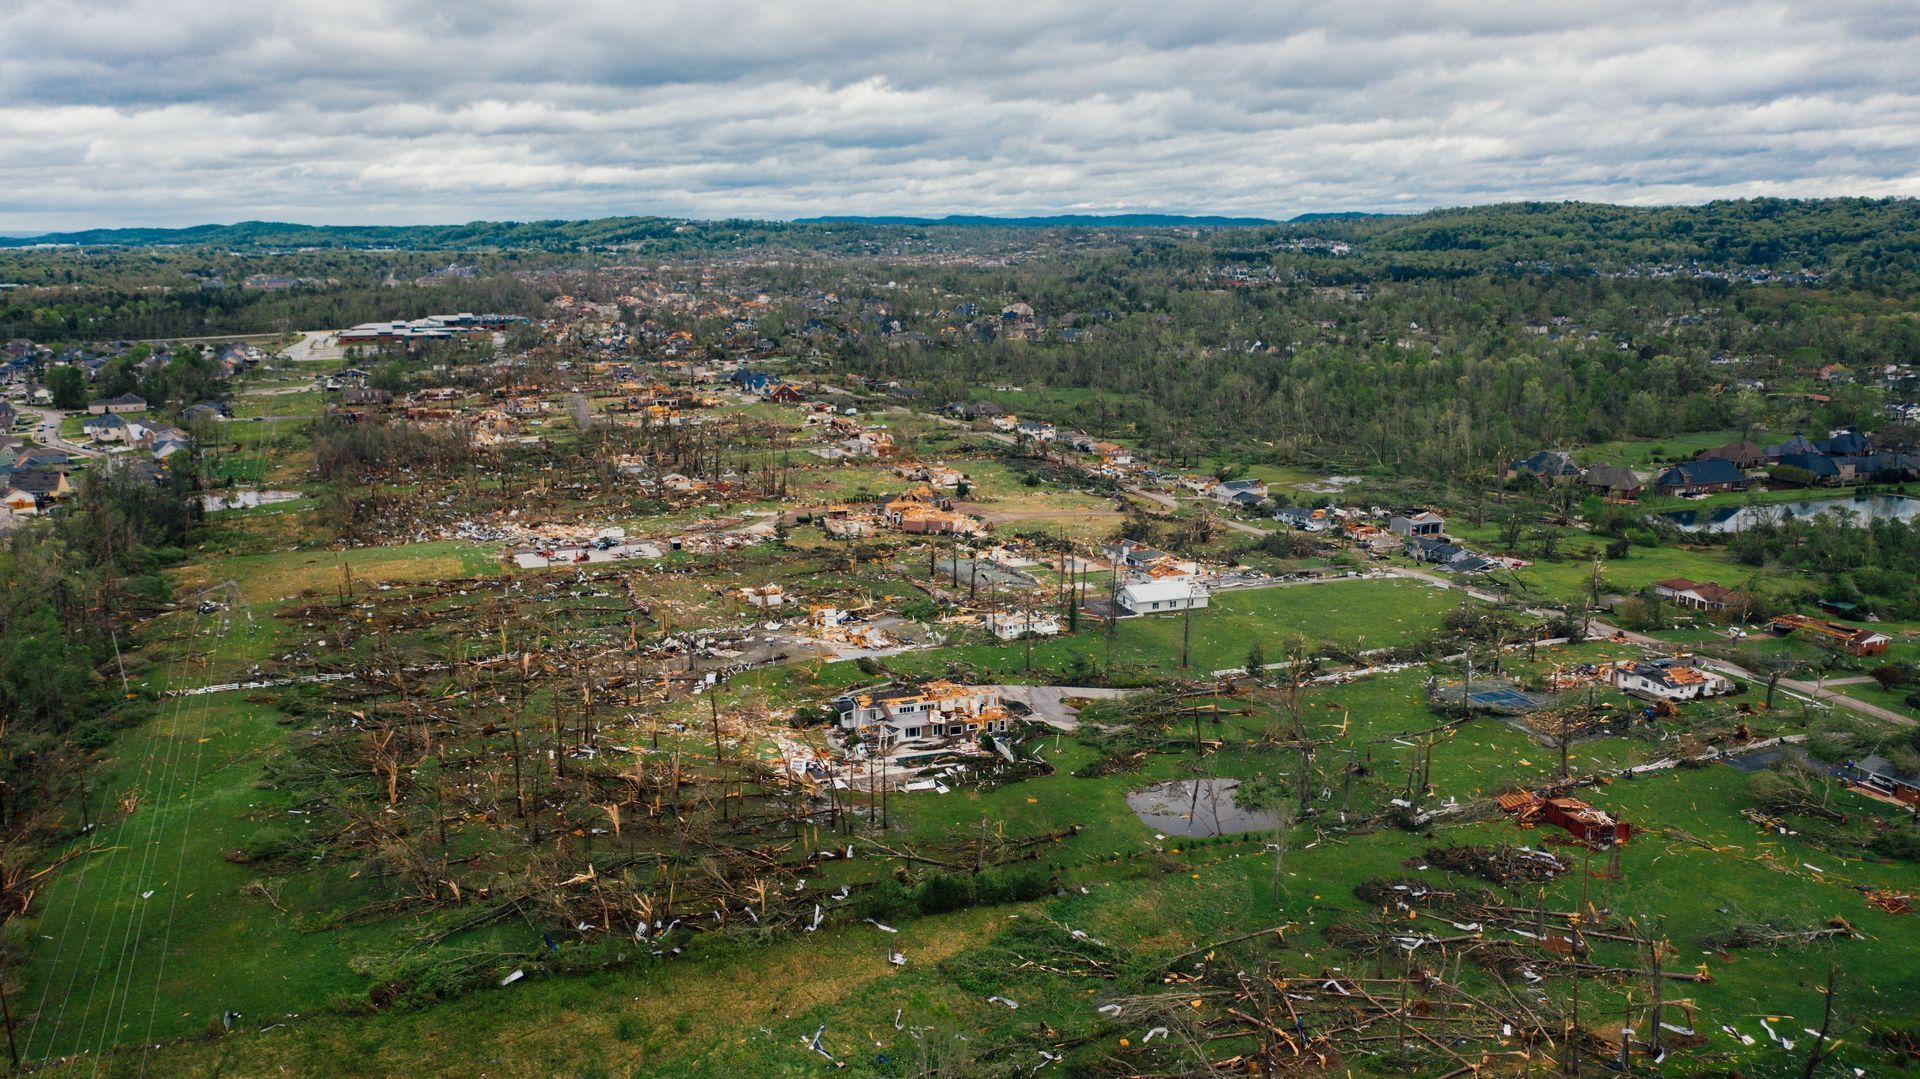
- Take photos before you clean up. Record video and photos of every damaged area, inside and out. Get close-ups of the roof, siding, windows, and belongings.
- Call your agent or insurer quickly. Your policy likely says you need to report damage quickly. After a big storm, carriers get flooded with calls, so filing early gets you in line sooner. Many carriers also let you file online or in an app.
- Prevent more damage. Tarp the roof, board up broken windows, and shut off the water if a pipe broke. Your insurer expects you to do this, and they'll usually pay you back. Keep every receipt.
- Hold off on permanent repairs. Wait until the adjuster has seen the damage, unless your insurer tells you otherwise.
- List your damaged belongings. Write down each item, its age, and what it cost. A home inventory makes this much easier.
- Meet the adjuster. Be there for the inspection and point out all the damage. Ask for the adjuster's name, your claim number, and a copy of the estimate.
- Get repair estimates. Use licensed, local contractors. If their estimate is higher than the adjuster's, send it to the adjuster and ask them to review it.
- Keep good records. Log every call with the date, the person's name, and what was said. Save all emails and letters.
What Does Homeowners Insurance Cover After a Disaster?
Most Oklahoma homeowners policies cover the storms we see most often. Here's a quick look:
- Tornado and wind damage: Usually covered.
- Hail damage: Usually covered, but it often comes with a separate wind and hail deductible.
- Ice storms: Damage from the weight of ice or a tree falling on your home is usually covered.
- Fire and lightning: Usually covered, including wildfire.
- Flood: Your homeowners policy won't pay for it. You'll need a separate flood policy.
- Earthquake: Not covered unless you added an earthquake endorsement.
Know Your Wind and Hail Deductible
A lot of Oklahoma policies have a percentage deductible for wind and hail. It's often 1% to 2% of your dwelling coverage. With $300,000 in dwelling coverage and a 2% deductible, you'd pay the first $6,000 of a hail claim. Check your declarations page now so it isn't a surprise later.
Additional Living Expenses
Your home may be unlivable after a covered loss. If so, loss of use coverage helps with extra costs like a hotel, rent, or meals. Keep every receipt and ask your adjuster about limits.
Does Homeowners Insurance Cover Flood?
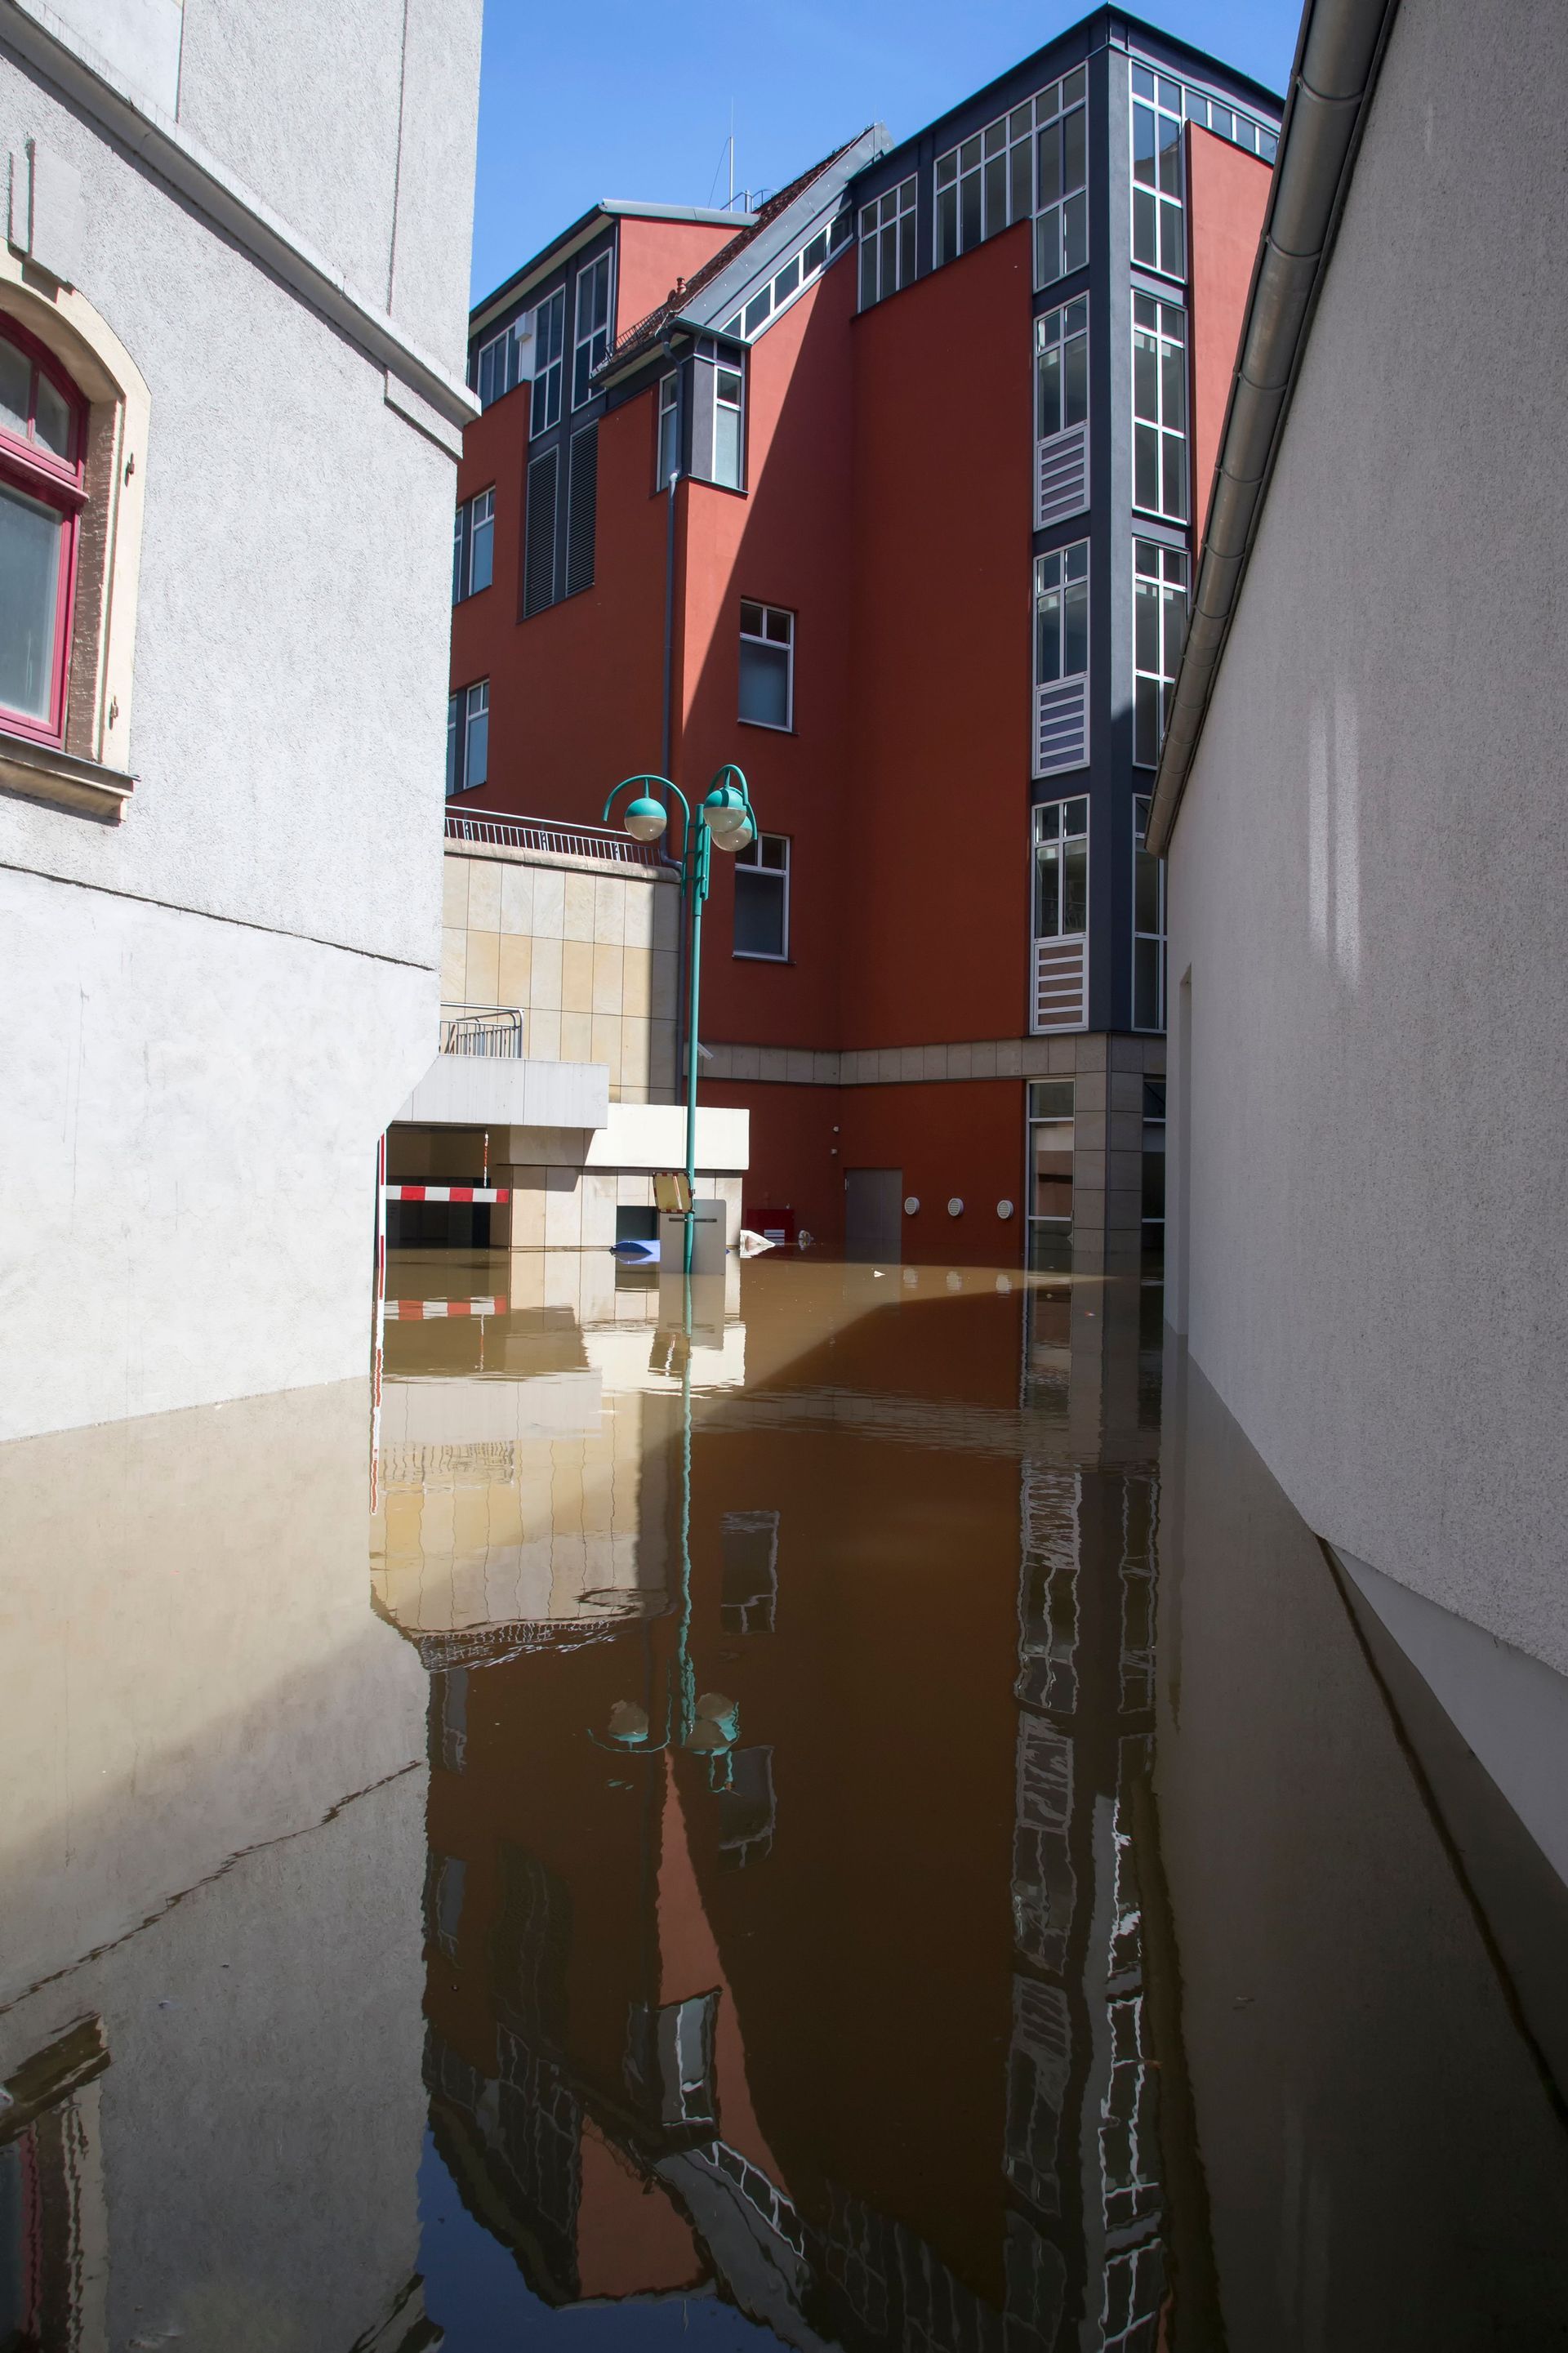
No. Standard homeowners policies don't cover flood damage, which is water that rises from outside and enters your home. A broken pipe inside the home is different and is usually covered.
If a storm brings both wind and flooding, you may file two claims. Wind damage goes to your home insurer, and flood damage goes to your flood carrier. The adjusters will sort out which damage came from which cause.
Flood Insurance Oklahoma Homeowners Should Know About
Flash floods can hit almost anywhere in the state, not just near rivers. Most families get their flood policy through the National Flood Insurance Program (NFIP), and private carriers sell it too.
NFIP policies usually have a 30-day waiting period, so don't wait for a storm warning. Get a flood insurance quote.
How Will Your Claim Be Paid? Replacement Cost vs Actual Cash Value
- Replacement cost pays to fix or replace things with new materials at today's prices.
- Actual cash value pays the current value, after taking off for age and wear.
With replacement cost, many insurers pay in two checks. The first check is the actual cash value. The second check covers the amount held back for age and wear.
You usually get it after the repairs are done and you send proof. Watch the deadline to claim it.
Older roofs are another catch. Many Oklahoma policies pay them at actual cash value or on a roof payment schedule. That can mean a much smaller check. For more on this, see our homeowners insurance myths guide.
If you have a mortgage, your claim check may be made out to you and your lender. Your lender may hold the money and release it as repairs move forward.
How Can You Spot Storm Chasers?
After big storms, out-of-town contractors often go door to door. Protect yourself with these tips:
- Make sure any roofer is registered with the Oklahoma Construction Industries Board.
- Get written estimates, and never pay the full amount up front.
- Read any contract carefully before you sign, especially one that lets a contractor deal with your insurer for you.
- Walk away from anyone who offers to cover or waive your deductible. That can be insurance fraud.
How Can You Prepare Before the Next Storm?
A little prep work now makes a future claim faster and less stressful:
- Make a home inventory. Walk through each room and take a video, opening closets and drawers.
- Photograph your home's outside. Get clear shots of the roof, siding, fences, and outbuildings so you have a "before" record.
- Save your documents online. Keep your policy, inventory, and receipts in cloud storage you can reach from your phone.
- Know your deductibles. Look up your wind and hail deductible and set money aside to cover it.
- Trim nearby trees. Cut back dead limbs that could fall on your roof in a storm or ice event.
- Ask about flood coverage. Because of the 30-day wait, the best time to buy flood insurance is before you need it.
Where Can You Get Help Beyond Insurance?
- FEMA: If the president declares a major disaster, you can apply for help at DisasterAssistance.gov. FEMA aid helps with needs insurance doesn't cover, so file with your insurer first.
- SBA disaster loans: The Small Business Administration offers low-interest disaster loans to homeowners, not just businesses.
- Oklahoma Insurance Department: If you run into problems with a claim, the department can answer questions and take complaints.
Frequently Asked Questions
How long do I have to file a homeowners insurance claim?
It depends on your policy, but you should report damage as soon as you can. Look for deadlines in your policy too, including the one for your second check.
Does homeowners insurance cover flood?
No. You need a separate flood policy from the NFIP or a private carrier. Water from a burst pipe inside your home is usually covered.
Will insurance pay for a hotel while my home is repaired?
Yes, if a covered loss makes your home unlivable. Your loss of use coverage pays the extra living costs, up to your limit.
What is the difference between replacement cost vs actual cash value?
Replacement cost pays to repair or replace with new materials. Actual cash value pays the current value after age and wear, which is usually less.
Should I hire a public adjuster?
Most claims don't need one. Public adjusters charge a share of your claim payment, so talk with your agent first if you're unhappy with an offer.
Talk to an Edmond Insurance Agent
We're Miner Family Insurance, a local, independent agency right here in Edmond. We shop more than 50 carriers, and we never charge fees. We'd be glad to look over your wind and hail deductible and flood coverage before the next storm. Call 405-724-2389 or request a home insurance quote online.