What Does Homeowners Insurance Cover? An Oklahoma Guide
Joshua Miner • March 6, 2023
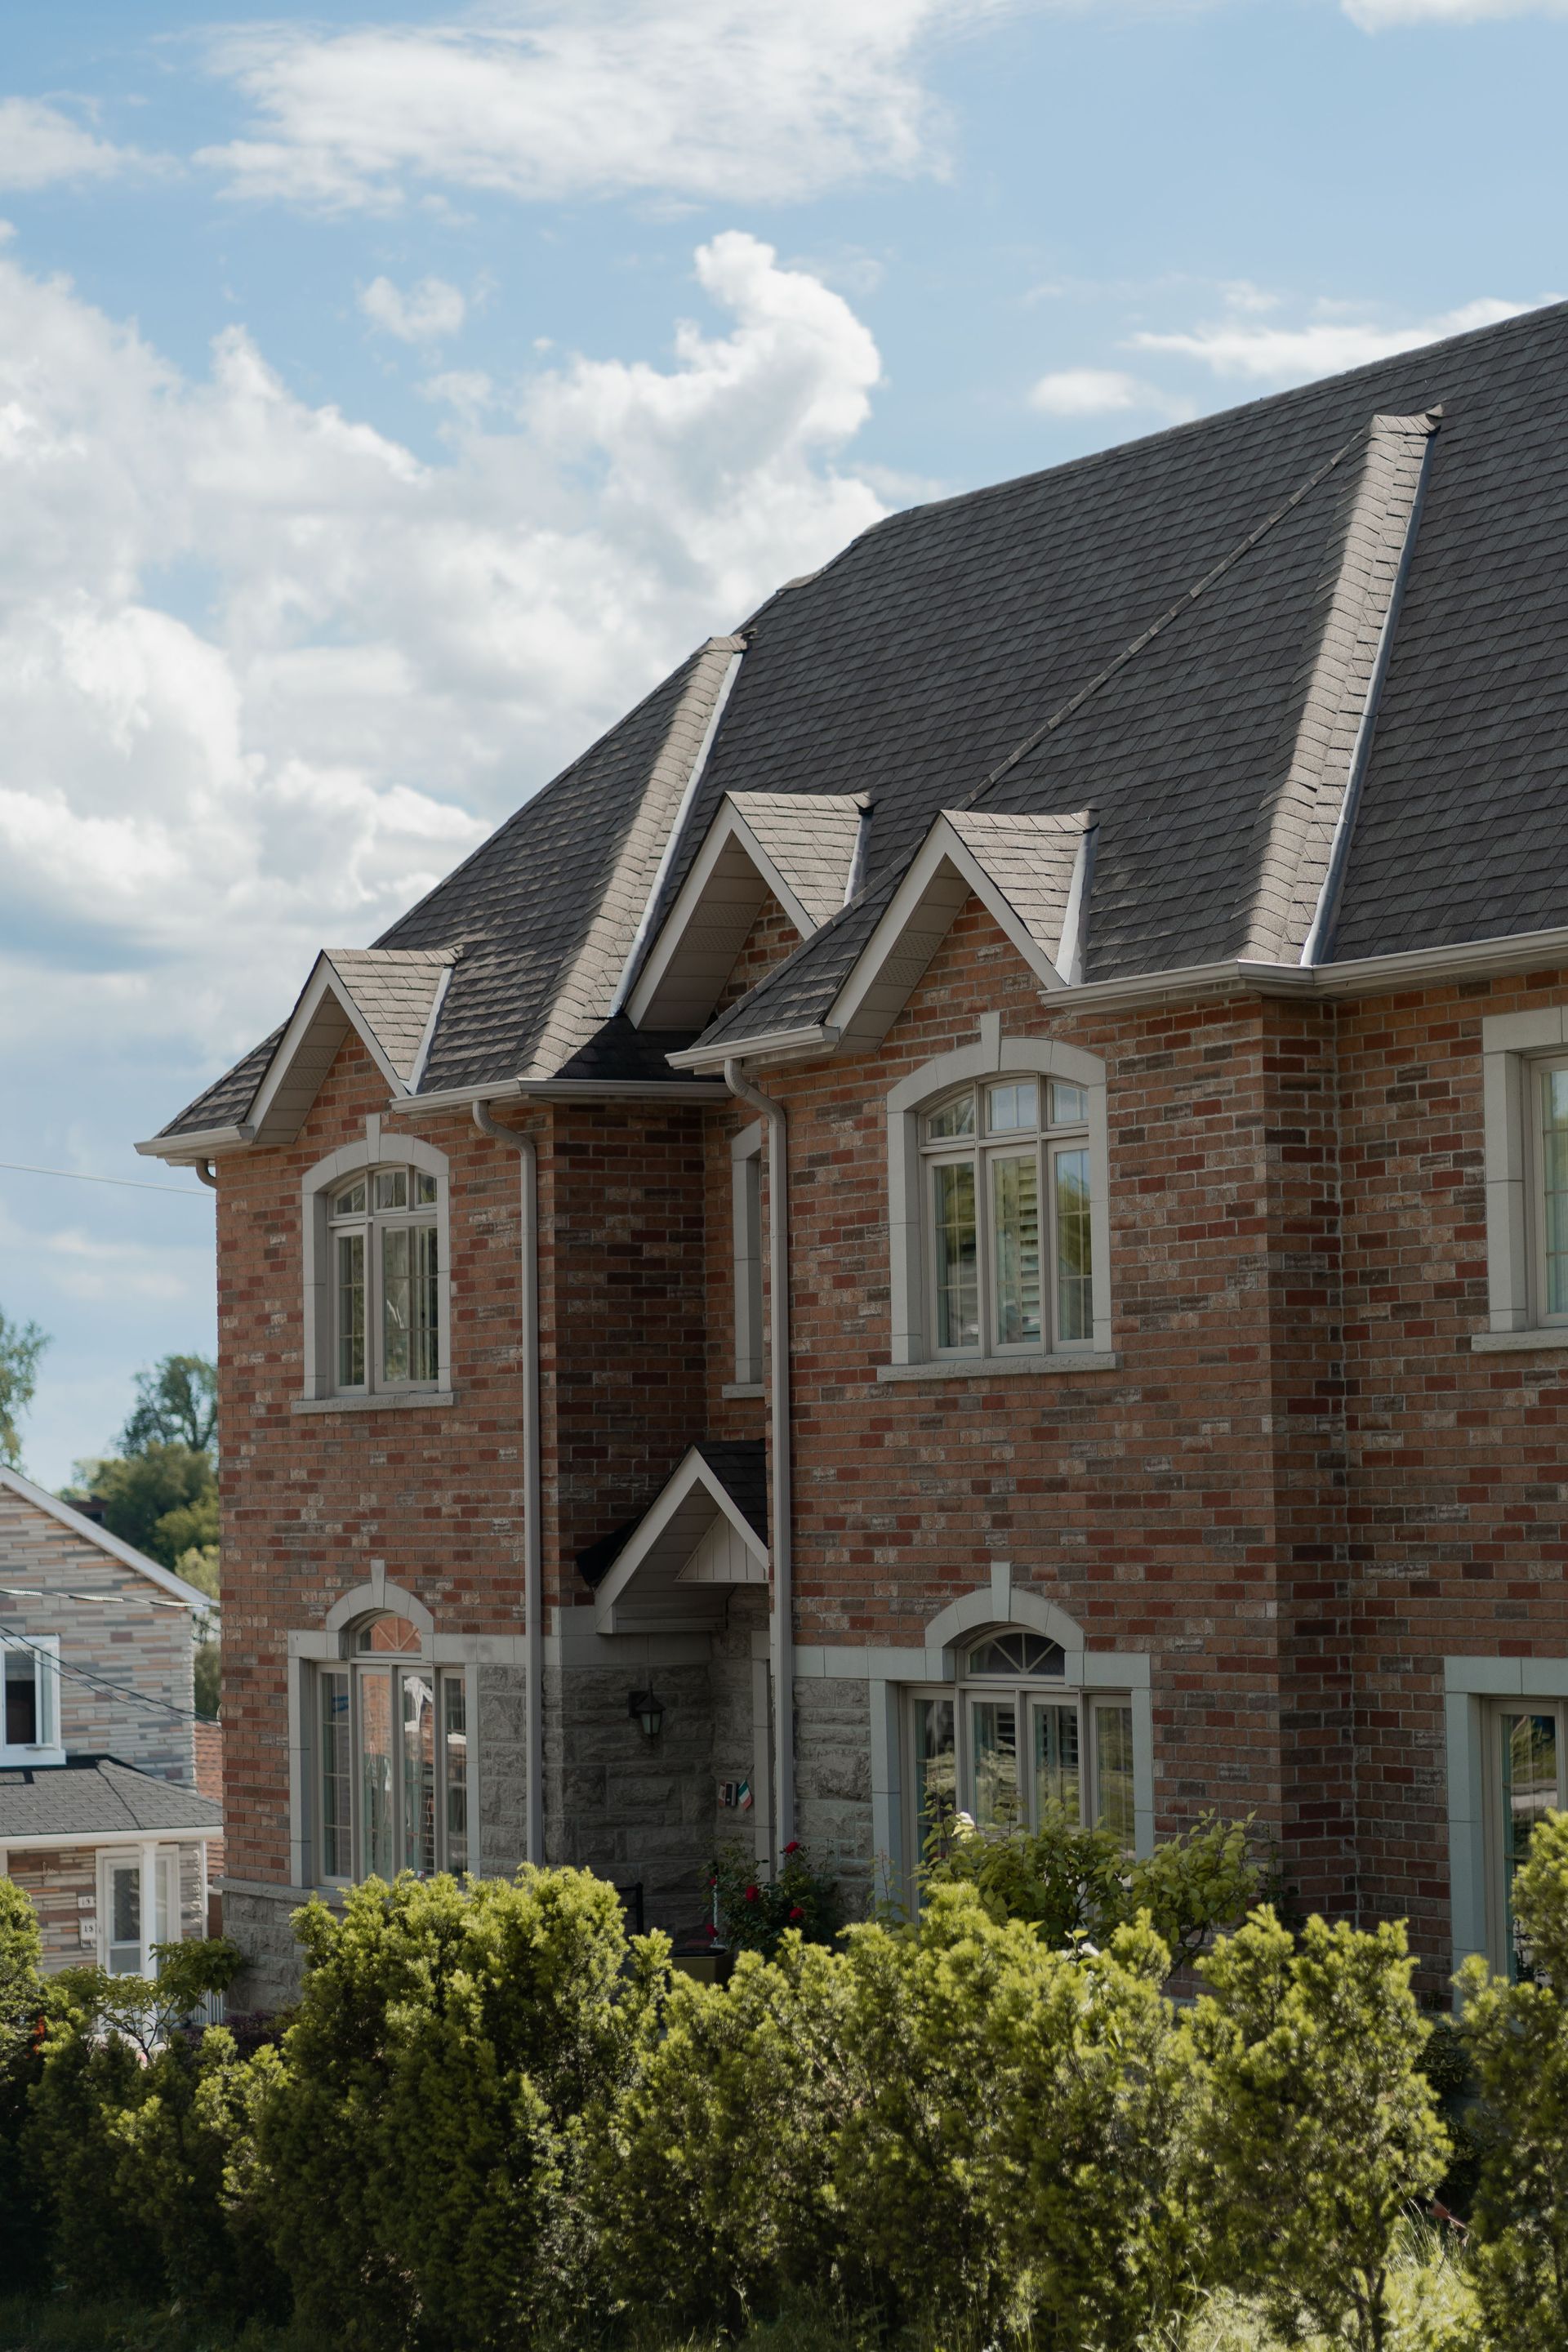
Brick home exterior representing Oklahoma home insurance coverage basics

What Does Homeowners Insurance Cover? An Oklahoma Guide


By Josh Miner, licensed agent and owner of Miner Family Insurance, an independent agency in Edmond, Oklahoma, since 2020.

Updated October 2026


Home insurance (also called homeowners insurance) protects your house, your belongings, and your finances if something goes wrong. Buying your first home in Oklahoma? Or just want to understand the policy you have? This guide covers what homeowners insurance covers, the main home insurance policy types, how escrow works, and the coverage you may need to add.


What Is Home Insurance?


Home insurance is a contract between you and an insurance company. You pay a premium. In return, the company pays for covered damage to your home and belongings, minus your deductible. A standard homeowners insurance policy covers common perils like fire, wind, hail, theft, and vandalism. Some risks, such as flood and earthquake, are excluded and need separate coverage.


If you have a mortgage, your lender will almost always require home insurance until the loan is paid off.


Buying your first home? Read about the benefits of home insurance for first-time homebuyers.


What Does Homeowners Insurance Cover?


Most policies are built from the same six parts. You can customize your policy by adjusting the limits on each one:


  • Dwelling coverage: Pays to repair or rebuild the structure of your home, including the walls, roof, floors, foundation, and built-in appliances.
  • Other structures: Covers detached structures like fences, sheds, and detached garages.
  • Personal property: Protects your belongings, such as furniture, electronics, and clothing.
  • Loss of use (additional living expenses): Pays for temporary housing, meals, and other extra costs if a covered loss makes your home unlivable.
  • Liability coverage: Protects you if someone is injured on your property or you accidentally damage someone else's property.
  • Medical payments: Covers small medical bills for guests injured at your home, regardless of fault.


What Are the Types of Home Insurance Policies?


Every home insurance policy is built on a standard form, and the form decides which perils are covered. For a deeper look, see our guide to homeowners insurance policy forms.


  • HO-1 (basic form): Covers a short list of named perils, such as fire and theft. It is rarely sold today.
  • HO-2 (broad form): Covers a longer list of named perils, including falling objects, the weight of ice or snow, and accidental water discharge.
  • HO-3 (special form): The most common policy. It covers your home against all perils except those the policy specifically excludes, and covers your belongings against a list of named perils.
  • HO-4 (renters): For tenants. It covers personal belongings and liability, but not the building.
  • HO-5 (comprehensive form): The broadest coverage. It covers both your home and your belongings against all perils except those excluded.
  • HO-6 (condo): For condo owners. It covers your unit's interior, your belongings, and your liability.


Carriers do not all word their policies the same way, so it pays to compare the actual coverage, not just the form name.


How Does Personal Property Coverage Work?


The personal property coverage homeowners insurance includes pays to repair or replace your belongings after a covered loss, like a fire, a break-in, or a storm. The limit is usually set at 50% to 70% of your dwelling coverage, and it typically covers your belongings even when they are away from home.


Two details are worth checking:


  • Replacement cost vs. actual cash value: Replacement cost pays what it costs to buy a new item. Actual cash value subtracts depreciation, so you get less.
  • Special limits: Jewelry, firearms, and collectibles usually have low limits for theft. If you own high-value items, you can schedule them separately for full coverage.


What Is Additional Living Expenses Coverage?


If a fire, tornado, or other covered loss forces you out of your home, additional living expenses coverage (also called loss of use) helps pay for a hotel or rental, extra meals, and other costs above your normal budget while your home is being repaired. It is usually set as a percentage of your dwelling coverage or a set time period, so check your limit.


How Much Homeowners Liability Coverage Do You Need?


Homeowners liability coverage protects you if someone is hurt at your home or you accidentally damage someone else's property. It can pay for the other person's medical bills, your legal defense, and any settlement or judgment, up to your limit.


Common examples include a guest slipping on your steps, your dog biting a visitor, or a tree on your property falling on a neighbor's car. Most policies start at $100,000 of liability coverage, but many homeowners choose $300,000 or more, and an umbrella policy can add another layer on top.


Does Homeowners Insurance Cover Hail, Water Damage, and Theft?


A standard HO-3 policy covers many perils beyond fire. Here are the ones Oklahoma homeowners ask about most.


Wind and Hail Damage in Oklahoma


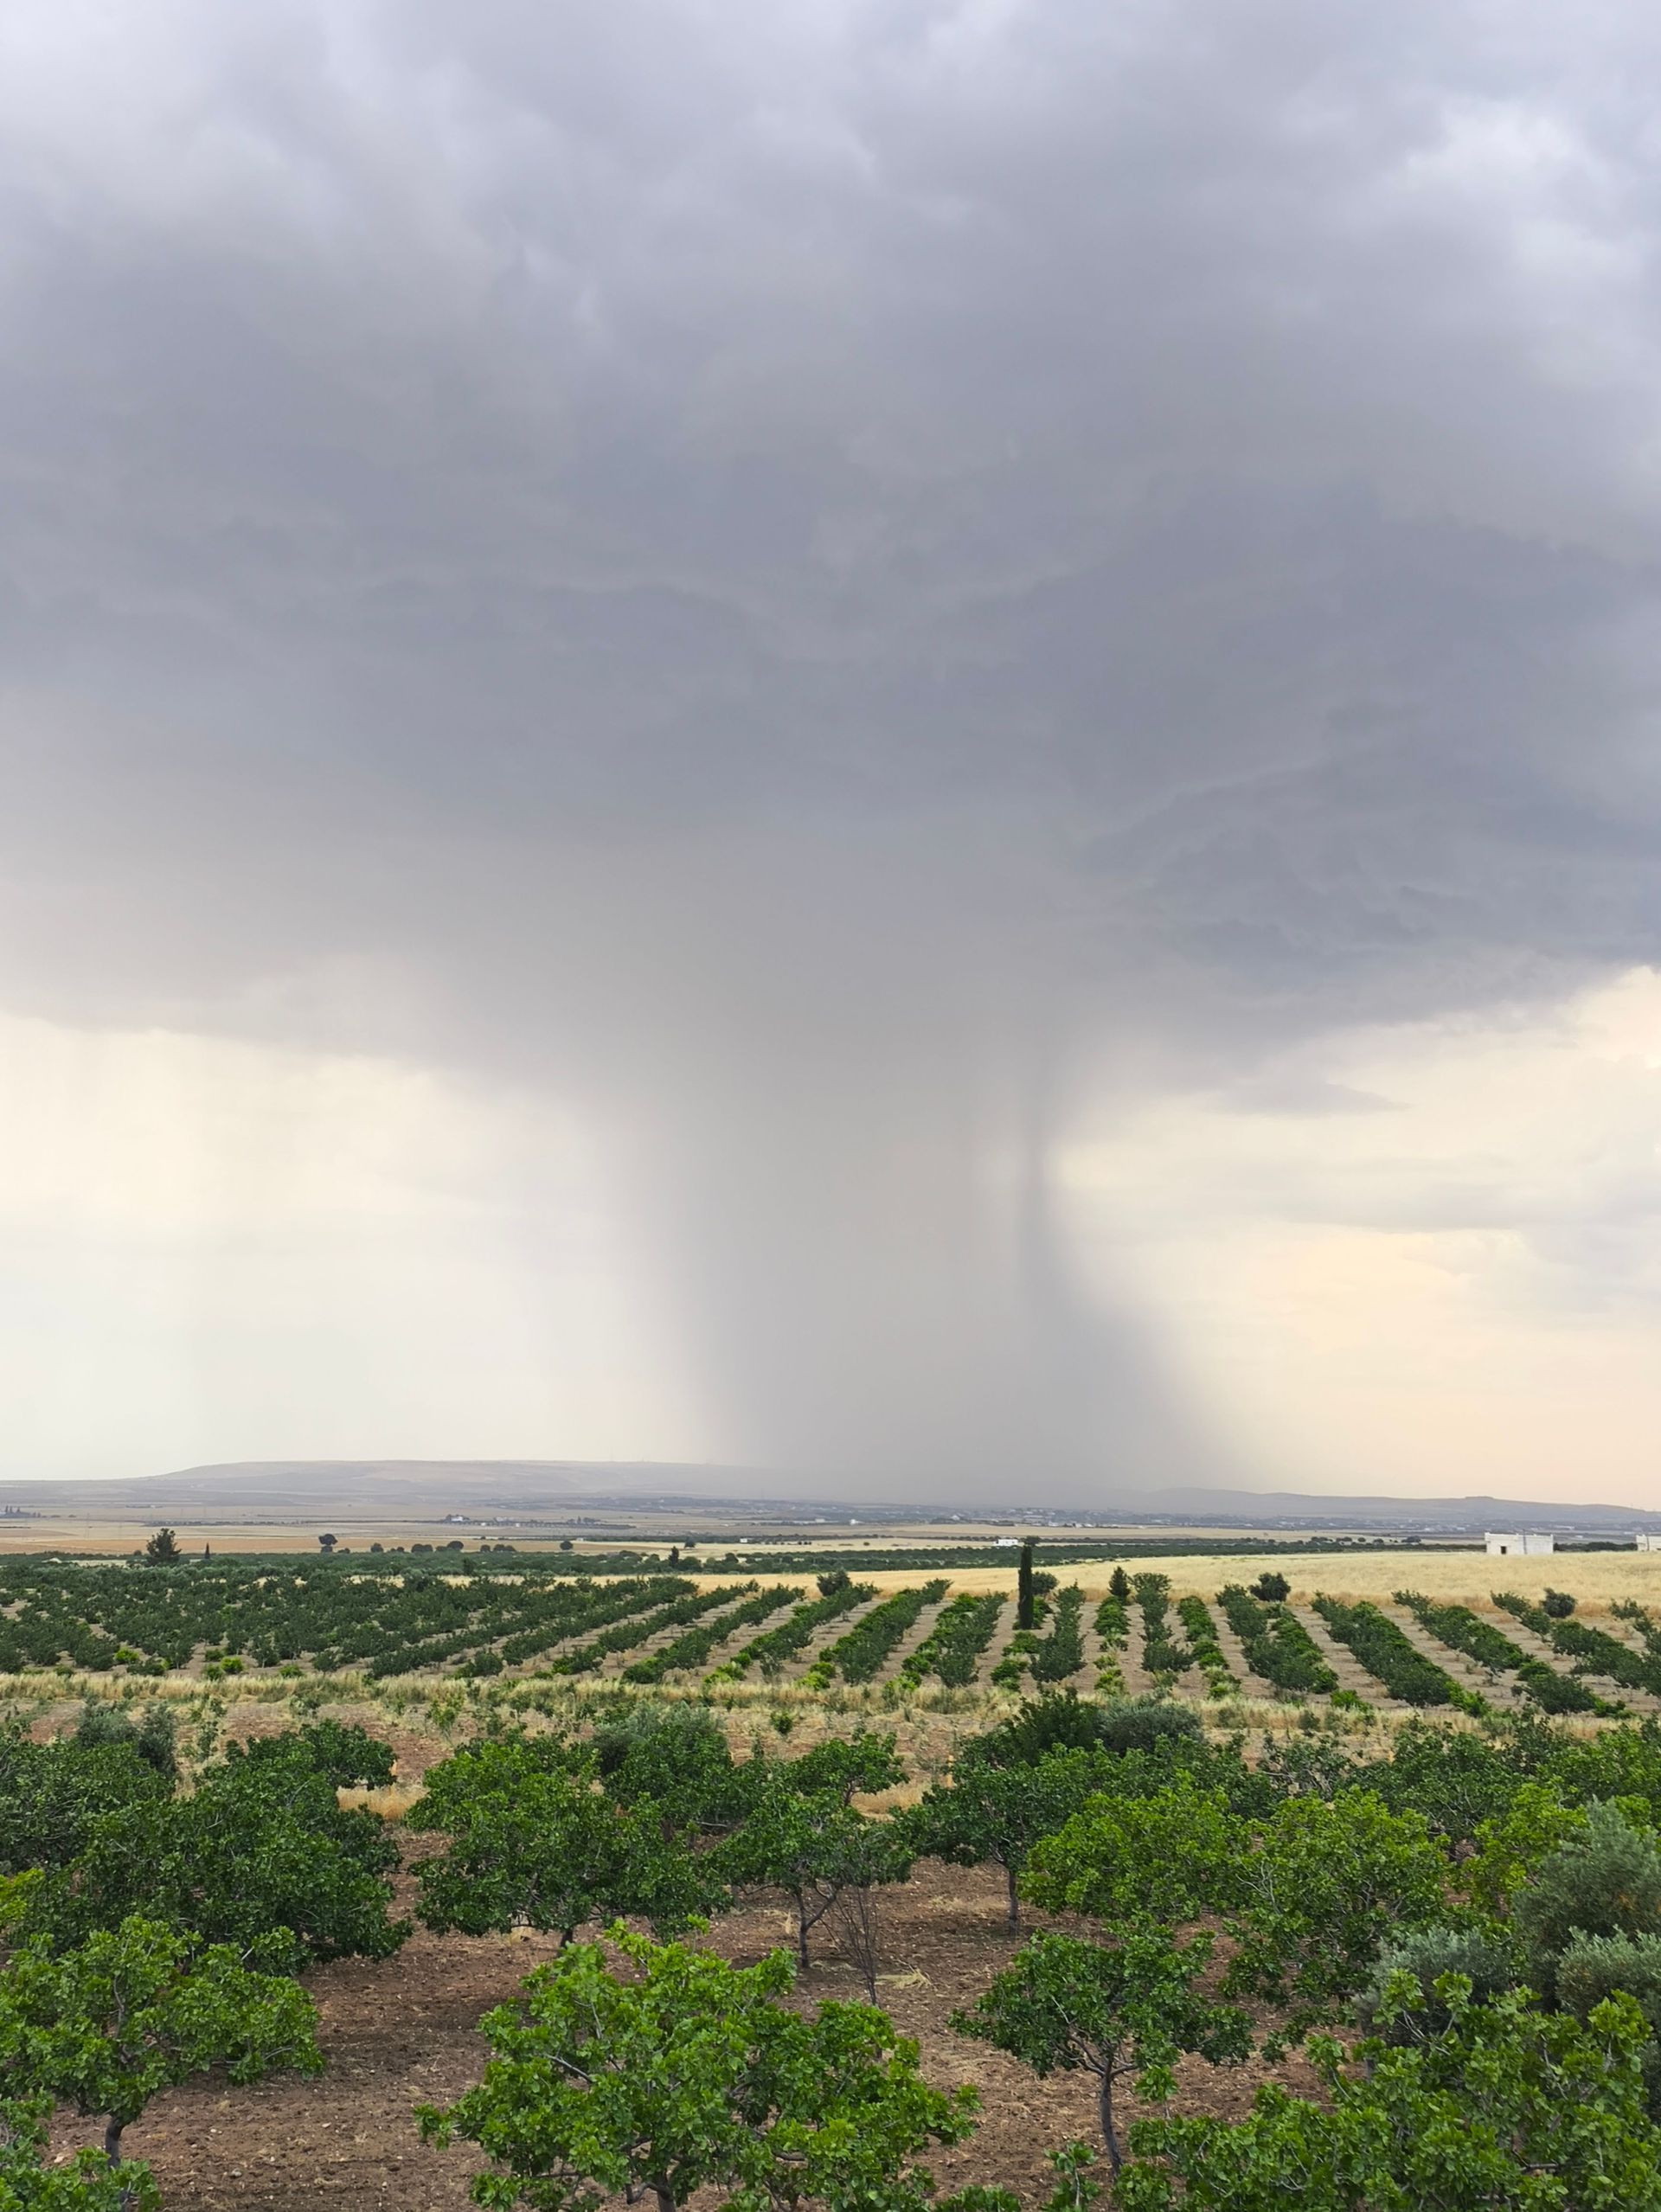
Wind and hail are covered, but in Oklahoma many policies carry a separate wind/hail deductible, often a percentage of your dwelling coverage. A 2% deductible on a $300,000 home means you pay the first $6,000 of a hail claim. Some homeowners add a wind/hail deductible buyback policy to reduce that cost.
Hail storm over Oklahoma farmland, a common cause of wind and hail homeowners insurance claims

Weight of Ice, Snow, or Sleet


Damage from the weight of ice, snow, or sleet, such as a sagging or collapsed roof, is generally covered. Oklahoma ice storms make this one worth knowing about.


Water Damage


Sudden and accidental water damage, like a burst pipe or a failed water heater, is usually covered. Damage from slow leaks you did not fix, and from water backing up through a drain or sump pump, usually is not. Water backup coverage can be added for a small cost.


Vandalism and Riot


Damage from vandalism, malicious mischief, riot, and civil commotion is typically covered under a standard policy. Some policies limit vandalism coverage if a home has been vacant for a long period (often 60 days or more).


Theft and Burglary


If someone breaks in, your policy covers stolen belongings up to your personal property limit, plus damage to doors, windows, and locks. Remember the special limits on jewelry and other valuables mentioned above.


What Coverage Do You Need to Add?


Some risks are excluded from standard homeowners insurance and need their own coverage.


Earthquake Insurance in Oklahoma


Earthquake damage is not covered by a standard policy. Oklahoma saw a sharp rise in earthquakes in the 2010s, which made earthquake insurance Oklahoma homeowners once ignored worth a second look. You can usually add it to your policy as an endorsement, and it usually has its own deductible, often a percentage of your dwelling coverage.


Does Homeowners Insurance Cover Flood?


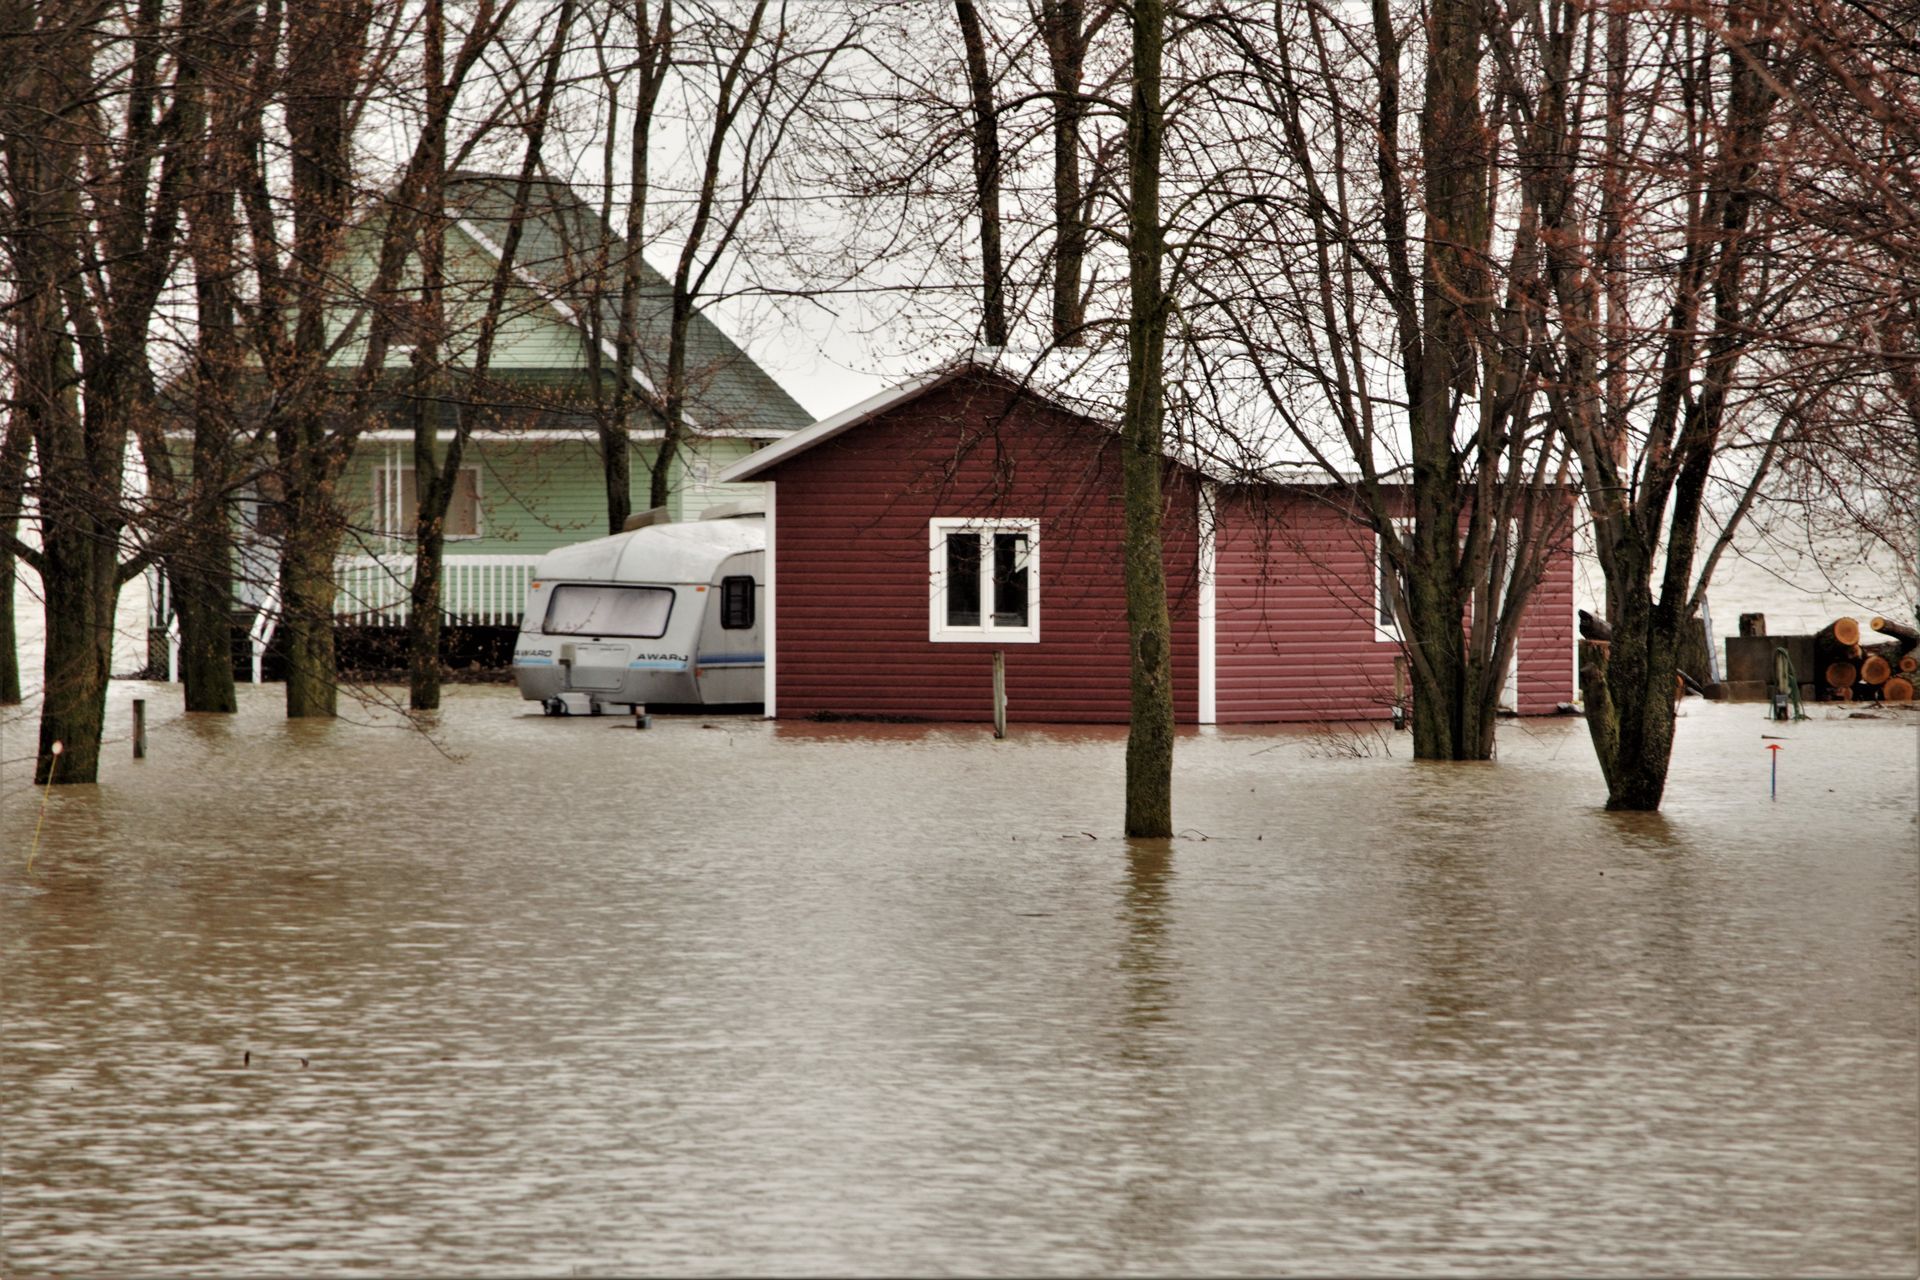
Flood insurance is never included in a standard home policy. You can buy it through the National Flood Insurance Program (NFIP) or from a private flood carrier. NFIP policies usually have a 30-day waiting period, so do not wait until a storm is in the forecast. Heavy rain can flood homes outside of mapped flood zones too.

Oklahoma house surrounded by floodwater, damage not covered by standard homeowners insurance without flood insurance

If your home is damaged by a storm or other natural disaster, our guide walks through what to do next.


How Does Home Insurance Work With Escrow?


If you have a mortgage, your lender usually pays your home insurance through an escrow account. Each monthly mortgage payment includes a share of your yearly premium, and the lender pays the insurance company when your policy renews.


When your premium goes up, the lender adjusts your escrow amount, usually at its yearly escrow review, and your monthly mortgage payment rises to match. Shopping your homeowners insurance before renewal is one of the best ways to keep that payment in check.


If your mortgage payment jumped, read Did Your Mortgage Payment Go Up? Thinking about changing carriers? Here is how to switch home insurance in Oklahoma without a gap in coverage.


How Much Is Home Insurance in Oklahoma?


Compared with most states, the homeowners insurance Oklahoma residents buy costs more because of hail, wind, and tornado risk. Your premium depends mostly on these factors:


  • Roof age and material: Older roofs cost more to insure, and some carriers only pay actual cash value on an aging roof. Impact-resistant shingles can earn a discount.
  • Wind/hail deductible: A higher percentage deductible lowers your premium but raises what you pay after a storm.
  • Credit-based insurance score: Most carriers in Oklahoma use it, and a stronger score usually means a lower rate.
  • Claims history: Recent claims on your home, or on you as a policyholder, can raise your premium.
  • Location: Distance to a fire station, local hail history, and neighborhood claim trends all play a role.


For a full breakdown of Oklahoma rates, read Why Is Home Insurance So Expensive in Oklahoma?


Frequently Asked Questions


Does homeowners insurance cover hail damage in Oklahoma?


Yes. Hail is a covered peril on standard homeowners insurance, but most Oklahoma policies apply a separate wind/hail deductible, often 1% to 2% of your dwelling coverage.


Does homeowners insurance cover tornado damage?


Yes. Wind damage from a tornado is covered on standard policies, subject to your wind/hail deductible. Additional living expenses coverage helps if you cannot live in your home during repairs.


Is home insurance required in Oklahoma?


No state law requires it, but your mortgage lender will require it until your loan is paid off.


Is flood insurance required in Oklahoma?


Only if your lender requires it, which usually happens when your home is in a FEMA high-risk flood zone. Even outside those zones, flood insurance is worth considering because standard policies exclude flooding.


Does homeowners insurance cover earthquakes in Oklahoma?


No. Earthquake damage is excluded from standard policies, but you can usually add earthquake coverage as an endorsement.


Does escrow pay for home insurance?


Yes, if your mortgage has an escrow account. Your lender collects part of your yearly premium with each monthly payment and pays your insurance company when the policy renews.


Does home insurance come out of escrow?


Usually, yes. If your mortgage includes escrow, your homeowners insurance premium is paid from that account once a year. Without escrow, you pay the insurance company directly.


Talk to an Edmond Home Insurance Agent


Miner Family Insurance is an independent agency in Edmond, Oklahoma. We compare homeowners insurance from dozens of carriers to find the right coverage at a fair price. Call us at (405) 724-2389 or request a home insurance quote online.

Suburban house with landscaped yard, white garage, and red fence under a clear blue sky
By Joshua Miner • October 27, 2026
Oklahoma home insurance averages $4,700 to $7,700 a year in 2026, double the U.S. An Edmond agent explains why and shares real local rates by city.
Aerial view of an Edmond-area neighborhood where home insurance rates vary
By Joshua Miner • October 23, 2026
Why is my home insurance so high? Learn why Edmond neighbors pay different rates, from roofs and credit to discounts, and how to lower your premium.
Home insurance graphic with hands supporting a small house and text about guest injuries at home
By Joshua Miner • October 23, 2026
Does homeowners insurance cover guest injuries? An Edmond agent explains premises liability, what to do after a guest is hurt, and umbrella coverage.
Large brick-and-siding suburban house with a front porch, dormer windows, and a green lawn under a blue sky
By Joshua Miner • October 23, 2026
Choosing Edmond home insurance? A local agent explains rebuild cost, extended replacement cost coverage, liability limits, deductibles, and more.
Snow-covered log cabins and evergreen trees in a winter village scene
By Joshua Miner • October 23, 2026
Ice storm, fallen tree, or frozen pipes? An Edmond agent explains what Oklahoma homeowners insurance covers in winter and how loss of use works.
Home insurance graphic with house in hands and text: “What to Do If Your Home Is Damaged in a Natural Disaster”
By Joshua Miner • October 23, 2026
Tornado, hail, or flood damage? An Edmond agent explains how to file a homeowners insurance claim in Oklahoma and what your policy covers.
Woman working on a laptop at her kitchen table, running a business from home
By Joshua Miner • October 23, 2026
Running a business from your Edmond home? Learn what home insurance covers, what it doesn't, and your options for home based business insurance.
Red umbrella in the rain, a symbol of umbrella liability insurance
By Joshua Miner • October 23, 2026
Learn how homeowners liability coverage protects Oklahoma families, how much personal liability coverage you need, and when umbrella insurance makes sense.
Two-story brick home protected by extended replacement cost coverage
By Joshua Miner • October 23, 2026
What is extended replacement cost coverage? Learn how it protects Oklahoma homes when rebuild costs rise, how it differs from guaranteed replacement cost.
Woman holding house keys beside a red model house on a table, with a laptop in the background
By Joshua Miner • October 23, 2026
Home safety tips from an Edmond, OK agent: prevent house fires, frozen pipes, water damage, and break-ins to avoid homeowners insurance claims.
Show More