Does Homeowners Insurance Cover Guest Injuries?
By Josh Miner, a licensed agent and the founder of Miner Family Insurance in Edmond, OK. Updated October 2026.
A guest slips on your icy front steps. A neighbor's child gets hurt on your trampoline. Your dog nips a friend at a cookout. Moments like these are stressful, and the next steps matter.
Below, you'll learn what to do right away and how homeowners liability works in Oklahoma. You'll also see how to check that your coverage is high enough.
What to Do If a Guest Is Injured in Your Home
- Make sure they get medical help. Call 911 for anything serious. For minor injuries, offer first aid or a ride to urgent care.
- Avoid admitting fault. Be kind and helpful, but don't say it was your fault or promise to pay. Fault gets sorted out later.
- Write down what happened. Take photos of the area, note the time and conditions, and get the names of any witnesses.
- Call your agent or insurer quickly. Report it even if your guest says they won't file a claim. Late reporting can cause problems.
- Fix the hazard. Repair the step, salt the walkway, or lock the gate so it doesn't happen again.
- Let your insurer handle it. If the guest or an attorney contacts you, refer them to your claims adjuster. Your policy usually pays for your legal defense.
What Happens After You Report a Guest Injury?
Once you report the injury, your insurer assigns a claims adjuster. Here's how it usually goes:
- The adjuster gathers facts. They'll ask what happened, look at your photos, and may talk to witnesses.
- Medical payments come first. For small injuries, med pay can cover the bills quickly without anyone proving fault.
- Liability is reviewed. Sometimes a guest asks for more, like lost wages or pain and suffering. Then the adjuster decides if you're legally responsible.
- Your insurer defends you. If the guest sues, your carrier hires and pays for a lawyer to defend you. On most policies, defense costs don't reduce your liability limit.
- The claim is settled or closed. Most guest injury claims settle without going to court.
Does Homeowners Insurance Cover Guest Injuries?
In most cases, yes. Standard homeowners policies include two coverages that apply when a visitor gets hurt:
- Personal liability (Coverage E) pays for injuries you're legally responsible for, plus your legal defense. Limits often start at $100,000.
- Medical payments to others (Coverage F) pays small medical bills no matter who is at fault, often $1,000 to $5,000. It can settle a minor injury quickly, before it turns into a lawsuit.
Some injuries usually aren't covered. These include injuries to people who live in your home and injuries tied to a home business. Intentional acts aren't covered either. Some carriers also exclude certain dog breeds or trampolines, so check your policy.
How Does Premises Liability Work in Oklahoma?
Premises liability means property owners must keep their property reasonably safe for visitors. Oklahoma, like most states, owes different duties to different visitors:
- Invitees, such as contractors or customers, are owed the most care. You need to look for hazards and fix them.
- Licensees include most social guests. You need to warn them about dangers you already know about.
- Trespassers are owed the least, with an important exception for children.
To win a claim, an injured guest usually has to prove one thing. You knew, or should have known, about a hazard and didn't fix it or warn them.
Common Types of Premises Liability Claims
These are the types of premises liability claims we see most often at homes:
- Slips and falls on wet floors, icy steps, or loose rugs
- Trips on uneven walkways or in poor lighting
- Falls from broken railings or decks
- Dog bites (in Oklahoma, owners are usually liable if the person was there lawfully and didn't provoke the dog)
- Pool and trampoline injuries
- Falling tree limbs
What Do Guest Injury Claims Look Like in Real Life?
A friend slips on icy steps
This is a classic liability claim. Med pay may handle a small bill. A serious fall, like a broken hip, would go to your liability coverage.
Your dog bites a visitor
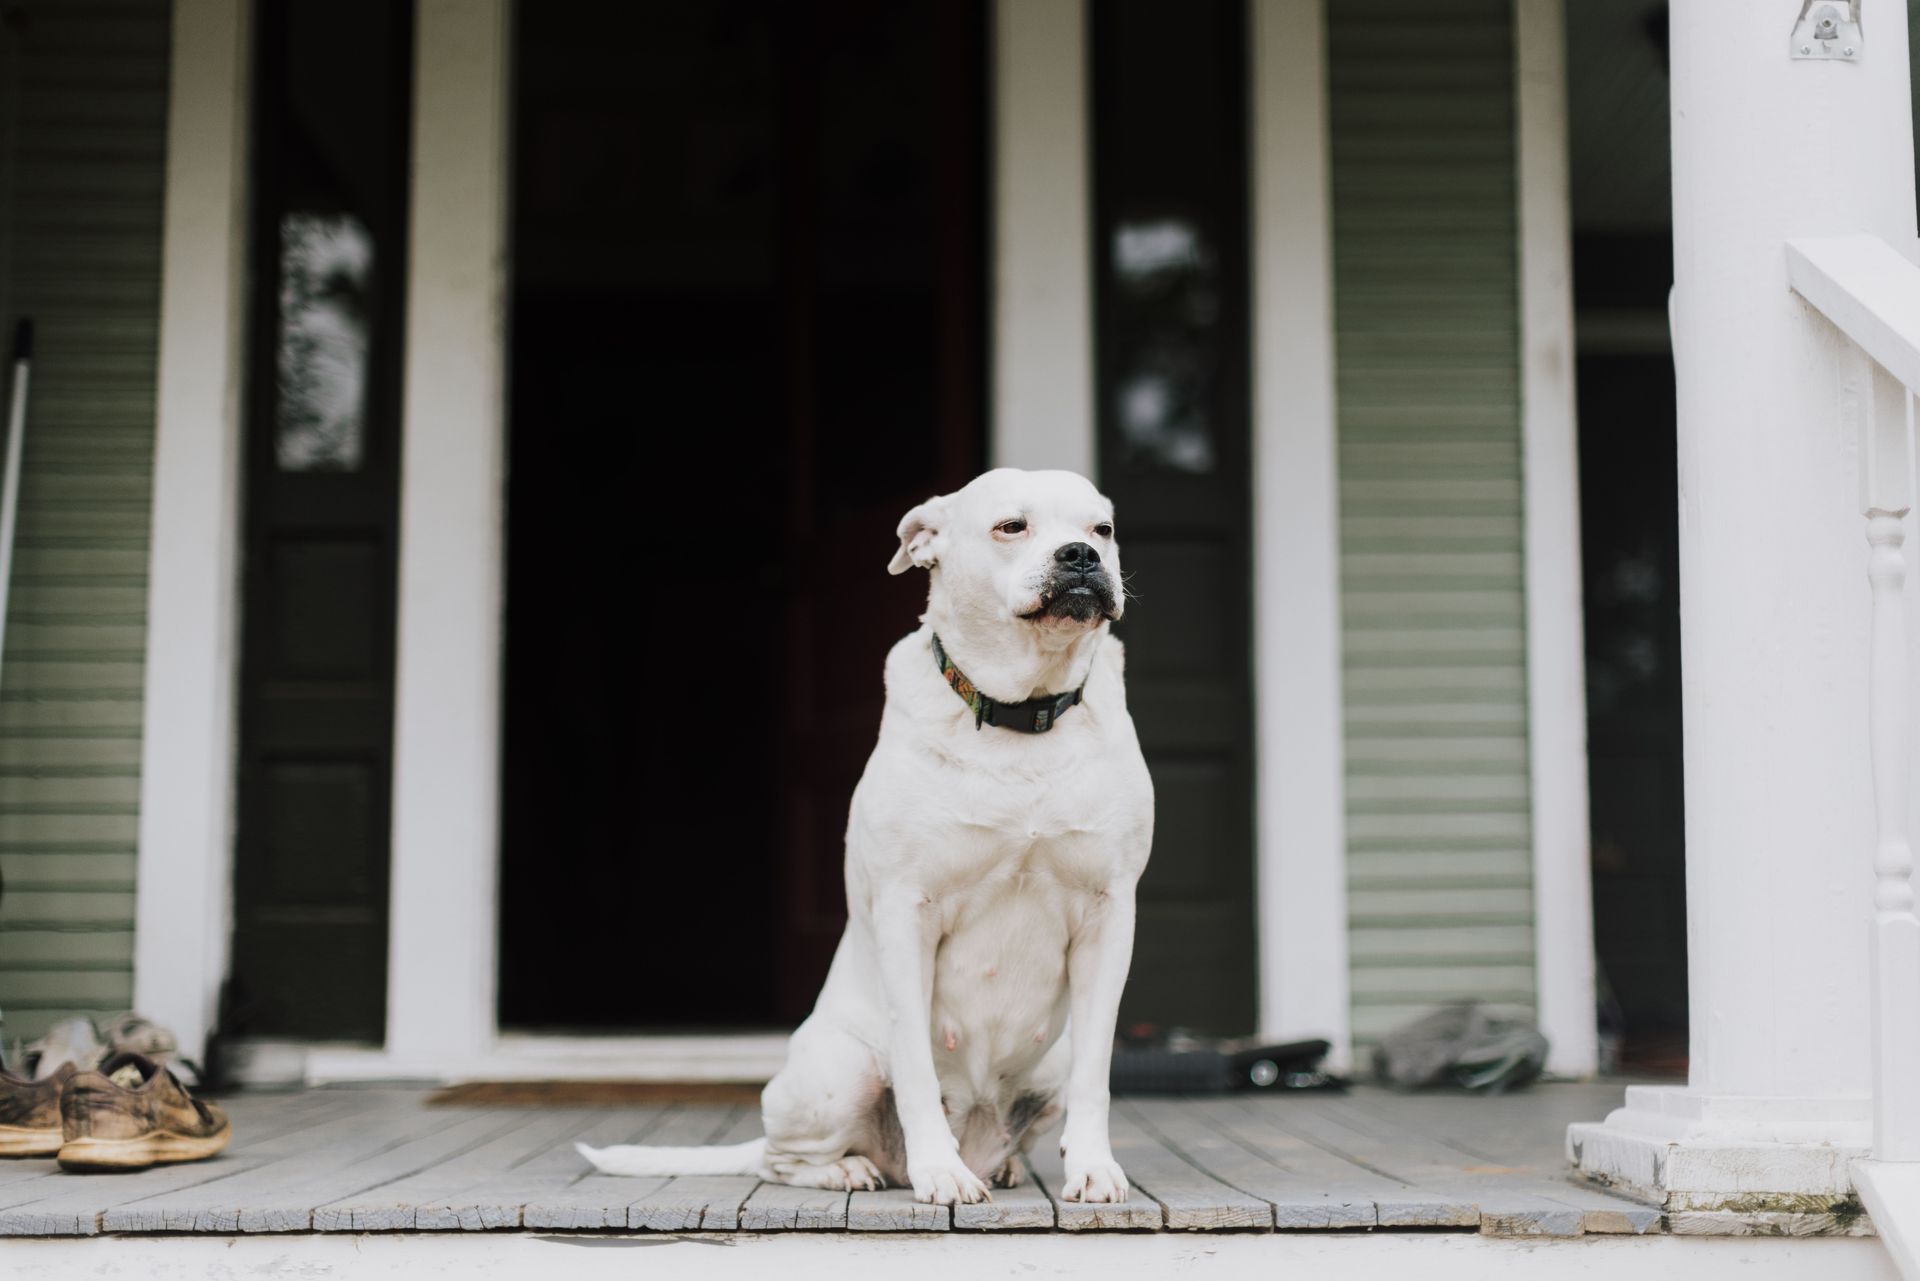
Dog bites are one of the most common homeowners liability claims in the country. Most policies cover them, but some carriers exclude certain breeds or dogs with a bite history. Tell your agent about your dog up front.
A child is hurt on your trampoline
Some policies cover trampoline injuries, some require a net and enclosure, and some exclude them. This is a good one to check before summer.
A contractor falls off a ladder
A contractor should carry their own workers' compensation and liability insurance. Before work starts, ask for a certificate of insurance. If they don't have coverage, the claim could land on your policy.
What Is Attractive Nuisance Law?
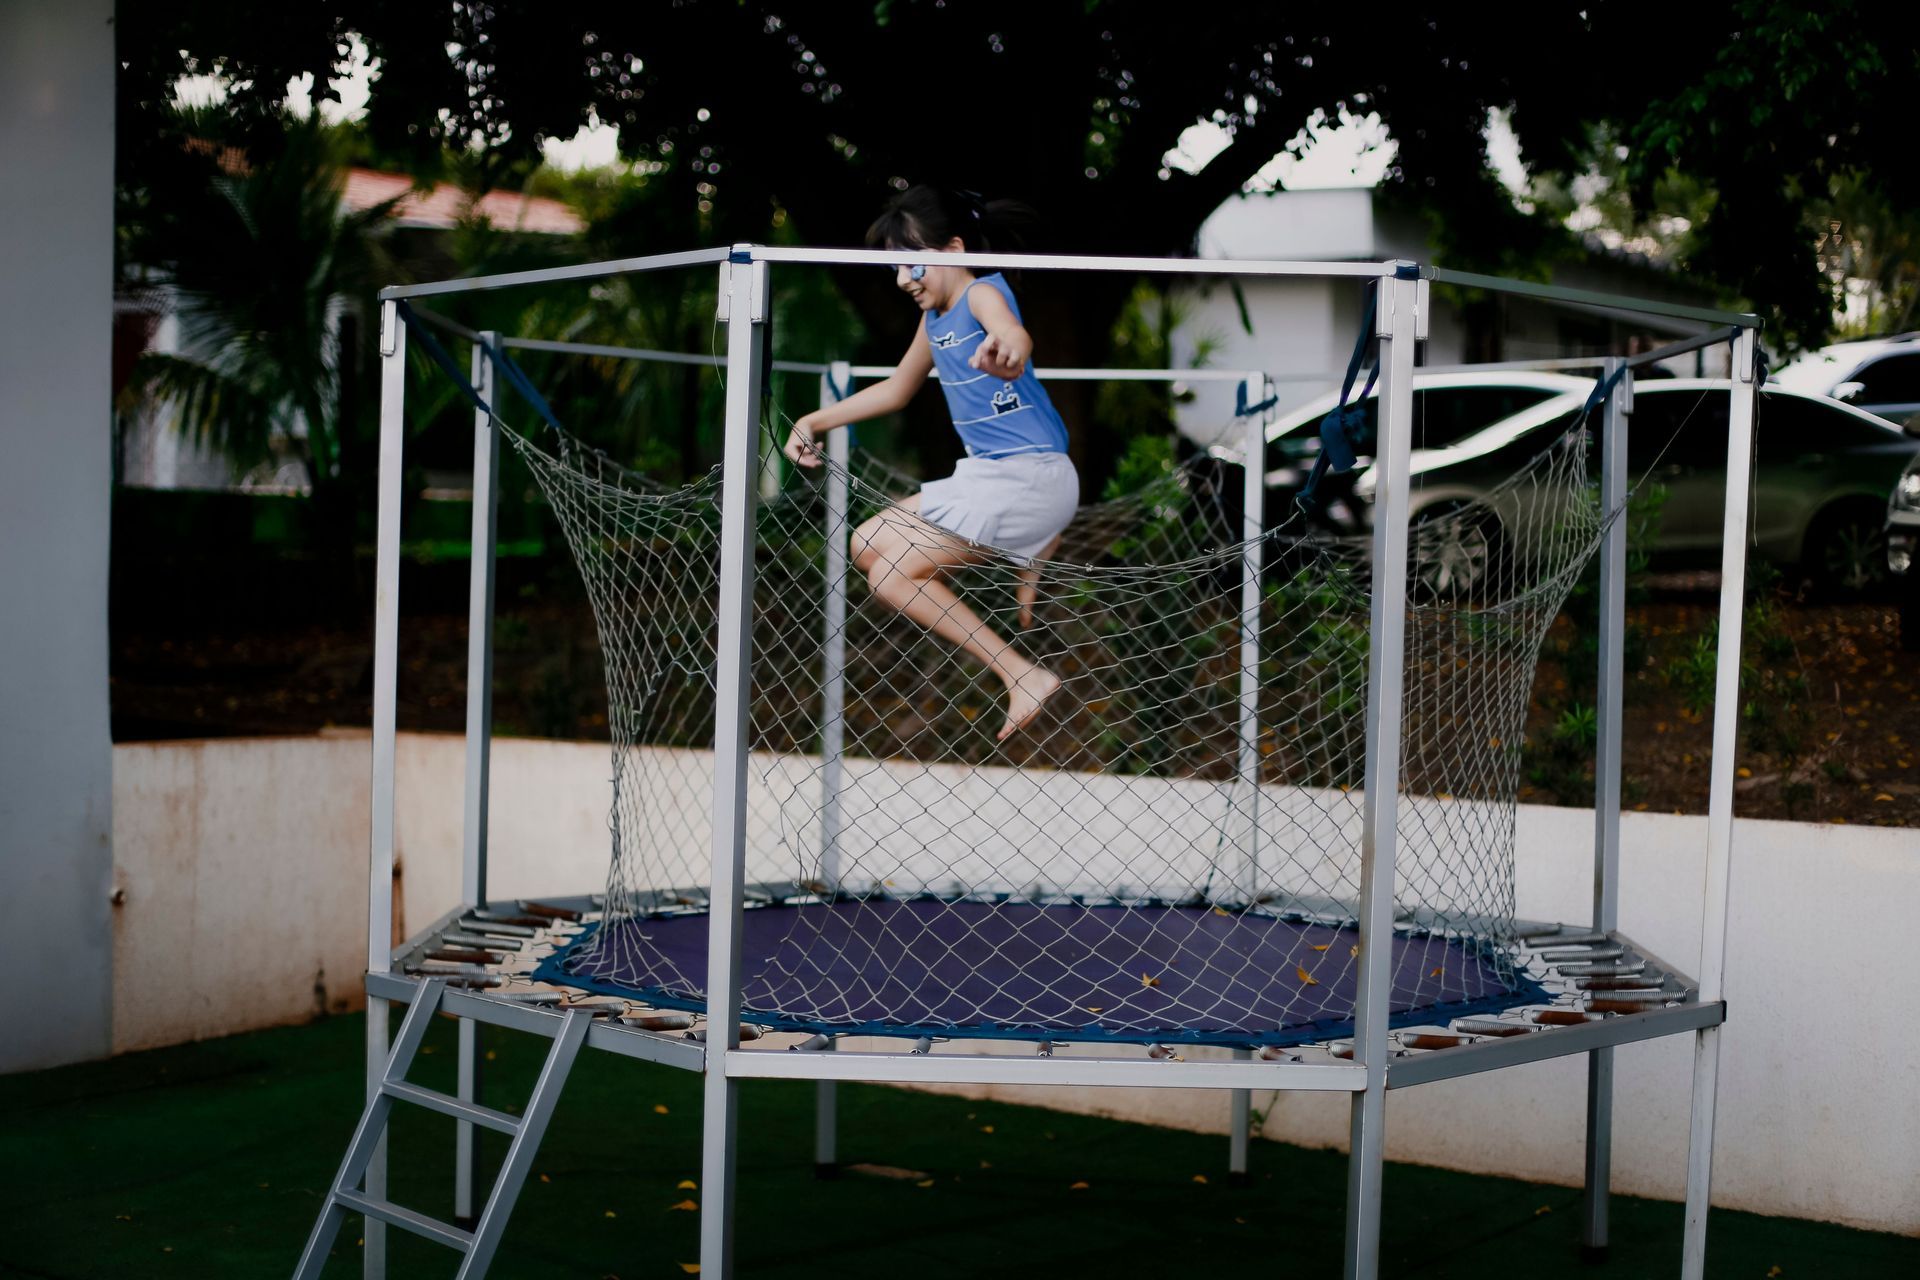
Attractive nuisance law protects curious kids. It applies when something on your property, like a pool, trampoline, or playset, draws a child in. This is true even if the child is trespassing. You can be held liable if the danger was easy to foresee and you could have reasonably prevented it.
Oklahoma recognizes this rule. Protecting your home is simple. Fence and lock your pool. Put a net on your trampoline and anchor it. Store ladders and tools out of reach.
Also tell your agent if you have a pool or trampoline. Some carriers ask about them, and leaving them off your application can put a claim at risk.
Is Your Homeowners Liability Limit High Enough?
A serious injury can cost far more than $100,000 once medical bills, lost wages, and legal fees add up. If a judgment goes over your limit, you could be on the hook for the rest.
For most families, we suggest at least $300,000 to $500,000 in personal liability on the home policy. Raising your limit usually costs very little.
Umbrella Insurance for Homeowners
Umbrella insurance for homeowners adds extra liability protection on top of your home and auto policies. It's usually sold in $1 million amounts. It kicks in after your other limits run out.
It's worth a look if you have a pool, trampoline, or dog, host often, own rental property, or have savings to protect. Coverage often costs a few hundred dollars a year. Get an umbrella insurance quote.
How Can You Keep Guests Safe at Home?
- Keep steps and walkways clear, and salt them in icy weather.
- Add lighting to entries, stairs, and paths.
- Repair loose railings, boards, and uneven pavers.
- Fence your pool and lock the gate.
- Keep pets secured around guests they don't know.
For more ideas, see our 10 home safety tips.
Frequently Asked Questions
Does homeowners insurance cover guest injuries?
Yes, in most cases. Liability coverage pays when you're legally at fault. Medical payments coverage pays small bills even when you're not.
What are the most common types of premises liability claims?
Slips and falls, trips, dog bites, pool and trampoline injuries, and falls from decks or railings.
Does homeowners liability cover injuries to my own family?
No. Liability coverage doesn't apply to people who live in your home. Their own health insurance usually pays.
Do I need umbrella insurance?
If a big lawsuit could top your home policy's limit, an umbrella is a cheap way to add $1 million or more.
Will a guest injury claim raise my premium?
Yes, it can. Insurers look at your claims history at renewal, and a liability claim counts like any other. That's one more reason to keep your home safe for visitors.
This article is general information, not legal advice. Talk to your insurer or an attorney about your situation.
Talk to an Edmond Insurance Agent
We're Miner Family Insurance, a local, independent agency right here in Edmond. We shop more than 50 carriers, and we never charge fees. We can review your liability limits and quote umbrella coverage. Call 405-724-2389 or request a home insurance quote online.