Oklahoma Homeowners Insurance for Winter Storms
By Josh Miner, a licensed agent and the founder of Miner Family Insurance in Edmond, OK. Updated October 2026.
Oklahoma winters are hard to predict. One week it's 60 degrees, and the next an ice storm snaps trees and knocks out power. Many metro families still remember the October 2020 ice storm. Others remember the February 2021 deep freeze that burst pipes across the state.
Here's what Oklahoma homeowners insurance usually covers after a winter storm. You'll also learn where the gaps are and how to protect your home before the next freeze.
What Does Homeowners Insurance Cover in a Winter Storm?
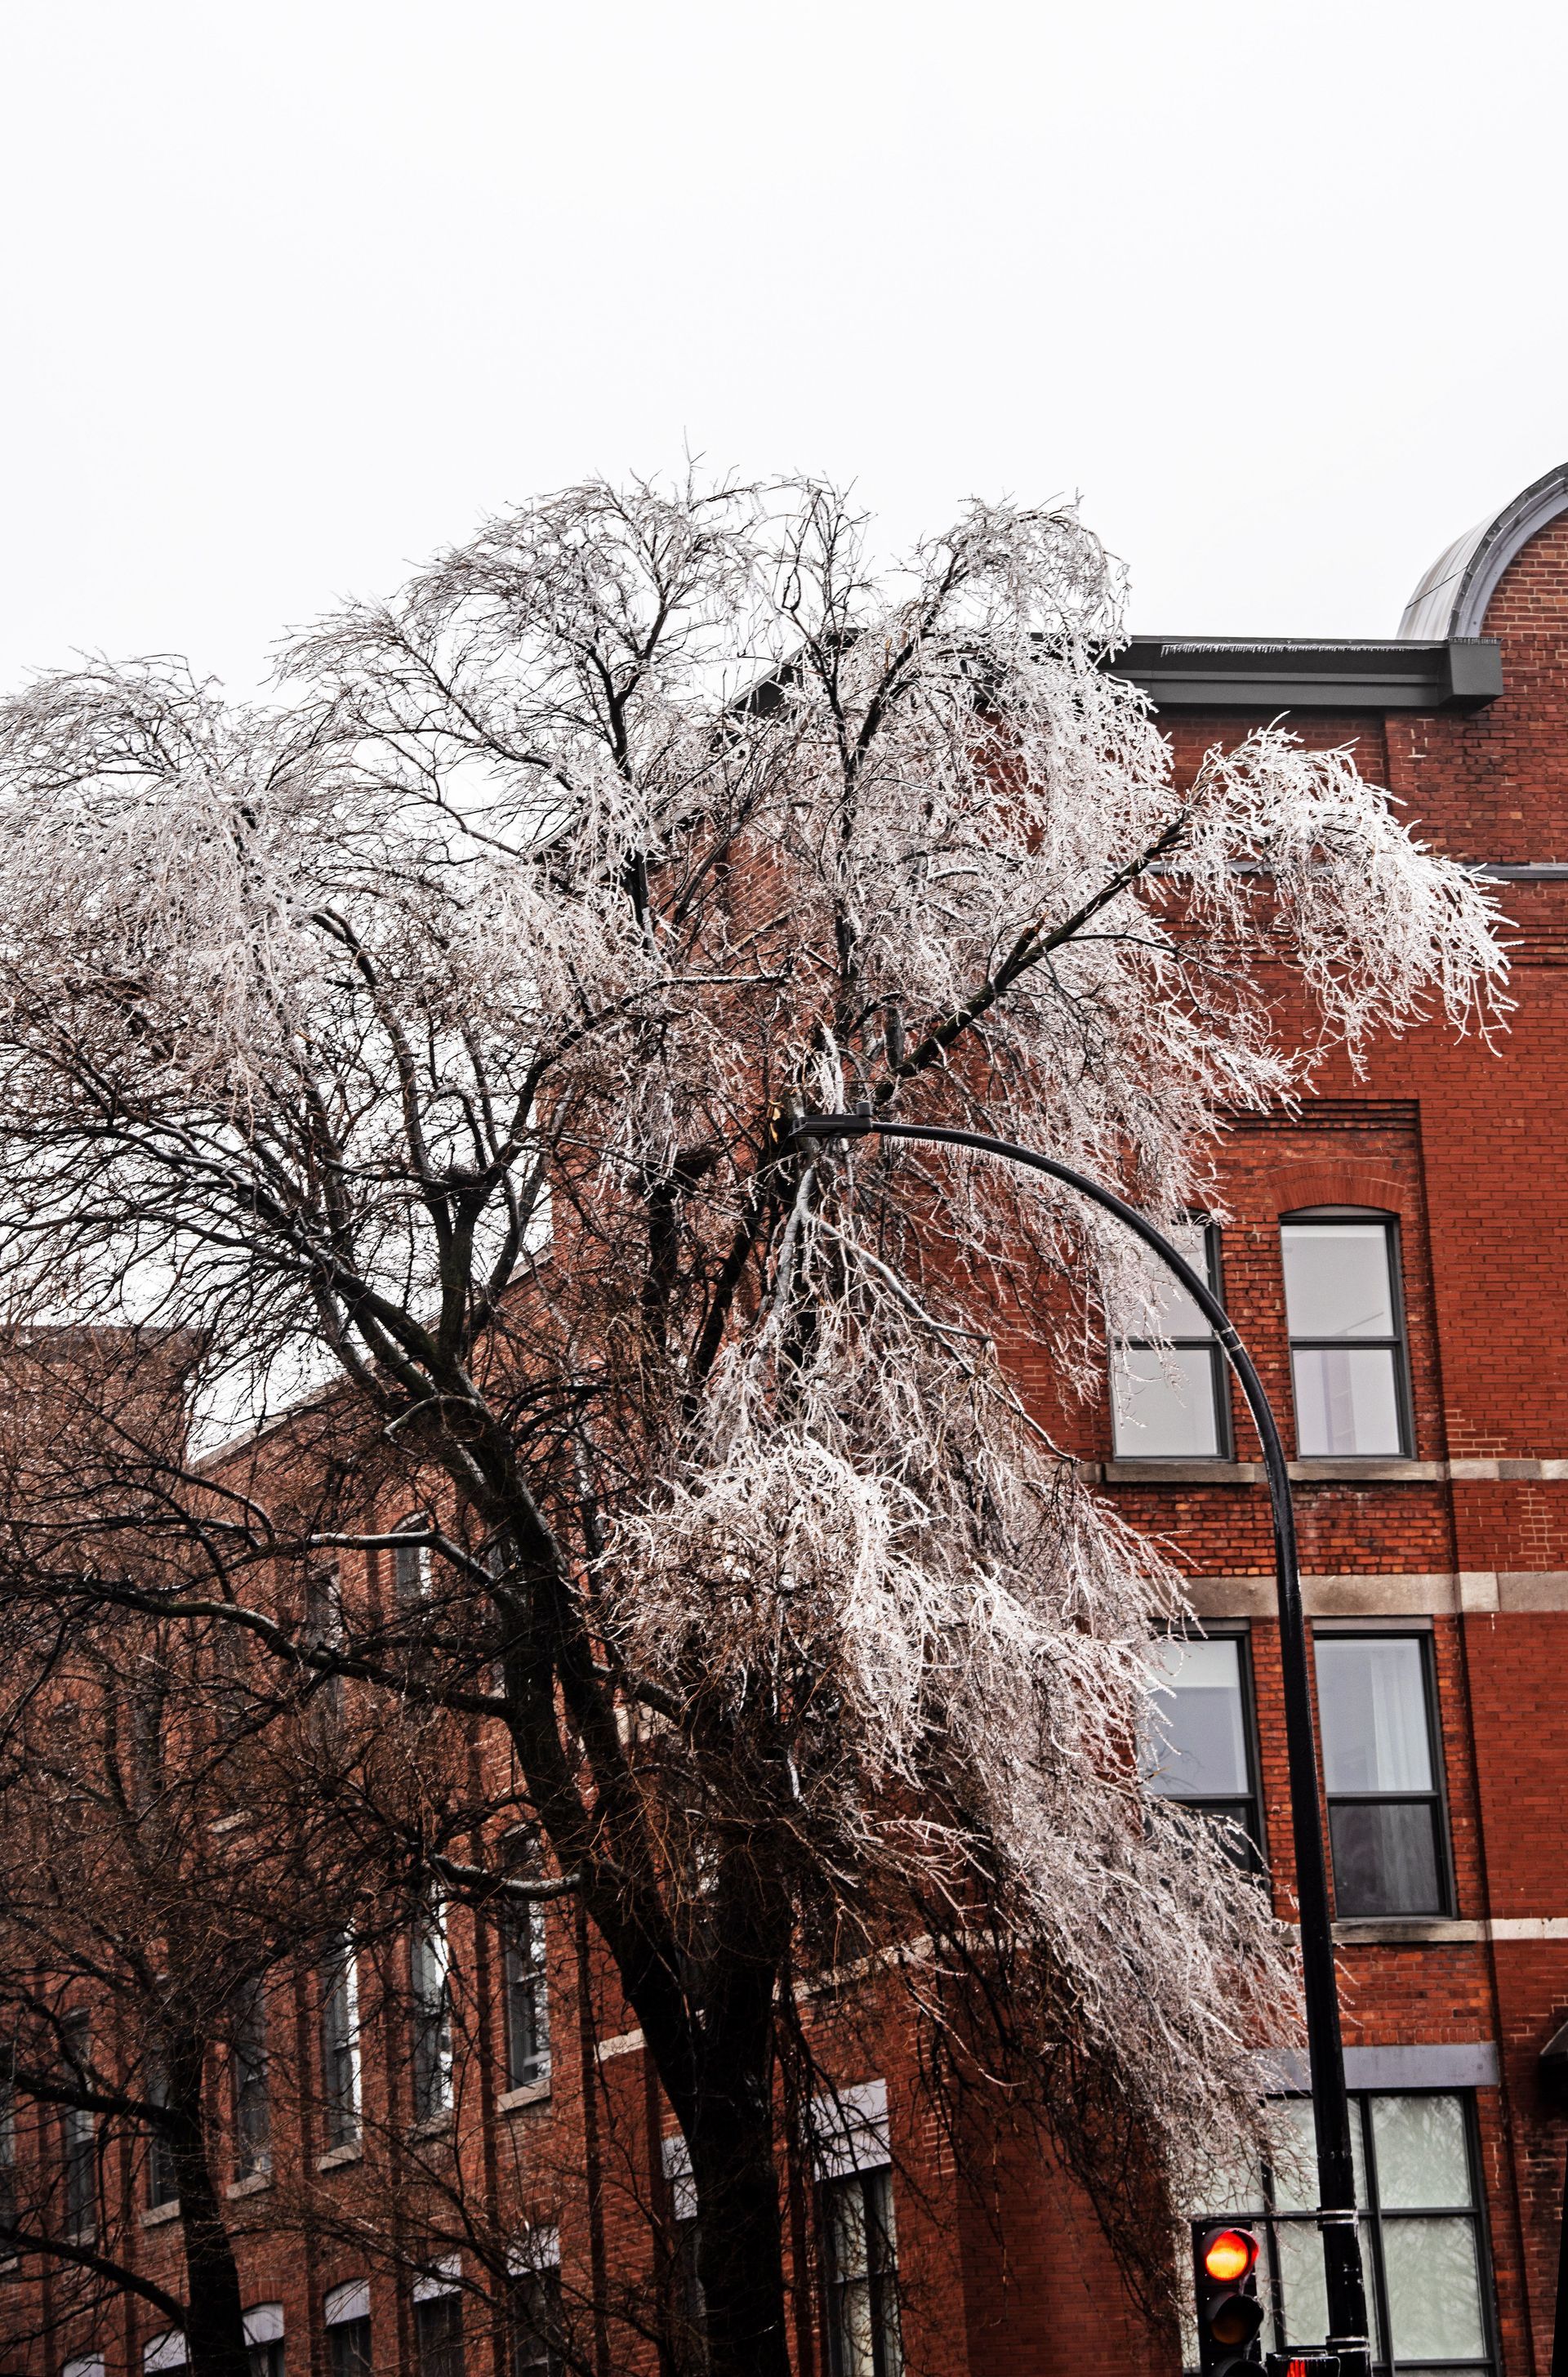
Most standard policies cover sudden damage from winter weather, including:
- Roof or structure damage from the weight of ice or snow
- Trees or limbs that fall on your home, garage, or fence
- Burst pipes, as long as you took reasonable steps to keep the home heated
- Wind damage from winter storms
- Fire from a space heater or fireplace accident
Some winter damage usually isn't covered. That includes damage from wear and tear or poor upkeep, and flooding from water that rises from outside. Damage to your car is handled by your auto policy, not your home policy.
Is There Insurance Coverage for Fallen Trees?
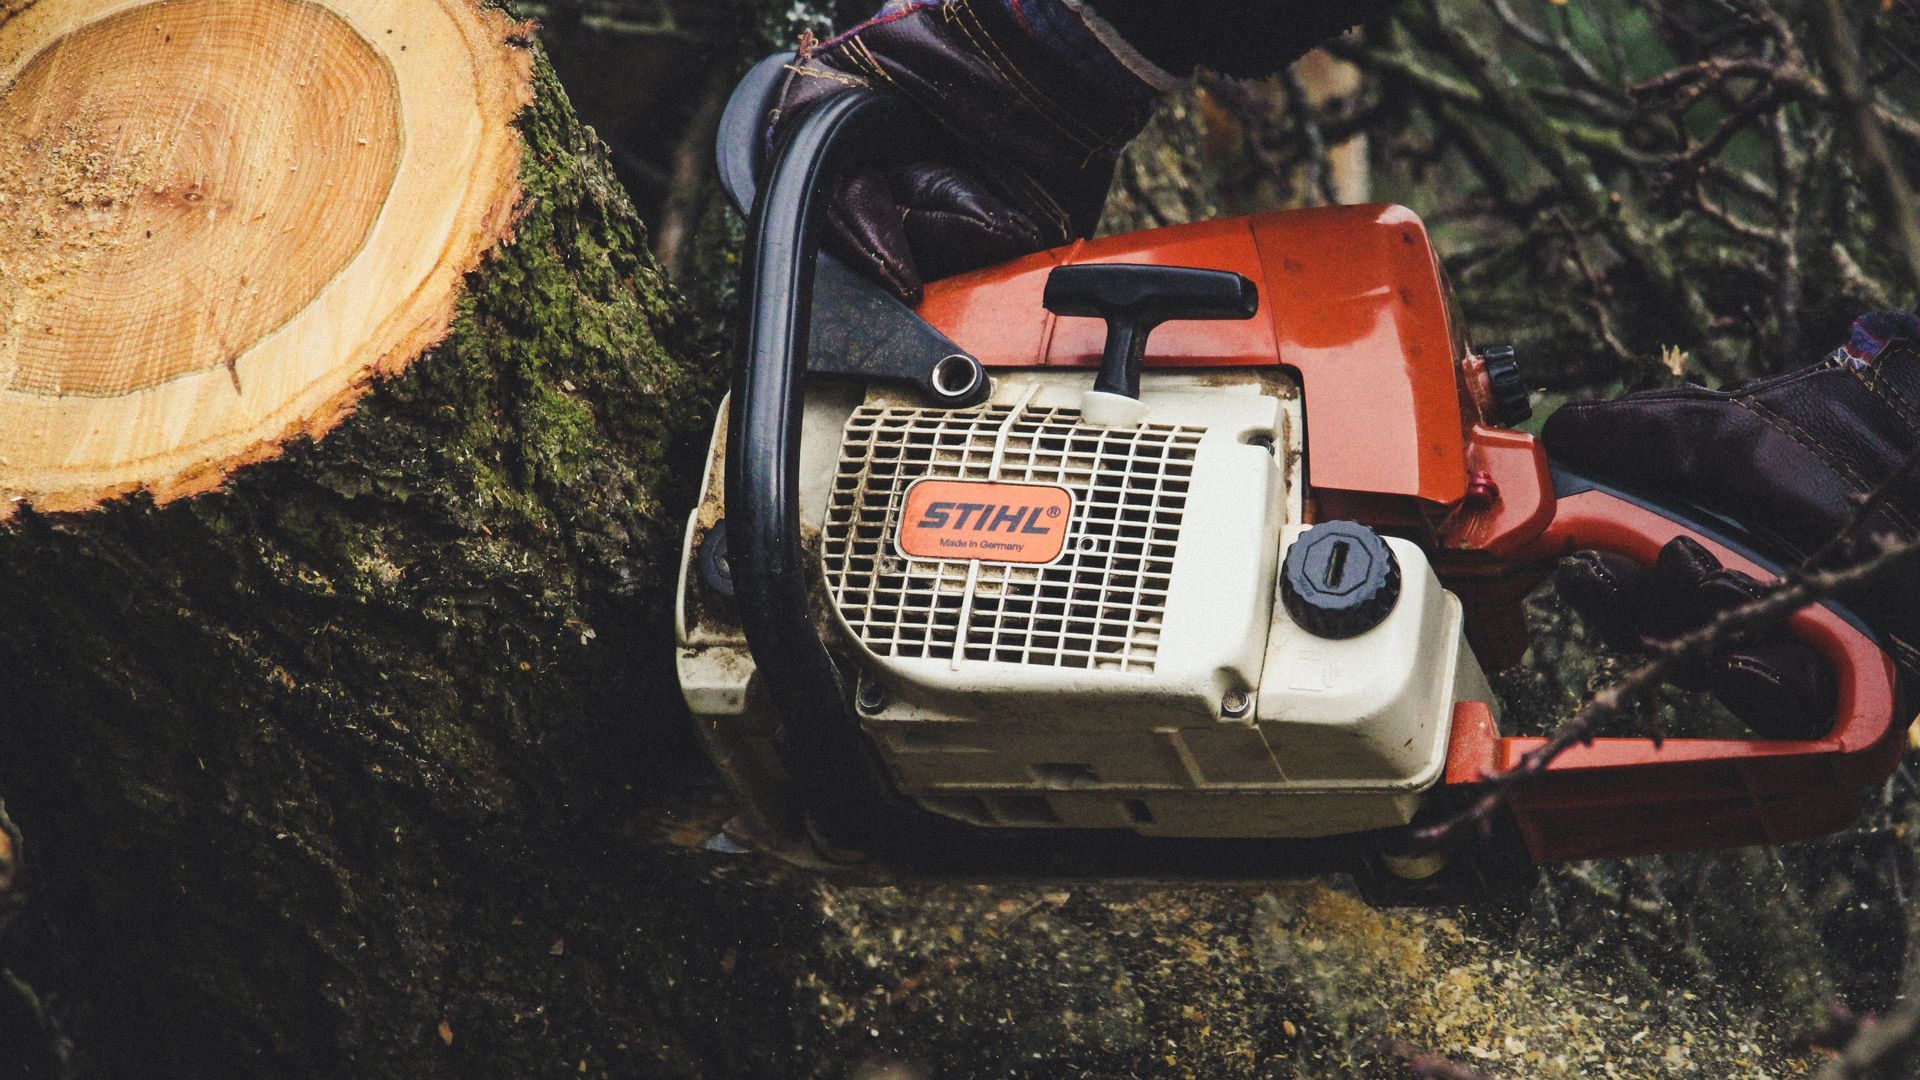
Ice storms are hard on Oklahoma trees. How your claim works depends on where the tree lands:
- It hits your home or another covered structure: Your policy usually pays to fix the damage and remove the tree.
- It blocks your driveway: Many policies pay for removal, up to a small limit.
- It falls in your yard without hitting anything: Removal usually isn't covered.
- It lands on your car: File the claim with your auto insurer under comprehensive coverage.
Many policies cap tree removal at about $500 per tree and $1,000 per storm. Check your policy so you know your limits.
What If Your Neighbor's Tree Falls on Your House?
Your own policy covers the damage to your home. Your neighbor is usually only responsible if the tree was clearly dead or diseased and they ignored it. Either way, start by calling your own insurer.
Does Homeowners Insurance Cover Roof Damage From Ice and Snow?
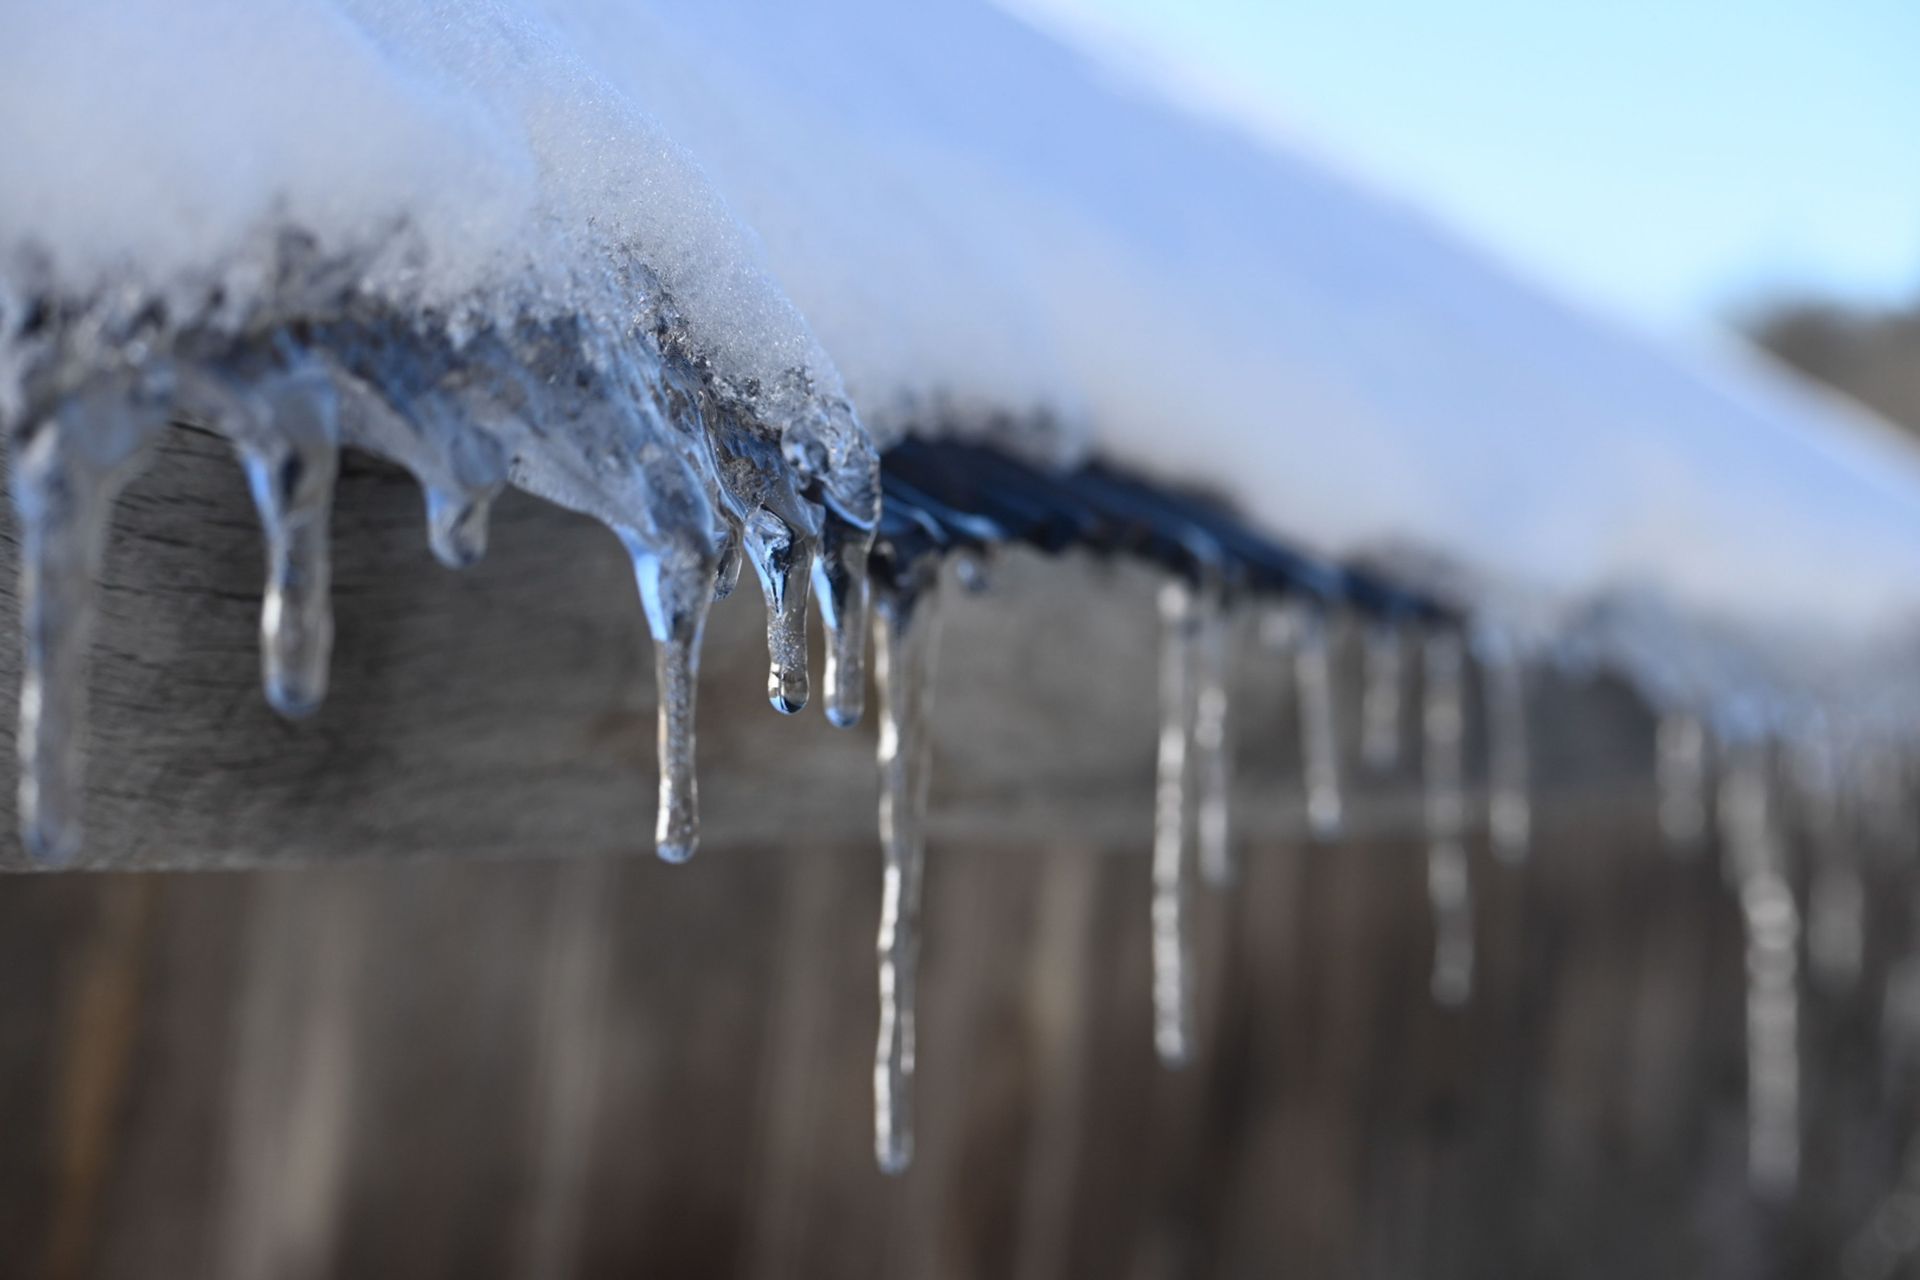
In most cases, yes. If heavy ice or snow damages your roof or causes part of it to collapse, that's usually a covered loss.
Leaks can be trickier. Water that gets in because of sudden storm damage is usually covered. A leak caused by worn-out shingles or a roof that wasn't maintained usually isn't.
Roof age matters too. Some Oklahoma policies pay less on older roofs. They might pay actual cash value or use a roof payment schedule. That means a smaller check, so know how your roof is covered before winter hits.
Are Fences, Sheds, and Detached Garages Covered?
In most cases, yes. Your policy has separate coverage for other structures on your property, like fences, sheds, and detached garages. It's often 10% of your dwelling coverage.
So if an ice-heavy limb crushes your backyard fence or shed, you can file a claim. Your deductible still applies, so small repairs may cost less to pay out of pocket.
Is There Insurance Coverage for Frozen Pipes?
Burst pipes are one of the most common winter claims in Oklahoma. Most policies cover sudden water damage when a pipe freezes and bursts.
There's a catch. You need to have kept the heat on, or shut off and drained the water if the home was empty. If a house sits unheated and the pipes freeze, the claim can be denied.
These steps help prevent frozen pipes:
- Keep the thermostat at 55°F or higher, even when you travel.
- Let faucets on outside walls drip during hard freezes.
- Open cabinet doors under sinks so warm air reaches the pipes.
- Disconnect garden hoses and cover outdoor spigots.
- Learn where your main water shutoff is.
For more ideas, see our home safety tips.
How Does Loss of Use Coverage Work?
Storm damage can make your home unlivable. When it does, loss of use coverage in your homeowners insurance pays the extra costs while repairs are made.
- A hotel or short-term rental
- Higher food costs if you can't cook at home
- Laundry and extra mileage
It pays the difference between your normal costs and your higher ones. Keep every receipt. A power outage on its own usually doesn't qualify. Your home needs covered damage that makes it unsafe to live in.
How Much Loss of Use Coverage Homeowners Insurance Policies Include
Most policies include it. You may see it called Coverage D or additional living expenses.
The limit is often 20% to 30% of your dwelling coverage. Some policies set a time limit instead, like 12 or 24 months. Check your declarations page to see which one you have.
What About Power Outages and Spoiled Food?
Most policies don't cover an outage that starts away from your home, like a downed power line. Some policies include, or let you add, food spoilage coverage for a few hundred dollars.
If you run a generator, keep it outside and well away from doors and windows. Make sure your carbon monoxide detectors work.
What Winter Damage Isn't Covered?
Knowing the gaps helps you plan ahead. These are the most common winter claims that get denied or limited:
- Neglect: Pipes that freeze in an empty, unheated home.
- Wear and tear: Old roofs, rotted wood, or gutters that were already failing.
- Outside flooding: Melting snow or heavy rain that rises into your home needs flood insurance.
- Off-site power outages: Spoiled food and lost income aren't covered unless you added coverage.
- Tree removal only: Trees that fall in the yard without hitting anything.
How Do You File a Winter Storm Claim?
- Put safety first. Keep away from downed power lines and damaged trees.
- Take photos of everything. Record the damage before you move anything.
- Stop more damage. Shut off the water if a pipe bursts, and tarp any roof openings. Save your receipts.
- Call your agent or insurer. Report the claim as soon as you can, since big storms bring a flood of calls.
- Meet the adjuster. Walk them through all the damage and ask for a copy of the estimate.
For a full walkthrough, see our guide on how to file a homeowners insurance claim after a disaster.
How Can You Get Your Home Ready for Winter?
- Clean your gutters so melting ice can drain.
- Trim limbs that hang over your roof.
- Service your furnace and have your chimney checked.
- Test your smoke and carbon monoxide detectors.
- Insulate pipes in the attic, garage, and crawl space.
- Build an emergency kit with flashlights, blankets, water, and phone chargers.
- Take photos of your home and belongings in case you need to file a claim.
Is Your Edmond Homeowners Insurance Ready for Winter?
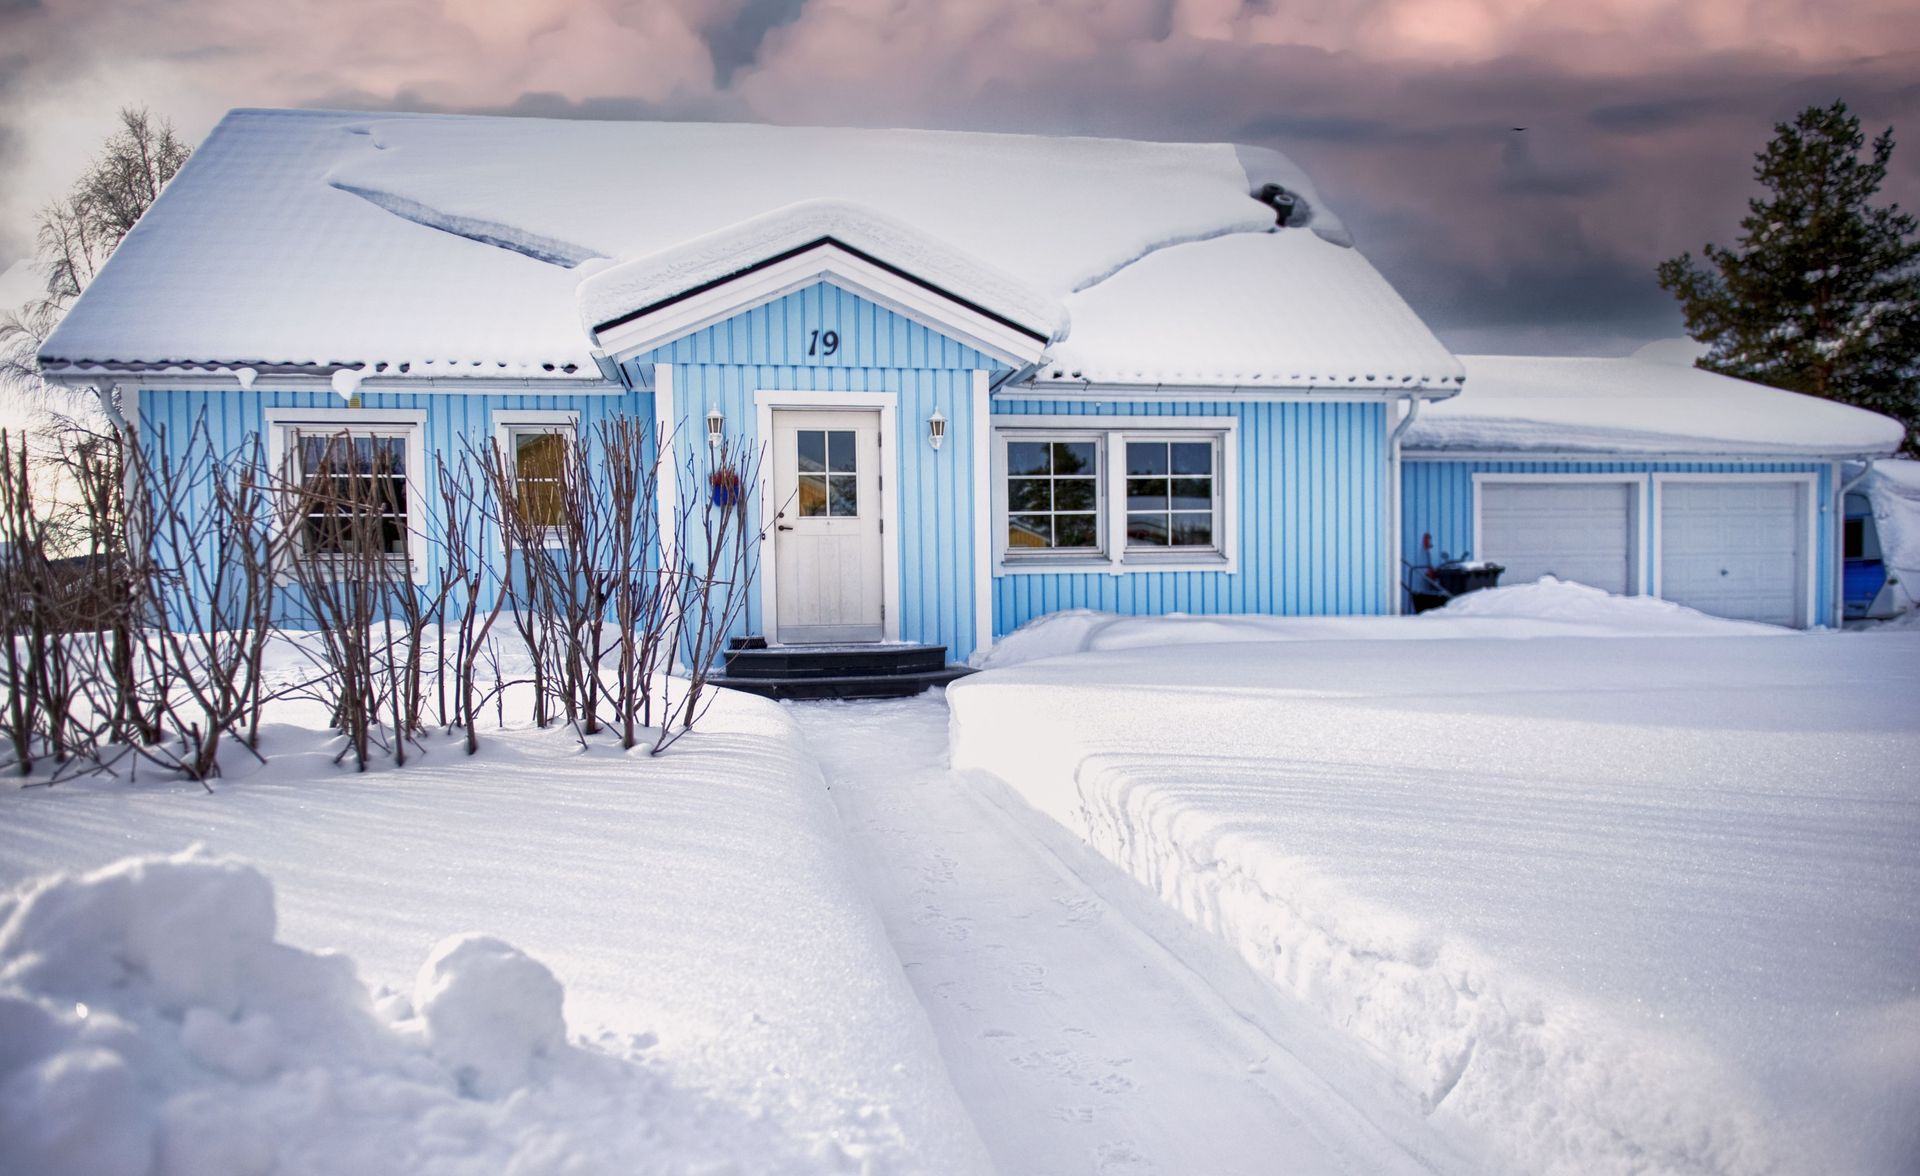
Edmond has plenty of mature trees and older neighborhoods, so winter is a good time to review your policy. Check these items:
- Tree removal limits: Know how much your policy pays to haul away fallen trees.
- Deductibles: Your wind and hail deductible may apply to winter windstorms too.
- Food spoilage: See whether you have it and how much it pays.
- Water backup: This optional coverage helps if a sump pump or drain backs up.
- Loss of use limit: Make sure it's high enough for a few months in a rental.
Frequently Asked Questions
Does homeowners insurance cover ice damage?
In most cases, yes. Damage from the weight of ice or snow, and from trees that fall on your home, is typically covered.
Is there insurance coverage for fallen trees that don't hit anything?
No, not in most cases. Insurers pay for removal when the tree hits a covered structure. Some also pay when it blocks your driveway.
Is there insurance coverage for frozen pipes?
Yes, in most cases, as long as you kept the home heated or drained the water. Unheated, empty homes can be denied.
Does loss of use cover a hotel during a power outage?
Usually not. Loss of use applies when covered damage makes your home unlivable, not for an outage alone.
Who pays if a tree falls on my car?
Your auto insurance does, if you have comprehensive coverage. Your homeowners policy doesn't cover vehicles.
Talk to an Edmond Insurance Agent
We're Miner Family Insurance, a local, independent agency right here in Edmond. We compare Oklahoma homeowners insurance from more than 50 carriers, and we never charge fees. Call 405-724-2389 or request a home insurance quote online.