Replacement Cost vs Actual Cash Value in Oklahoma
Written by Joshua Miner, local independent insurance agent at Miner Family Insurance in Edmond, OK.
Two homes can have the same coverage limit and still get very different checks after the same hailstorm. The reason is often one line in the policy: replacement cost or actual cash value.
Here's what each one means, how roof depreciation plays a role, and which option makes sense for most Oklahoma homeowners.
What Is the Difference Between Replacement Cost vs Actual Cash Value?
The difference between replacement cost vs actual cash value comes down to depreciation. That's the value something loses as it ages.
- Replacement cost: Pays what it costs to repair or replace the item with a new one of similar quality, with no deduction for age.
- Actual cash value: Pays what the item was worth at the time of the loss. That's the replacement cost minus depreciation.
Replacement cost costs a bit more up front. But it usually pays far more after a claim.
How Does Actual Cash Value Work?
Actual cash value starts with the cost to replace an item and then subtracts depreciation. The older the item, the less you get.
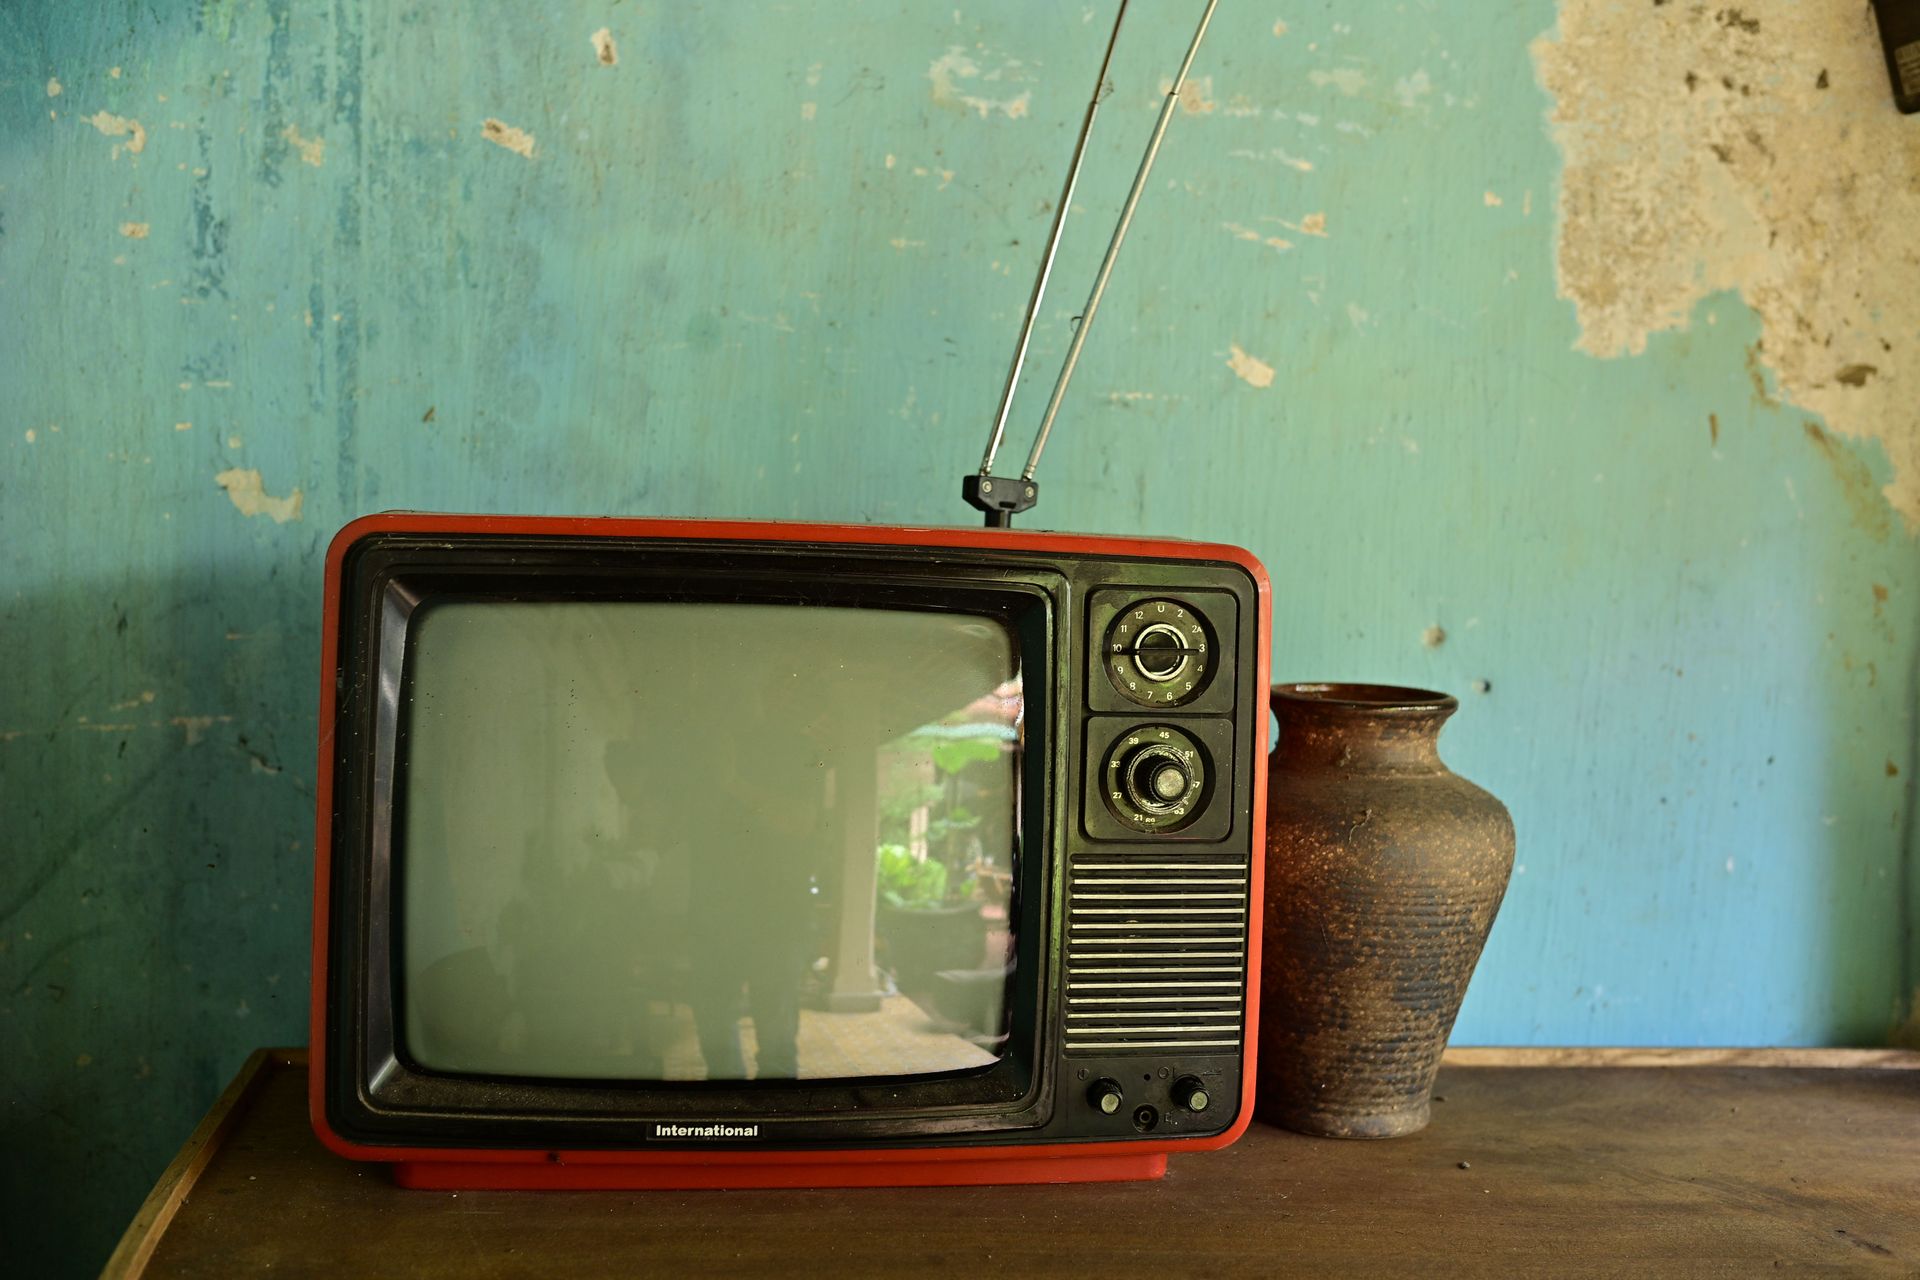
For example, say a storm ruins a 10-year-old TV. A new one costs $1,000. If the TV lost 70% of its value, an actual cash value policy might pay just $300. Then your deductible comes out.
How Does Replacement Cost Homeowners Insurance Work?
Replacement cost homeowners insurance pays to replace damaged items with new ones of like kind and quality. In the TV example, you'd get closer to $1,000, minus your deductible.
Many replacement cost policies pay in two steps. First, you get the actual cash value. Then, once you replace the item, you get the rest. Keep your receipts so you can claim the full amount.
What Is Roof Depreciation?
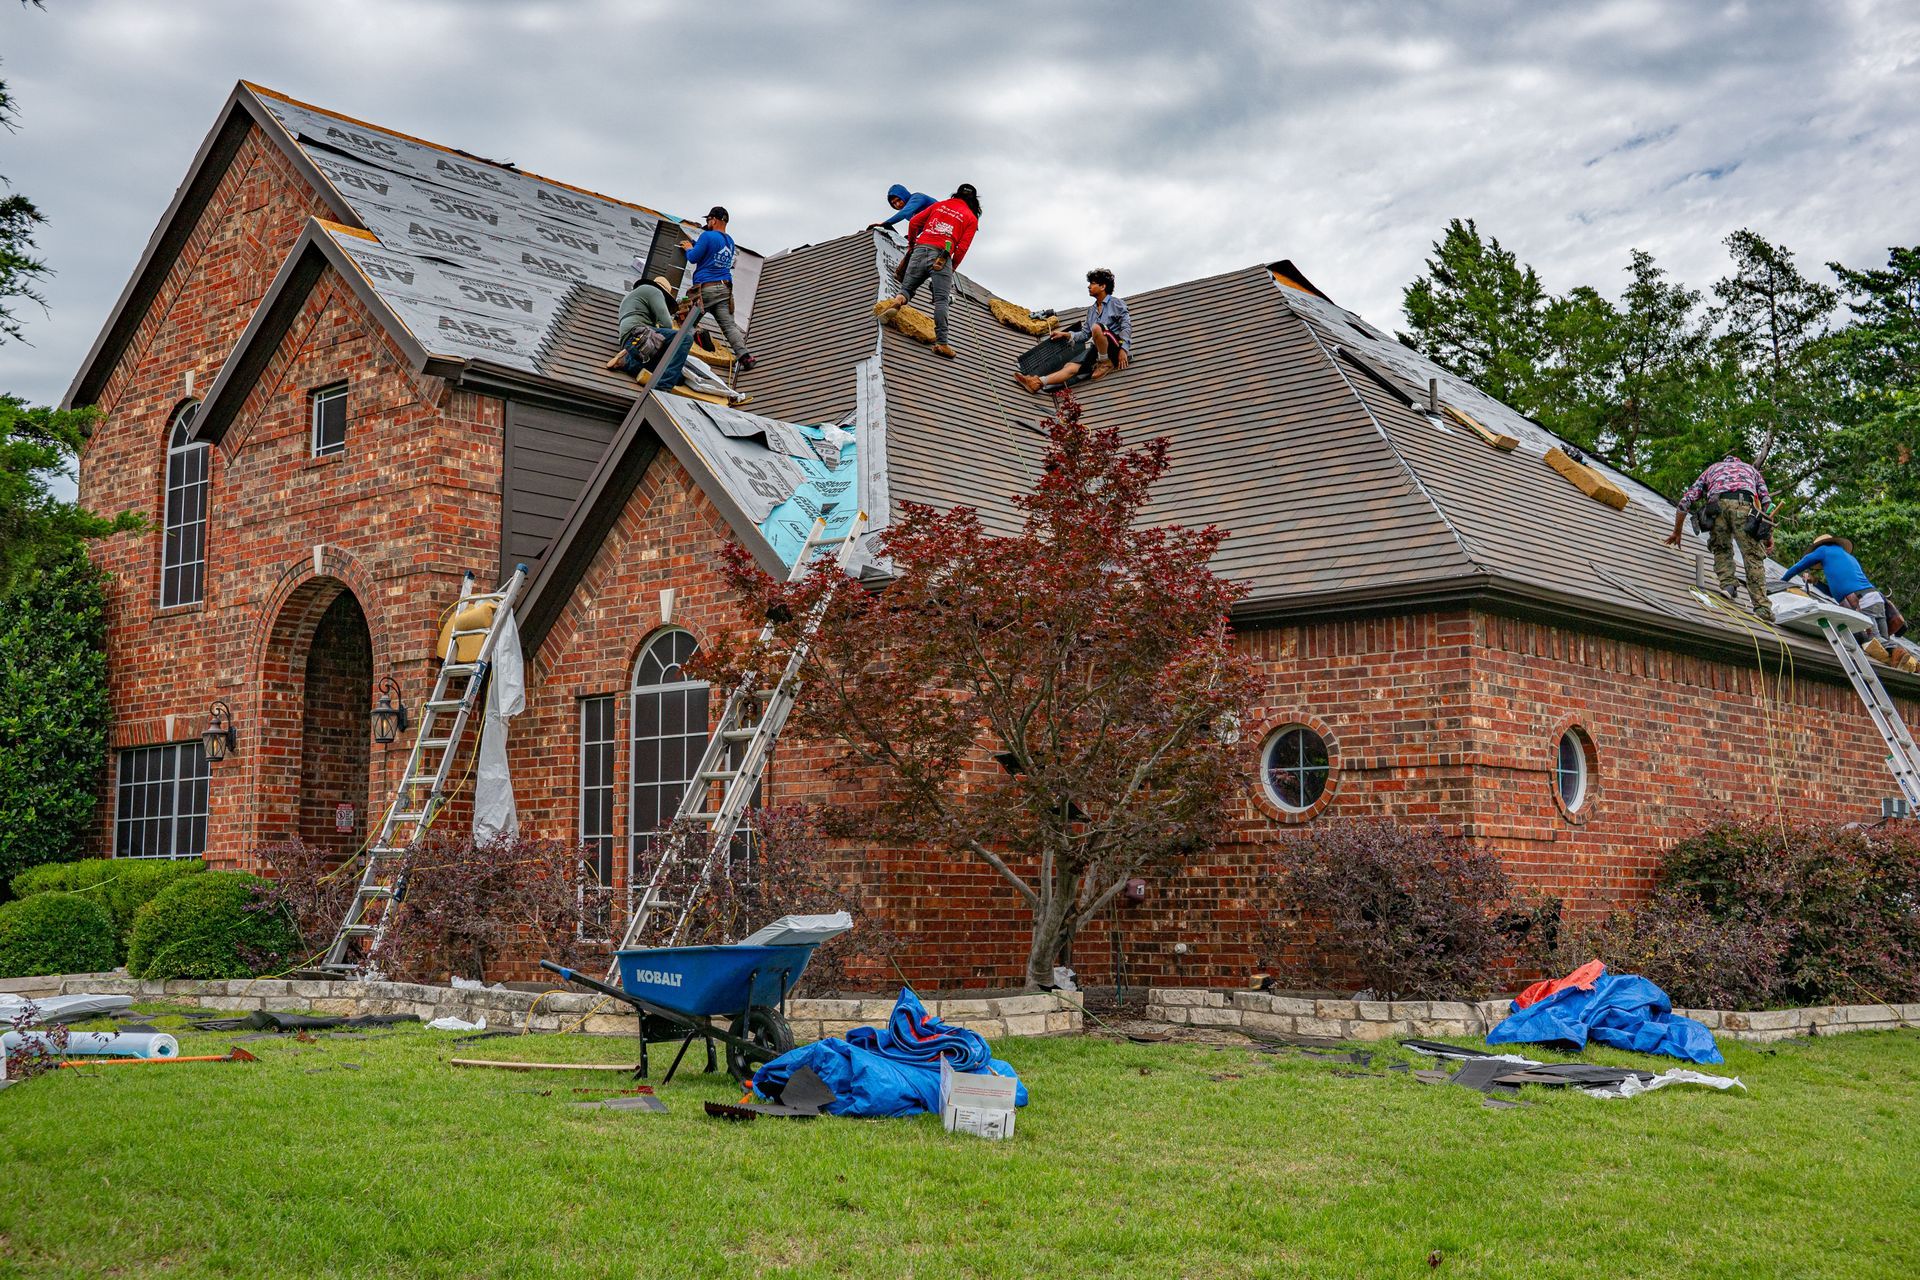
Roof depreciation is the drop in your roof's value as it ages. It matters a lot in Oklahoma, where hail damage to roofs is common.
A lot of carriers now pay older roofs at actual cash value, even if the rest of your policy is replacement cost. Some use a roof payment schedule that pays a smaller percentage each year the roof ages.
What does that mean for a $20,000 roof claim? Here's how it can look:
- Replacement cost: Pays about $20,000, minus your deductible.
- Actual cash value on a 15-year-old roof: Might pay $8,000 or less, minus your deductible.
That gap is why it's so important to know how your policy pays for your roof.
Which Is Better for Oklahoma Homeowners?
For most homeowners, replacement cost is the better choice. Oklahoma sees frequent hail, wind, and tornadoes, so the odds of a claim are higher. When a claim happens, replacement cost gives you enough money to actually rebuild and replace.
Actual cash value can make sense in a few cases:
- You need the lowest possible premium
- The home or roof is older and hard to insure
- You plan to sell soon and accept the risk
How Do You Know What Your Policy Has?
Check your declarations page or ask your agent. Look for these items:
- How your dwelling is paid: replacement cost or actual cash value
- How your personal property is paid
- Any roof payment schedule or roof age limits
- Your wind and hail deductible
Frequently Asked Questions
Is replacement cost worth the extra premium?
For most Oklahoma homeowners, yes. The extra cost is usually small compared to what you'd lose with depreciation after a big claim.
Does actual cash value cover my full roof?
Often, no. It subtracts roof depreciation, so older roofs get much smaller payouts.
Can I switch from actual cash value to replacement cost?
Yes, you often can. A newer roof can make it easier to qualify.
Does replacement cost apply to my belongings?
Only if your policy has replacement cost for your stuff, too. Some policies pay belongings at actual cash value unless you add it.
Compare Your Options With a Local Agent
We're Miner Family Insurance, a local, independent agency in Edmond. We'll explain how your policy pays claims and compare more than 50 carriers. Call (405) 724-2389 or request a home insurance quote online.