Why Home Insurance Rates Vary by Location in Oklahoma
Written by Joshua Miner, local independent insurance agent at Miner Family Insurance in Edmond, OK.
Two identical homes can have very different insurance prices just because of where they sit. Your ZIP code, your distance to a fire station, and even your street can change what you pay. Here's why home insurance rates vary by location, and what it means for Oklahoma homeowners.
Why Do Home Insurance Rates Vary by Location?
Insurance companies set prices based on risk. Some places are more likely to have claims than others. The more claims an area has, the higher the rates tend to be.
Location affects your rate through:
- Weather risk, like hail, wind, tornadoes, and winter storms
- Fire protection, including how close you are to a fire station and hydrant
- Crime rates, like theft and vandalism
- Local building costs and labor prices
- Flood risk and nearby water
- Claims history in your area
How Much Do Home Insurance Rates by ZIP Code Change?
Home insurance rates by ZIP code can vary quite a bit, even within the same metro. A home in one part of the OKC area may cost more to insure than a similar home a few miles away.
That's because carriers track losses down to small areas. If one neighborhood had many hail claims, rates there may go up more than in nearby areas.
Why Are Oklahoma Home Insurance Rates So High?
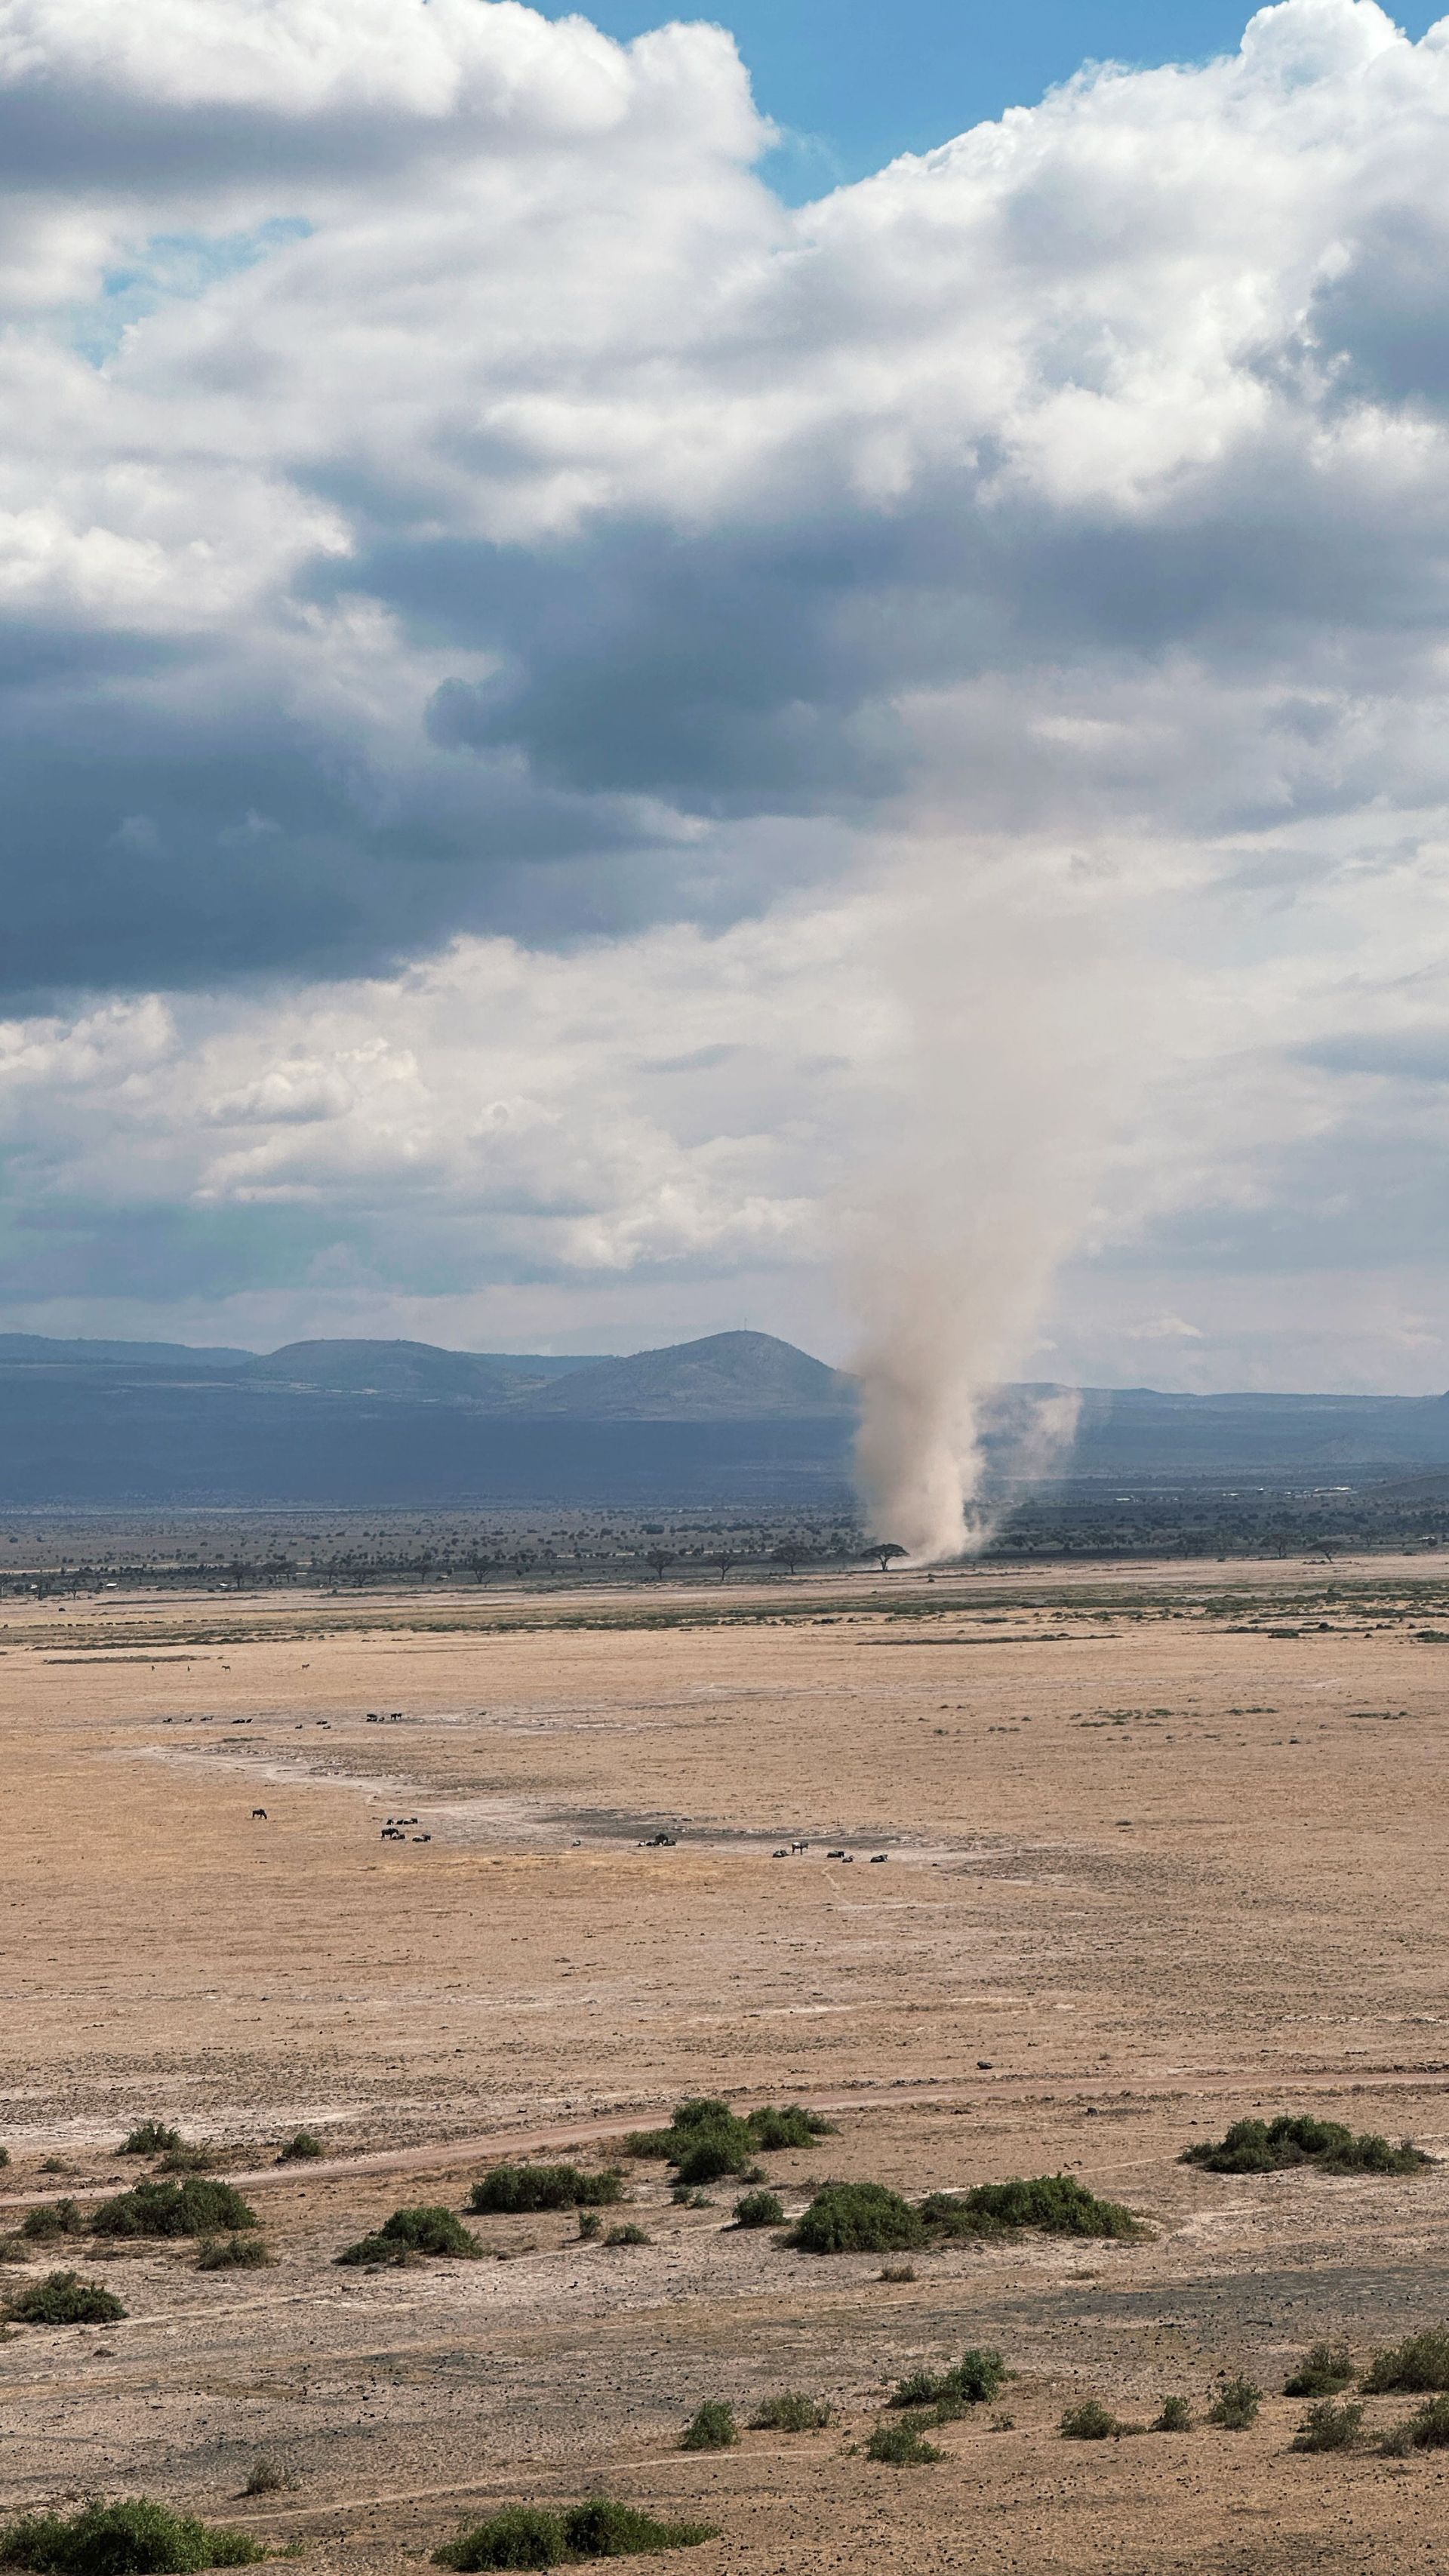
Oklahoma home insurance rates are some of the highest in the country. The main reason is the weather. Oklahoma sits in Tornado Alley and sees frequent large hail and strong straight-line winds.
Other factors include:
- Rising costs for roofing, lumber, and labor
- Many roof claims after hailstorms
- Higher reinsurance costs for carriers
- Severe winter storms that cause frozen pipes and ice damage
What Is a Fire Protection Class?
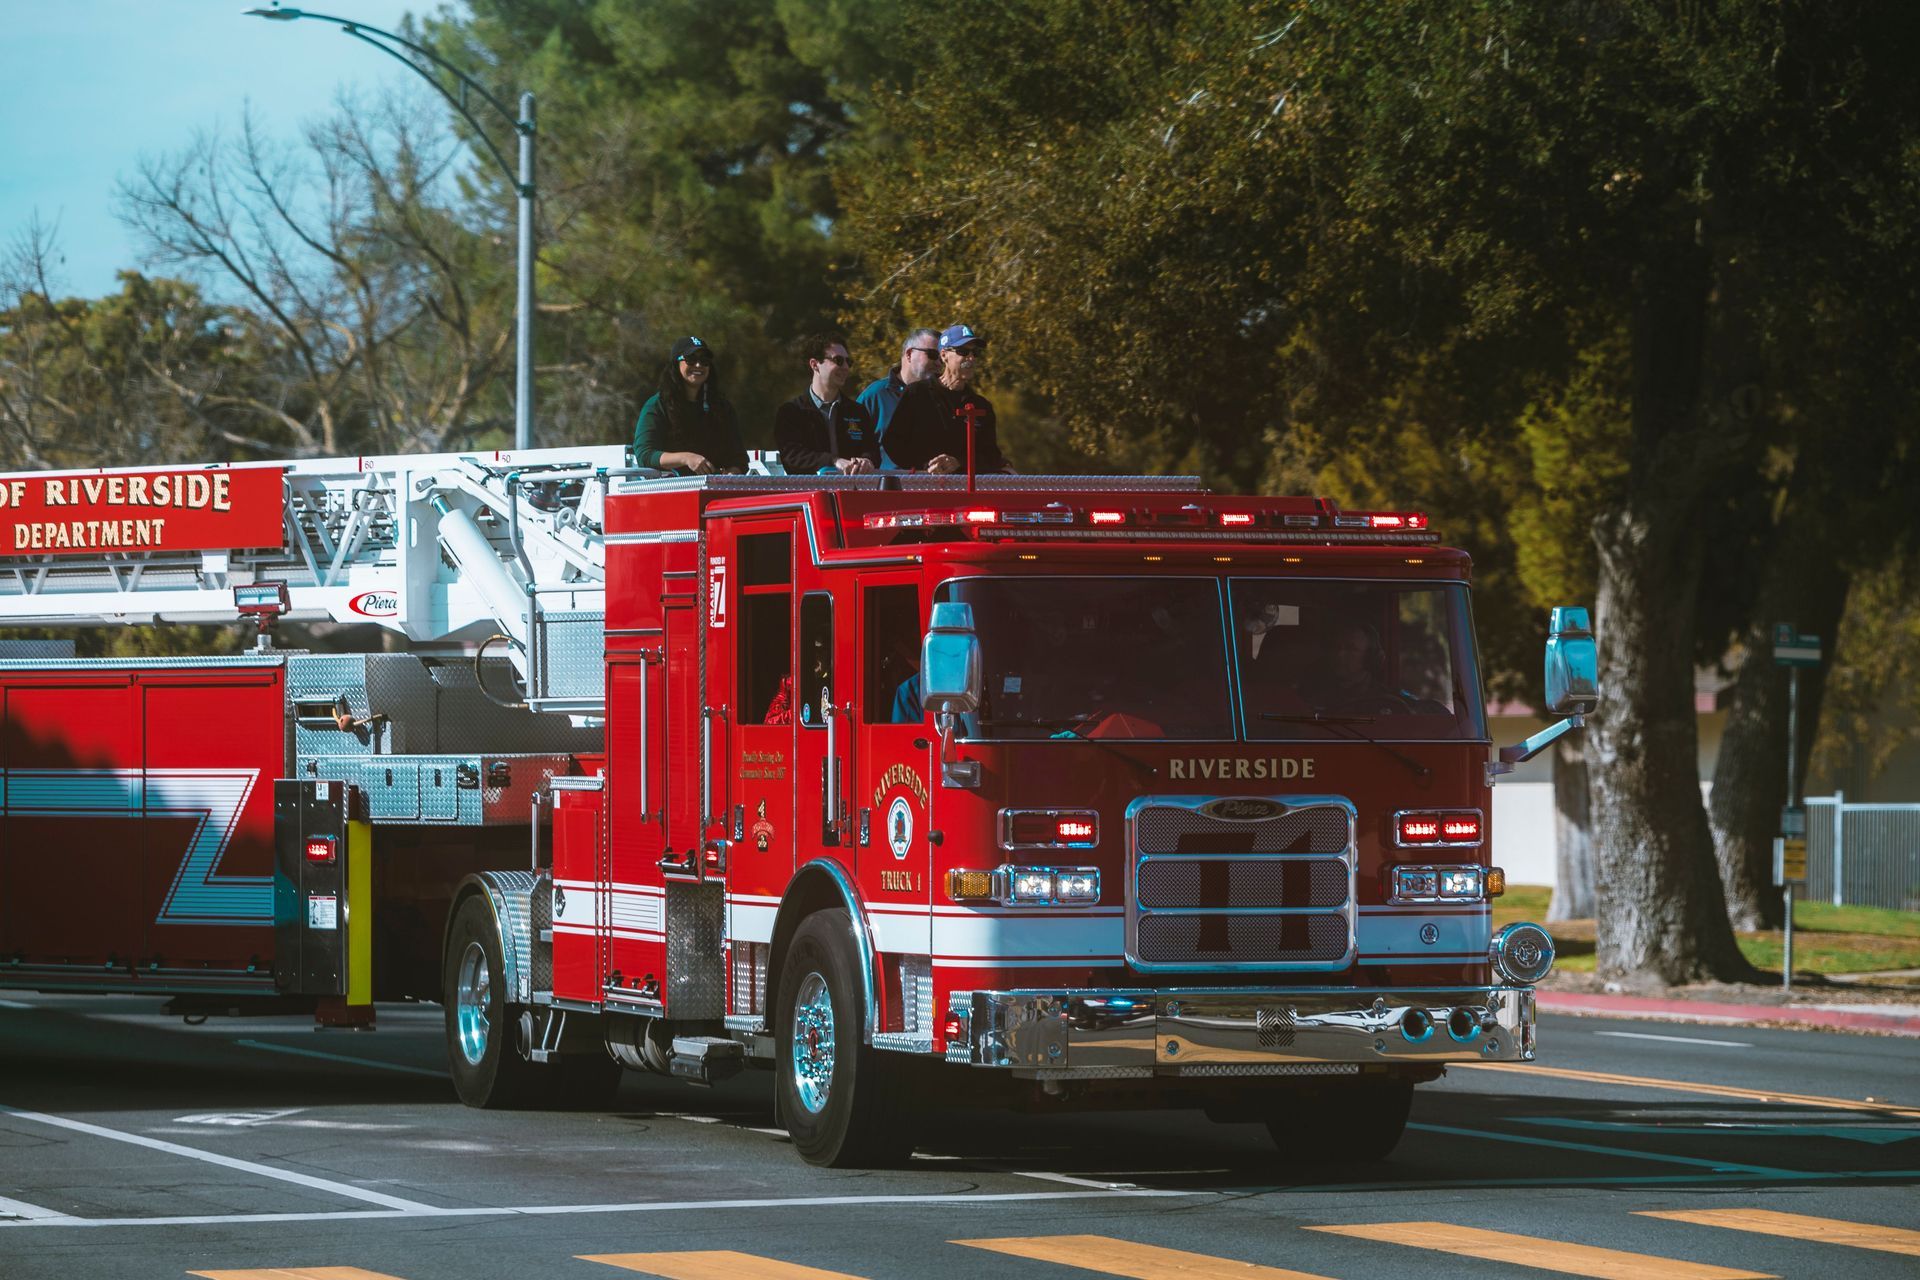
Your fire protection class is a score that shows how well your area can fight a house fire. It's based on things like your fire department, water supply, and distance to a fire station and hydrant.
Ratings usually run from 1 to 10. A lower number means better fire protection and often a lower premium. Homes in rural areas far from a fire station may have a higher class and pay more.
Does Your Street or Neighborhood Matter?
Yes. Even small details can change your rate:
- Trees: Large trees near your home can raise the risk of roof damage.
- Elevation: Low-lying areas may face more water and flood risk.
- Nearby water: Homes near lakes or creeks may face higher flood risk.
- Local claims: Neighborhoods with many past claims may see higher rates.
What Can You Do If You Live in a High-Rate Area?
You can't move your home, but you can still lower your premium:
- Install a Class 4 impact-resistant roof.
- Add a monitored security and fire alarm system.
- Bundle your home and auto insurance.
- Choose a higher deductible you can afford.
- Compare quotes from several carriers.
Different carriers view locations differently. One company may charge much less for your ZIP code than another. An independent agent can help you find the best fit.
Frequently Asked Questions
Why did my rate go up when I moved across town?
Your new ZIP code may have more storm claims, a different fire protection class, or higher building costs.
How can I find my fire protection class?
Ask your agent or your local fire department. Your agent can also see how it affects your rate.
Do rural homes cost more to insure?
Yes, they usually do. Homes far from a fire station or hydrant usually have a higher fire protection class and pay more.
Can I lower my rate in a high-risk area?
Yes. A new roof, safety upgrades, bundling, and comparing carriers can all help.
Get a Quote for Your Location
We're Miner Family Insurance, a local, independent agency in Edmond. We know the OKC area and compare more than 50 carriers to find the best rate for your home. Call (405) 724-2389 or request a home insurance quote online.