Insurance During Home Renovation Projects in Oklahoma
A new kitchen, an added room, or a fresh roof can make your home better and worth more. But a remodel also changes what your insurance needs to cover. If you don't update your policy, you could be underinsured when it matters most.
Here's what Oklahoma homeowners should know about insurance before, during, and after a renovation.
Why Do Renovations Change Your Insurance?
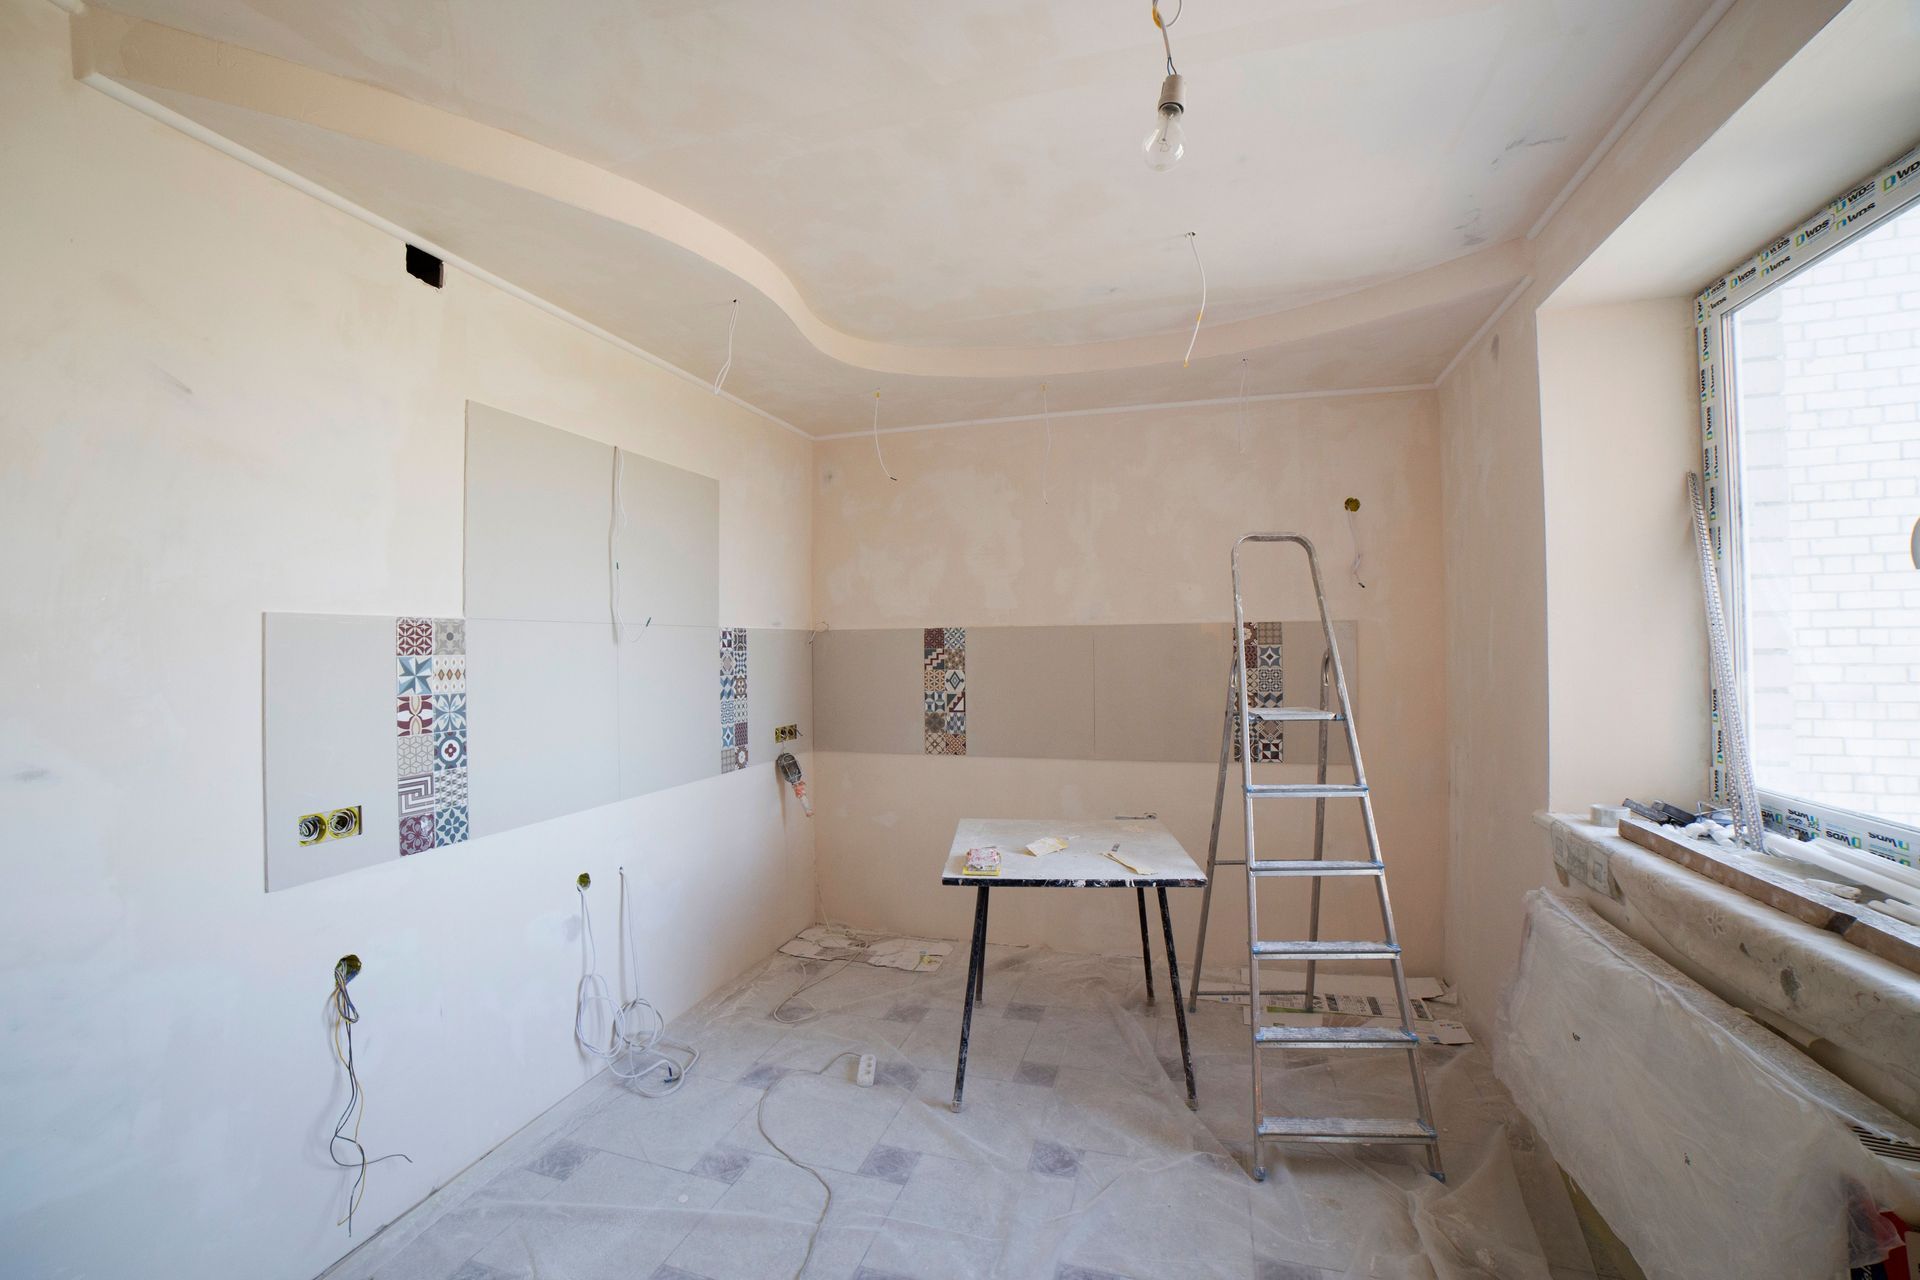
Your dwelling coverage should match what it would cost to rebuild your home. When you add space or upgrade finishes, that rebuild cost goes up. If your policy limit stays the same, you could come up short after a big loss.
Some projects can also lower your rate. A new roof, updated wiring, or new plumbing can make your home safer to insure.
Does Homeowners Insurance Cover Renovations?
Partly. Your homeowners policy still covers your home during a remodel, but there are limits. So, does homeowners insurance cover renovations? It depends on the size of the project and who is doing the work.
- Small projects: Painting, new flooring, or a bathroom refresh are usually fine under your current policy.
- Large projects: Additions, gut remodels, or projects that leave the home empty may need extra coverage.
- Vacant homes: Many policies limit coverage if the home is empty for 30 to 60 days. Tell your agent if you'll move out during the work.
Your policy usually won't pay for poor work, faulty materials, or damage caused by a contractor's mistake. That's what the contractor's insurance is for.
What Insurance Do You Need During a Home Renovation?
Good insurance during home renovation projects usually involves three policies working together:
- Your homeowners policy: Covers your existing home and belongings from covered causes like fire and wind.
- Your contractor's liability insurance: Covers damage or injuries caused by the contractor's work.
- Workers' compensation: Covers injuries to the contractor's crew. Without it, an injured worker could file a claim against you.
Always ask your contractor for a certificate of insurance before work starts. Make sure the policies are active and the limits are high enough.
What Is Builders Risk Insurance for Renovations?
Builders risk insurance for renovations covers the work in progress. It protects your materials, supplies, and new framing while the crew is still building. It can cover losses from fire, wind, hail, theft, and vandalism during construction.
You may need it if:
- You're adding a large addition or second story
- The project costs a large share of your home's value
- You'll move out while the work is done
- Your lender or insurer requires it
Sometimes the contractor buys builders risk coverage. Other times the homeowner does. Settle this in writing before the project starts.
Should You Tell Your Insurance Company About a Remodel?
Yes. Call your agent before work begins and again when it's done. Before you start, we can look for gaps, like vacancy limits or a need for builders risk coverage. Once it's done, we can raise your dwelling limit to match your new rebuild cost.
If you skip this step, your claim might not cover the full cost to rebuild your upgraded home.
Which Renovations Can Lower Your Premium?
Some upgrades can earn discounts or make you easier to insure:
- A new roof, especially Class 4 impact-resistant shingles
- Updated electrical, plumbing, and heating systems
- A monitored security or fire alarm system
- A storm shelter or safe room
- Water leak sensors and an automatic shutoff valve
Which Renovations Can Raise Your Premium?
Projects that add value or risk may raise your rate:
- Room additions and finished basements
- High-end kitchens and bathrooms
- Pools, hot tubs, and trampolines
- Home offices with costly equipment
A higher premium is better than being underinsured. Paying a bit more now is much cheaper than covering a gap after a fire or tornado.
Frequently Asked Questions
Do I need to update my insurance after a remodel?
Yes. Most remodels raise your rebuild cost, so your dwelling limit should go up too.
Who pays if a contractor damages my home?
Usually, the contractor's liability insurance pays. That's why you should check their coverage before work starts.
Does builders risk insurance replace my homeowners policy?
No. Builders risk covers the new work and materials. Your homeowners policy still covers your existing home and belongings.
Can I get a discount for a new roof?
Yes, in many cases. Many carriers offer a discount for a new or impact-resistant roof.
Planning a Renovation? Talk to Us First
We're Miner Family Insurance, a local, independent agency in Edmond. We'll help you protect your home before, during, and after your project. Call (405) 724-2389 or request a home insurance quote online.