Pool Liability Insurance Questions for Oklahoma Homeowners
A backyard pool is a great way to beat the Oklahoma heat. It also changes your insurance. A pool adds value to your home, but it also adds risk, mostly in the form of injuries and lawsuits.
Here are answers to the pool insurance questions we hear most from homeowners in Edmond and the OKC metro.
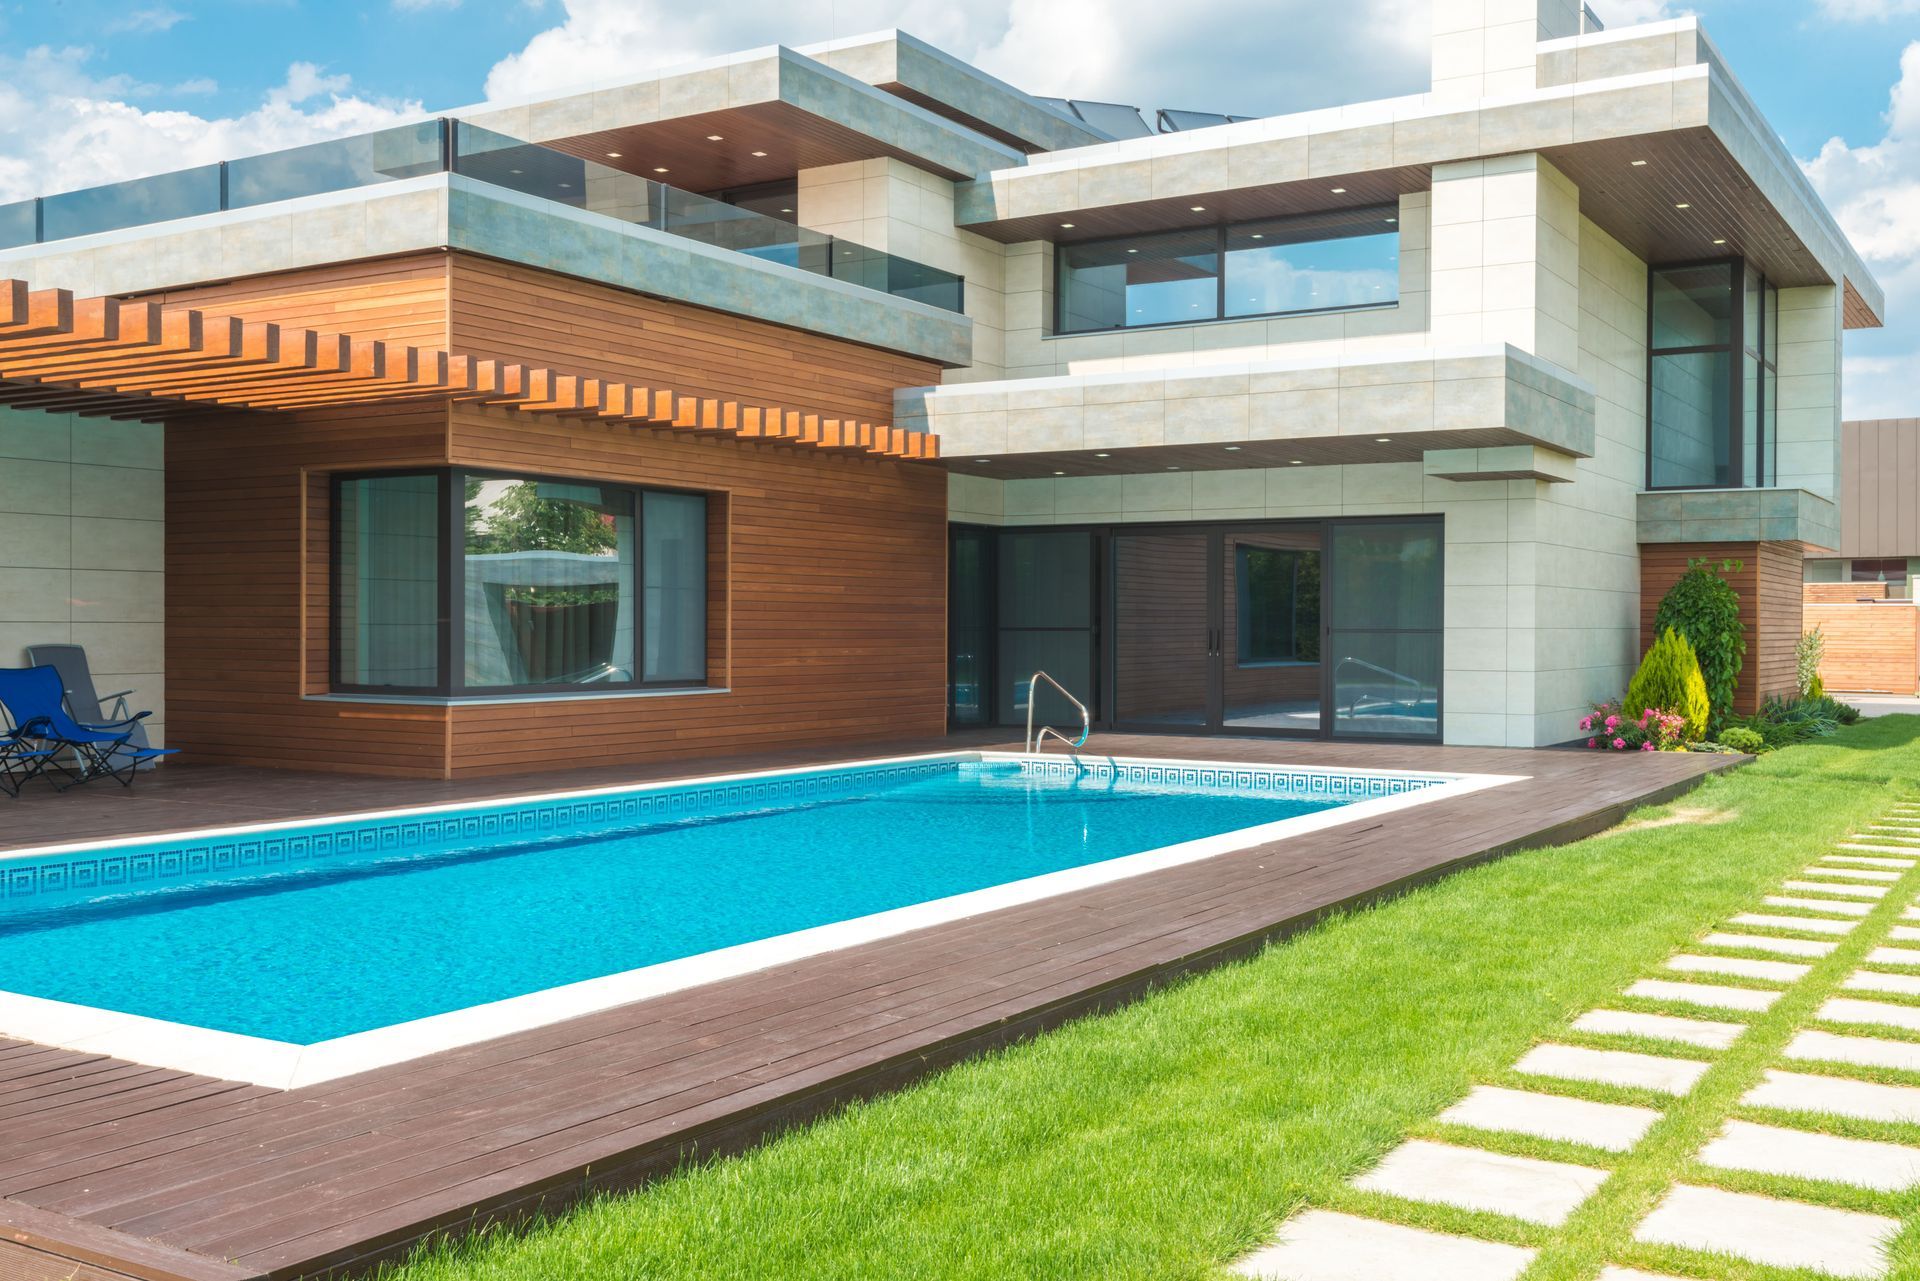
Does Homeowners Insurance Cover Pools?
Yes, in most cases. A standard homeowners policy usually covers your pool in two ways:
- Property coverage: An in-ground pool is usually covered under "other structures." An above-ground pool may fall under other structures or personal property, depending on your policy.
- Liability coverage: If a guest gets hurt at your pool, this coverage helps pay their medical bills and your legal costs.
So, does homeowners insurance cover pools for every kind of damage? No. Covered causes usually include fire, wind, hail, lightning, falling trees, and vandalism. Wear and tear, cracks from settling, and lack of upkeep are usually not covered.
What Does Homeowners Insurance Pool Coverage Include?
Homeowners insurance pool coverage can help pay for:
- Damage to the pool shell or liner from a covered storm
- Pool equipment like pumps, heaters, and filters
- Fences, decks, and pool houses
- Injuries to guests who use your pool
- Legal defense if someone sues you
Check your other structures limit. It's often 10% of your dwelling coverage. A pool, deck, fence, and shed can add up fast, so you may need to raise that limit.
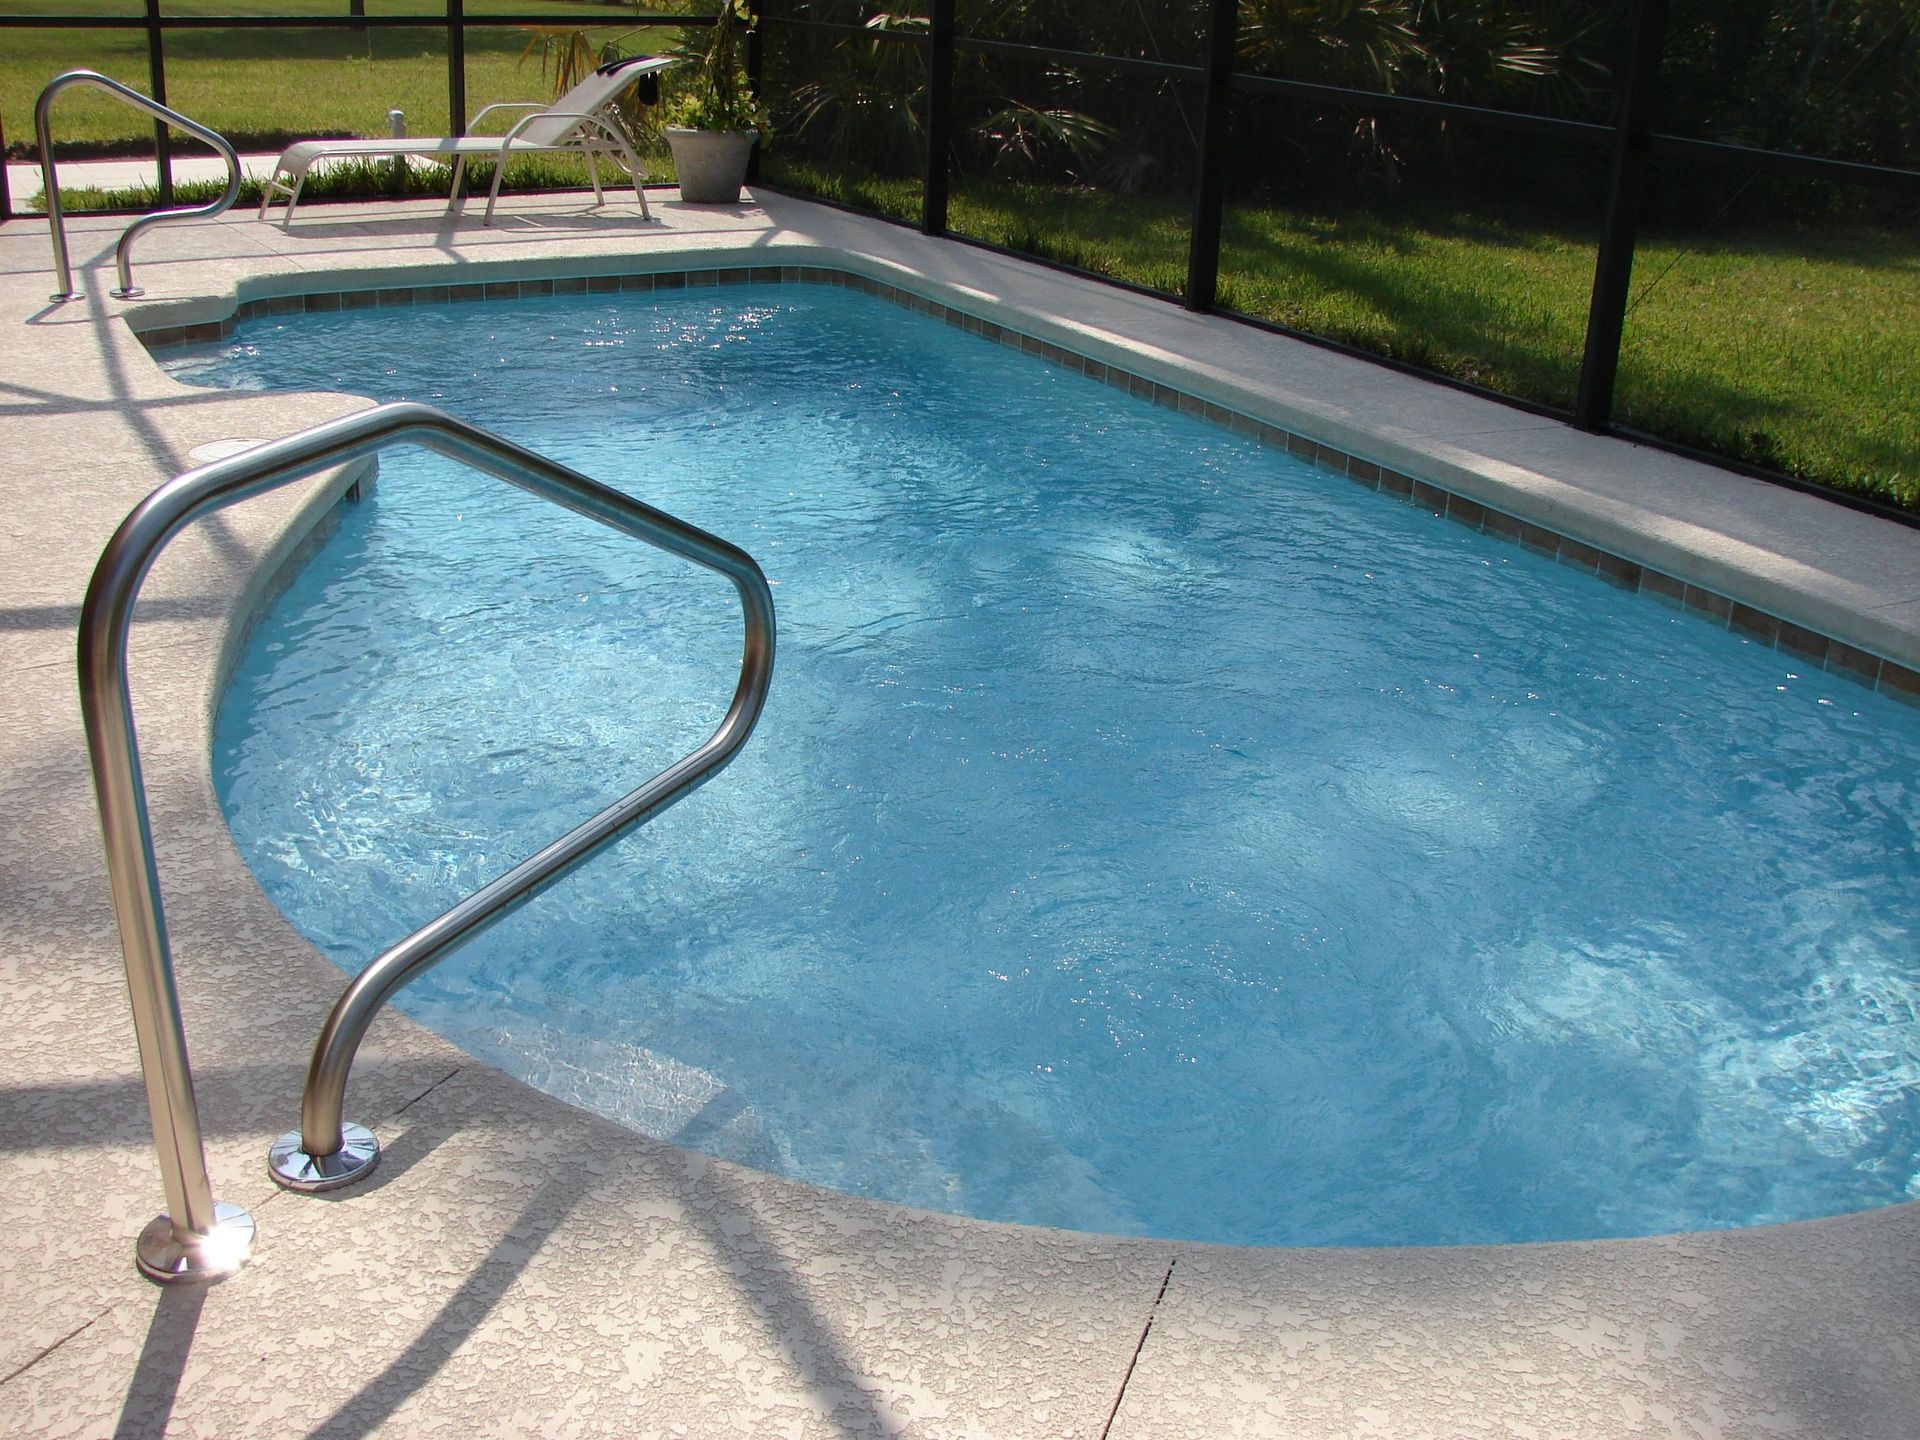
What Isn't Covered?
Most policies won't pay for:
- Leaks or cracks from age or poor upkeep
- Freeze damage if you didn't winterize the pool
- Damage from ground movement or settling
- Injuries from a diving board or slide, if your policy excludes them
- Flood damage, unless you have a separate flood policy
Read your policy for any pool, diving board, or trampoline exclusions. Some carriers have them, and some charge more to remove them.
How Much Liability Coverage Do You Need With a Pool?
Pools raise the risk of serious injuries, and serious injuries can lead to big lawsuits. A lot of basic policies start with just $100,000 of liability coverage. That's often not enough for a pool owner.
We usually suggest at least $300,000 to $500,000 in liability coverage. Many pool owners also add an umbrella policy.
What Is Pool Liability Insurance?
Pool liability insurance isn't usually a separate policy. It's just the liability part of your home policy, plus an umbrella policy if you add one. Together, they protect you if someone is hurt at your pool.
An umbrella policy adds $1 million or more of coverage on top of your home and auto limits. It's often affordable, and it gives pool owners extra peace of mind.
Will a Pool Raise Your Homeowners Insurance Rate?
It might. A pool can bump up your premium, since it adds value and more chances for injuries. How much it goes up depends on your carrier, your limits, and your safety features.
Some carriers won't insure homes with certain features, like diving boards or slides. If you're building a pool, call your agent before you start. That way, there are no surprises at renewal.
How Can You Make Your Pool Safer?
Safety steps lower the chance of injury, and some can help with your insurance:
- Put a fence at least 4 feet tall around the pool
- Use self-closing, self-latching gates
- Add a pool cover and an alarm
- Keep rescue gear, like a ring buoy, close by
- Post pool rules and never leave kids alone near the water
- Skip the diving board, or follow your carrier's rules for one
Your city may also have rules about pool fences and gates. Following them protects your guests and your coverage.
Frequently Asked Questions
Do I need to tell my insurance company about my pool?
Yes. Tell your agent when you add a pool. If you don't, your claim could be denied, or your coverage could be too low.
Are above-ground pools covered?
In most cases, they are. They may be covered as other structures or personal property, depending on your policy.
Does homeowners insurance cover a pool leak?
In most cases, no. Leaks from wear, age, or poor upkeep aren't covered. Sudden damage from a covered cause may be.
Is an umbrella policy worth it for pool owners?
For most pool owners, yes. It adds a lot of liability protection for a modest cost.
Talk to a Local Agent About Your Pool
We're Miner Family Insurance, a local, independent agency in Edmond. We'll review your homeowners insurance pool coverage and liability limits and compare more than 50 carriers. Call (405) 724-2389 or request a home insurance quote online.