By Josh Miner, licensed agent and owner of Miner Family Insurance in Edmond, OK. Updated October 2026.
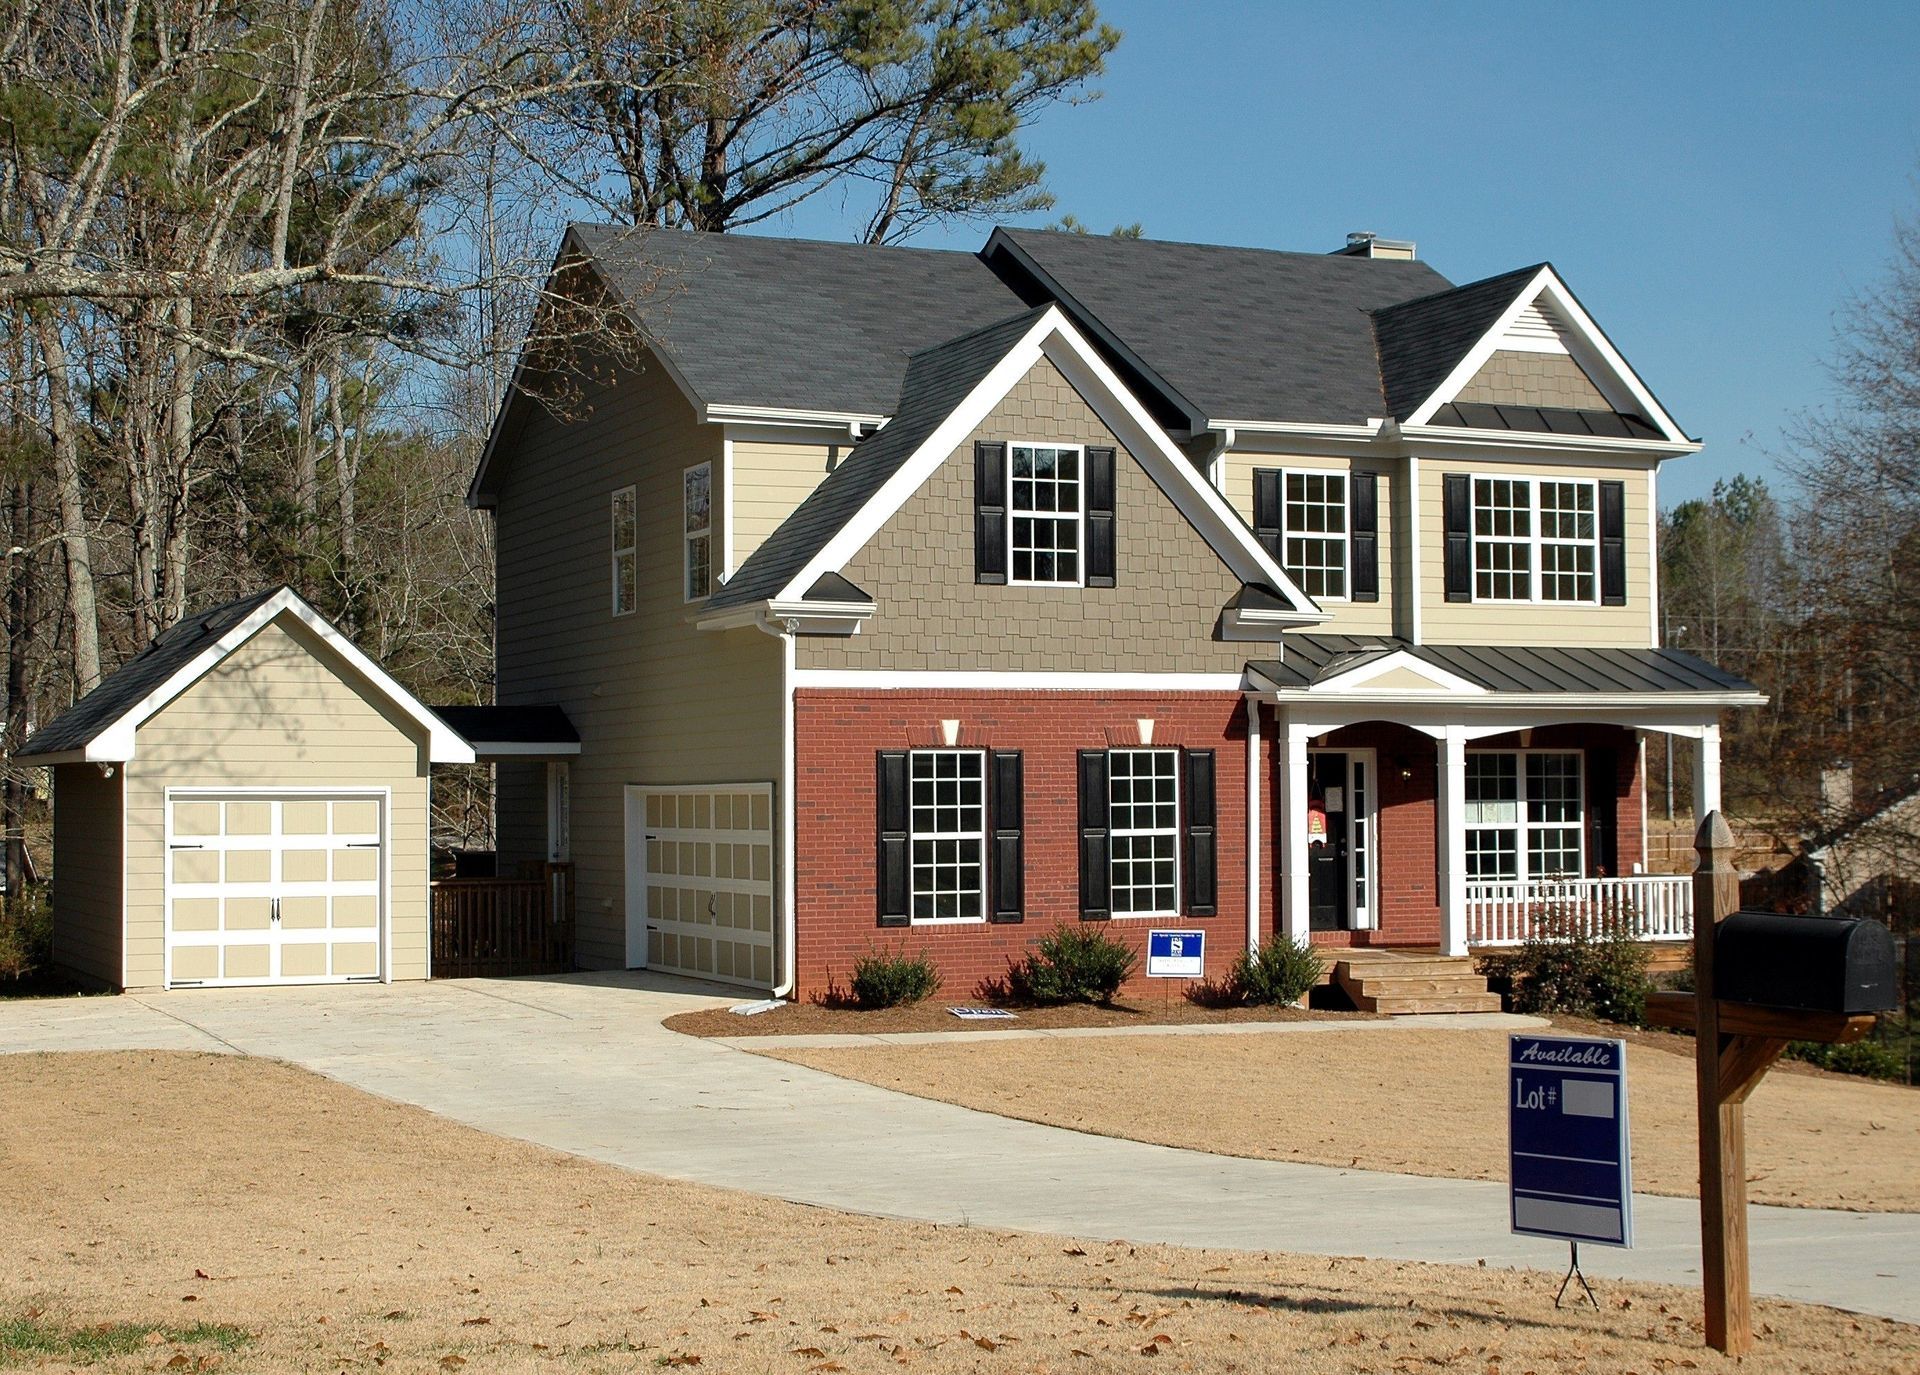
On a homeowners policy, a separate structure (also called an "other structure") is any building or structure on your property that is not attached to your house, or is connected only by a fence, utility line or similar. Detached garages, sheds, shops, barns, fences, gazebos, inground pools and driveways are common examples. They are covered under Coverage B, other structures, which is usually set at 10% of your dwelling coverage.
Key takeaways
- Other structures coverage is typically 10% of your dwelling limit. A $400,000 dwelling limit usually means $40,000 for all other structures combined.
- The limit is shared by every detached structure on the property, not per building.
- Structures attached to the house, like an attached garage or covered deck, fall under dwelling coverage instead.
- Structures rented to others or used for a business are usually excluded.
- You can raise the limit if you have a large shop, barn or guest house.
What counts as an other structure on homeowners insurance?
Most policies cover these as other structures when they are detached from the home:
- Detached garages and carports
- Storage sheds and workshops
- Barns and metal shop buildings
- Fences and gates
- Gazebos, pergolas and pavilions
- Inground swimming pools and pool houses
- Detached patios, retaining walls and driveways
- Guest houses that are not rented out
- Storm shelters that are not part of the house
What is attached versus detached?
The rule is simple: if a structure is physically attached to your house, it is usually covered under dwelling coverage (Coverage A). If it stands apart and is connected only by a fence, utility line, walkway or similar, it falls under other structures (Coverage B). A breezeway roof connecting a garage to the house can change how a carrier classifies it, so confirm with your agent.
How much other structures coverage do I need?
Add up what it would cost to rebuild every detached structure on your property today, including fencing. If the total is more than 10% of your dwelling limit, raise your other structures coverage. For example:
- Dwelling limit: $400,000, so default other structures limit: $40,000
- 40 x 60 metal shop: about $60,000 to rebuild
- Privacy fence: about $12,000
- Total needed: about $72,000.
You would want to raise Coverage B to at least $75,000.
Rebuild costs vary, so get a contractor estimate or ask your agent for help. This is especially common for acreage properties in areas like Piedmont, Arcadia and northeast Edmond.
What does other structures coverage protect against?
It covers the same perils as your home policy, typically including fire, lightning, wind, hail, falling trees, vandalism and theft. In Oklahoma, wind and hail claims on fences, shop roofs and detached garages are among the most common. Your wind and hail deductible usually applies. Learn how that works in our guide to 2% hail deductibles.
What is not covered under other structures?
- Structures rented to others,
such as a garage apartment or guest house you rent out (a rented garage used only for parking may be an exception).
- Structures used for business,
like a shop where you run a business. You may need a business policy or endorsement.
- Flood and earthquake damage,
which require separate policies.
- Wear and tear,
rot, pests and lack of maintenance.
- Contents of the structure,
which fall under personal property coverage, not other structures.
Frequently asked questions
Is an inground pool considered an other structure?
In most policies, yes. An inground pool and its decking are usually covered under other structures, so a pool can use up a large share of that 10% limit. An above-ground pool may be treated as personal property. Pools also raise liability risk, so review your liability limits too.
How many buildings are covered under other structures?
There is no limit on the number of structures, but they all share one coverage limit. Two sheds, a fence and a shop all come out of the same Coverage B amount.
Is a fence covered under homeowners insurance?
Yes. Fences are covered as other structures for covered perils like wind, hail, fire and falling trees. See our guide on whether Oklahoma home insurance covers fences.
Is my detached garage covered by homeowners insurance?
Yes, under other structures coverage. An attached garage is covered under your dwelling coverage instead.
Can I increase my other structures coverage?
Yes. Most carriers let you raise Coverage B above 10% for a small added premium. This is worth doing if you have a large shop, barn, pool or long fence line.
Is a shed covered if I run a business out of it?
Usually not. Structures used for business are typically excluded. You may need a business owners policy or a home business endorsement. Learn more about home-based business coverage.
Make sure your shop, fence and pool are covered
Miner Family Insurance can review your other structures limit and compare 50+ carriers, including options for acreage, large shops and barns. We are rated 5.0 stars by 322 Google reviewers. Call (405) 724-2389 or request a home insurance quote.