By Josh Miner, licensed agent and owner of Miner Family Insurance in Edmond, OK. Updated October 2026.
For a $500,000+ home in Oklahoma, the right policy insures the full cost to rebuild, not the market price. It adds 25% to 50% extended replacement cost, keeps the wind and hail deductible manageable, schedules jewelry and firearms, and pairs strong liability with a $1 million or larger umbrella. High-value carriers like Chubb, AIG and Travelers often handle this better than standard policies.
Key takeaways
- Insure a $500K+ home for its full rebuild cost, not its market value.
- Look for 25% to 50% extended replacement cost.
- Convert your wind and hail deductible to dollars: 2% on a $650,000 home is $13,000.
- Confirm whether your roof is paid at replacement cost or actual cash value.
- Schedule jewelry, art and firearms, and pair $500,000 in liability with a $1 million+ umbrella.
- Flood and earthquake need separate coverage in Oklahoma.

Why does a $500K+ Oklahoma home need a different approach?
A higher-value home usually has custom construction, premium finishes, larger detached structures and belongings that are expensive to replace. A standard homeowners policy can work as a starting point, but its default limits, roof settlement rules and theft limits are built for an average home, not a custom one.
The most important question is not "What is my home worth?" It is: "What would it cost to rebuild this exact home from the ground up today?"
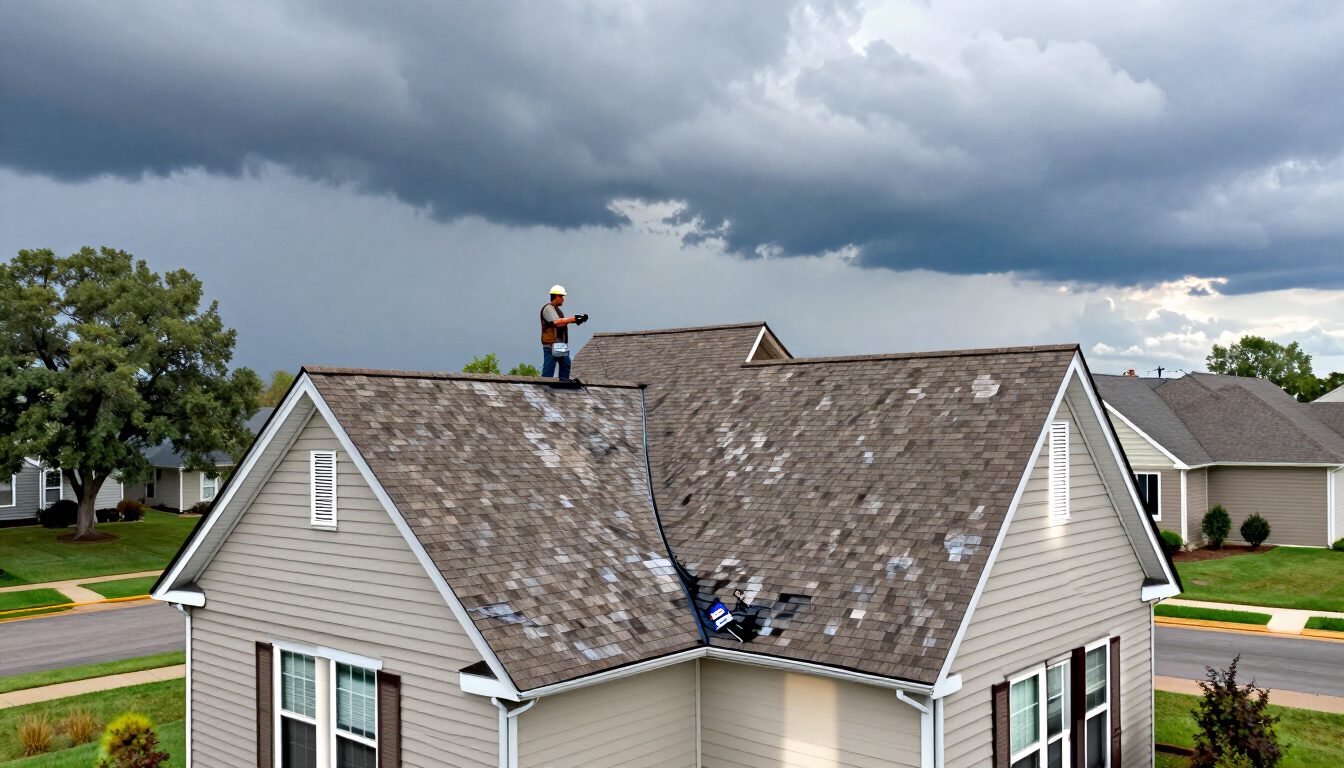
In Oklahoma, that question matters more than in most states. Hail, straight-line wind and tornadoes drive some of the largest property claims in the country, and after a widespread storm, contractor and material costs in the OKC metro can rise quickly. Homes in Edmond, Nichols Hills, Gaillardia, Oak Tree, Deer Creek and Piedmont often have custom features that standard rebuild estimates miss.
Think of your policy as a complete plan: dwelling, other structures, personal property, loss of use, liability, deductibles, exclusions and endorsements. Every piece should match the home you actually own.
The fastest way to see where you stand is to start a home insurance quote and ask how each proposed limit was calculated.
Standard vs. high-value home insurance: what is the difference?
Here is how a typical standard policy compares with a policy from a carrier that specializes in higher-value homes. Exact terms vary by carrier and policy form.
- Dwelling valuation: Standard policies often rely on a general estimating tool. High-value carriers commonly send an appraiser to document custom features and finishes.
- Extended replacement cost: Standard policies may offer 0% to 25% above the dwelling limit. High-value policies commonly offer 25% to 50%, and some offer guaranteed replacement cost.
- Roof claims: Many standard Oklahoma policies pay older roofs at actual cash value (depreciated). High-value policies are more likely to pay full replacement cost.
- Jewelry and valuables: Standard policies often cap jewelry theft at around $1,500. High-value policies offer higher limits, blanket coverage and scheduled items.
- Liability: Standard policies often carry $100,000 to $300,000. High-value policies commonly start at $500,000 and pair with an umbrella.
- Settlement options: Some high-value carriers offer a cash settlement if you choose not to rebuild after a total loss.
Why isn’t my home’s market value the right coverage amount?
Purchase price and reconstruction cost are two different numbers. Market value includes the land, which never needs to be rebuilt. Reconstruction cost includes things market value ignores: demolition, debris removal, code upgrades, permits, engineering and skilled custom labor. For many custom homes, rebuilding costs more per square foot than buying a comparable house.
Ask your agent how the replacement cost estimate was built and when it was last updated. A remodel, addition, new roof, upgraded kitchen or a jump in local construction costs can make last year’s number too low.
How do wind and hail deductibles work in Oklahoma?
Many Oklahoma policies carry a separate wind and hail deductible written as a percentage of the dwelling limit, commonly 1% to 5%. On a higher-value home, that percentage turns into real dollars.
- 1% deductible on a $650,000 dwelling limit: $6,500 out of pocket
- 2% deductible on a $650,000 dwelling limit: $13,000 out of pocket
- 5% deductible on a $650,000 dwelling limit: $32,500 out of pocket
A higher deductible lowers your premium, but choose a number you could comfortably pay after a hailstorm. Some carriers offer a flat dollar wind and hail deductible on higher-value homes, which can be a better fit. You can also learn how a wind and hail deductible buyback can reduce that out-of-pocket cost.
How are roofs handled on Oklahoma home insurance claims?
Roof terms are where Oklahoma policies differ the most. For a deeper look, see our guide to roof payment schedules vs. replacement cost in Oklahoma. Check these four things before you renew:
- Replacement cost vs. actual cash value: Some carriers pay roofs older than 10 to 15 years at depreciated value, which can leave you paying thousands toward a new roof.
- Cosmetic damage exclusions: Many policies exclude hail dents on metal roofs that do not cause leaks.
- Impact-resistant roofs: Class 4 shingles and FORTIFIED roofs can earn discounts with many carriers. Ask about the Oklahoma Insurance Department’s Strengthen Oklahoma Homes program.
- Roof age limits: Some carriers will not write a new policy on a roof past a certain age.
What is extended replacement cost, and do I need it?
Extended replacement cost adds coverage above your dwelling limit if rebuilding costs more than expected. If your home is insured for $800,000 with 25% extended replacement cost, you could have up to $1,000,000 available to rebuild after a covered loss.
This matters most after a widespread disaster, when hundreds of homes in the same area need contractors and materials at once. That demand surge is common after major Oklahoma hail and tornado events.
Extended replacement cost does not replace an accurate dwelling limit. To get the most from it:
- Give your carrier accurate square footage, construction type, finishes, roof, foundation and HVAC details.
- Report additions, remodels, custom work and outbuildings.
- Ask whether the endorsement is a percentage or a dollar cap.
- Ask whether ordinance or law coverage is included or separate.
What does a standard policy not cover in Oklahoma?
Two of the biggest gaps for Oklahoma homeowners are flood and earthquake. Neither is covered by a standard homeowners policy.
- Flood: Flash flooding can reach homes outside mapped flood zones. A separate flood insurance policy fills the gap, and NFIP policies usually have a 30-day waiting period.
- Earthquake: Oklahoma sees regular seismic activity. An earthquake insurance policy or endorsement covers what your home policy excludes.
- Water backup: Sewer and drain backup is often excluded unless you add it.
- Service lines: Damage to underground utility lines on your property usually requires an endorsement.

How should I insure jewelry, art, firearms and other valuables?
Standard policies limit theft coverage on categories like jewelry, watches, firearms, silverware and collectibles. Scheduling an item lists it separately at an appraised or agreed value and often covers accidental loss, like a stone falling out of a ring, frequently with no deductible.
Benefits of scheduling valuables commonly include:
- Higher limits for each listed item
- Coverage for mysterious disappearance and accidental loss
- No category sublimit
- Agreed value settlement with many high-value carriers
- A faster claim when ownership and value are documented
Keep appraisals, receipts, photos and serial numbers stored digitally. Update jewelry and art appraisals every 3 to 5 years, since values change.
How much liability coverage should a higher-value household carry?
Liability coverage pays when you are legally responsible for someone else’s injury or property damage, including legal defense costs. Higher-value households have more to lose in a lawsuit and often more exposure: pools, trampolines, dogs, frequent guests, household employees, teen drivers, ATVs and rental properties.
Many higher-value homeowners carry $500,000 in liability on the home policy and add a $1 million to $5 million umbrella. The right limit depends on your assets, income and activities.
When reviewing liability, ask about:
- Medical payments coverage for guests
- Exclusions for vehicles, watercraft, business activities and rentals
- Coverage for other properties you own, including rentals and land
When does an umbrella policy make sense?
An umbrella policy adds liability protection above your home, auto and watercraft policies, usually in $1 million increments. For most households it is one of the lowest cost ways to add serious protection. Carriers typically require minimum underlying limits on your home and auto policies first.
Before you buy an umbrella, confirm:
- Which underlying policies need specific liability limits
- Whether the carrier requires your home and autos to be insured with them
- Exclusions for business, rental, watercraft and recreational activities
- Whether uninsured and underinsured motorist coverage is available
- How the umbrella works with trusts, LLCs or other ownership arrangements
Learn more on our umbrella insurance page or request an umbrella insurance quote.
Which carriers insure high-value homes in Oklahoma?
The carrier matters as much as the price. Carriers differ in how they calculate rebuild costs, settle roof claims, set wind and hail deductibles, and treat custom homes, acreage and detached structures.
Miner Family Insurance is an independent agency with access to 50+ carriers, including high-value specialists like Chubb, AIG and Travelers, plus carriers such as Liberty Mutual, Allstate, Progressive, Openly and Mercury. That lets us match your home to the carrier that fits it instead of forcing it into one company’s guidelines.
When comparing carriers, look at:
- Whether the insurer specializes in higher-value homes
- How dwelling replacement cost is calculated and updated
- Roof settlement terms and roof age rules
- Wind and hail deductible options
- Available endorsements and their limits
- Claims service and local adjuster availability
- AM Best financial strength rating
- Total cost across home, auto and umbrella
The cheapest quote is not the best value if it comes with a restrictive roof schedule, a large percentage deductible or low limits. The most expensive quote may include features you do not need. Compare coverage line by line, not just premium.
See the insurance carriers we work with, or start a free policy review and we will compare your current coverage side by side.
Higher-value home insurance checklist
Use this checklist before you renew or switch carriers:
- Verify square footage, improvements, finishes, roof details and outbuildings.
- Confirm the dwelling limit reflects current reconstruction cost, not market value.
- Calculate your wind and hail deductible in dollars.
- Confirm whether your roof is paid at replacement cost or actual cash value.
- Add extended replacement cost and ordinance or law coverage.
- Create a home inventory and schedule high-value items.
- Consider flood, earthquake, water backup and service line coverage.
- Reassess liability limits and whether an umbrella fits.
- Compare deductibles, exclusions, endorsements and carrier requirements, not just price.
Review your coverage after a purchase, remodel, roof replacement, inheritance, major jewelry or art purchase, marriage, new pool, new dog, new teen driver or any big change in assets.
Frequently asked questions about high-value home insurance in Oklahoma
What counts as a high-value home for insurance in Oklahoma?
There is no single legal threshold, but most agents and carriers treat homes with a rebuild cost of roughly $500,000 or more as higher value, especially with custom construction, premium finishes, large outbuildings or significant valuables. Some specialist carriers set their own minimum dwelling limits.
Is home insurance more expensive for a $500,000 home in Oklahoma?
Usually, yes. In Edmond, most $500,000 homes we insure run around $3,100 per year. Rebuild cost, contents and liability limits are all higher, and Oklahoma premiums run above the national average because of hail and wind. Your price depends on location, construction, roof age and type, deductible, claims history and carrier, so comparing several carriers matters.
Does Oklahoma home insurance cover hail damage?
Yes, standard Oklahoma homeowners policies generally cover hail. Many apply a separate percentage wind and hail deductible, and some pay older roofs at actual cash value or exclude cosmetic damage to metal roofs. Review your roof terms before storm season.
Does homeowners insurance cover jewelry and artwork automatically?
Only partly. Standard policies include some coverage, but theft of jewelry, watches, firearms and collectibles is usually capped at a low limit. Scheduling valuable items gives each one its own limit and broader protection, usually backed by an appraisal.
Does homeowners insurance cover earthquakes in Oklahoma?
No. Earthquake damage is excluded from standard homeowners policies. Oklahoma homeowners can add coverage through a separate earthquake policy or endorsement, usually with its own percentage deductible.
Do I need umbrella insurance if I have a high-value home?
Not every homeowner needs one, but it is worth considering when your assets, income, pool, vehicles, guests or rental properties create more liability exposure. Umbrellas are usually sold in $1 million increments and are one of the most affordable ways to add protection.
Which insurance companies cover high-value homes in Oklahoma?
High-value specialists include Chubb, AIG and Travelers, and several other carriers write custom and higher-value homes in Oklahoma. An independent agency like Miner Family Insurance can quote multiple carriers at once to find the best fit.
Who are the best home insurance companies for high-value homes in Edmond, OK?
There is no single best company for every Edmond home. The right fit depends on your rebuild cost, roof, location and valuables. High-value specialists like Chubb, AIG and Travelers are often strong choices for $500K+ homes in Edmond, Deer Creek and Oak Tree. An independent agency can quote several of them at once and compare coverage side by side.
How much does home insurance cost for a $500,000 home in Edmond, OK?
Most $500,000 homes we insure in Edmond run around $3,100 per year. Price depends most on roof age and type, your wind and hail deductible, claims history and coverage limits. Edmond premiums generally run above the national average because Oklahoma has some of the most hail and wind claims in the country. Comparing several carriers side by side is the most reliable way to lower your price without cutting coverage.
Should I use an independent or captive insurance agent in Edmond?
An independent agent can quote many carriers, while a captive agent represents one company. For higher-value homes, more carriers usually means a better match on roof terms, deductibles and valuables coverage. Miner Family Insurance is an independent agency with access to 50+ carriers. Learn more in our guide to independent vs. captive insurance agents.
Can I get home insurance in Edmond with an older roof?
Usually yes, but an older roof often comes with actual cash value roof coverage, a higher wind and hail deductible or fewer carrier options. Some carriers will not write a new policy on a roof past a certain age. A Class 4 impact-resistant or FORTIFIED roof can open up more carriers and discounts.
Is Miner Family Insurance located in Edmond?
Yes. Miner Family Insurance is based at 3209 S Broadway Ste 231, Edmond, OK 73013, and works with clients by phone, email and online across the Oklahoma City metro. Call (405) 724-2389 or visit our Edmond insurance page.
What areas does Miner Family Insurance serve?
We serve Edmond, Deer Creek, Oklahoma City, Nichols Hills, Yukon, Piedmont, Mustang, Tuttle, Blanchard, El Reno and communities across Oklahoma, with access to 50+ home, auto, life and commercial carriers.
How often should I review insurance for a higher-value Oklahoma home?
At least once a year, and any time your home, belongings, household or finances change. Construction costs and carrier guidelines change too, so an updated replacement cost estimate keeps your limits aligned.
Get a free high-value home coverage review
For a $500,000+ Oklahoma home, the goal is not simply to buy more insurance. It is to line up accurate dwelling coverage, protection for your valuables, the right deductibles, strong liability limits and a carrier that fits your property. A free coverage review shows whether your current policy still matches your home and assets.
Miner Family Insurance is rated 5.0 stars by 322 Google reviewers and was voted a 2026 Nextdoor Neighborhood Fave. Contact Miner Family Insurance or request a home insurance quote to compare options from 50+ carriers. We serve Edmond, Deer Creek, Oklahoma City, Yukon, Piedmont and the surrounding communities.
About the author
Josh Miner is the owner of Miner Family Insurance, an independent agency he founded in Edmond at age 23 to make insurance simpler and give Oklahoma families real options. He and his team compare 50+ carriers, including Chubb, AIG and Travelers, to match homeowners with the right coverage. Meet our team.