Master Policy vs Individual Policies: Best for 7+ OK Rentals
August 21, 2026

Choosing between a master policy vs individual policies for an Oklahoma rental portfolio depends largely on your administrative threshold and total unit count. A master policy, often called a commercial schedule, consolidates 7 or more properties into a single contract with one renewal date and one premium payment, whereas individual policies require separate management for every property. For real estate investors in the Sooner State, the master policy typically offers superior scalability, blanket liability limits, and simplified reporting for complex storm-related claims.

Should you choose a master policy or individual policies for 7+ rentals?

If you are currently managing seven or more rental properties in Edmond, Yukon, or the greater Oklahoma City area, you probably feel less like a real estate mogul and more like a professional paper-pusher. Managing seven different insurance documents, seven different renewal dates, and seven different escrow payments is a recipe for a headache that even the strongest Oklahoma-brewed coffee can’t fix.

When we look at master policy vs individual policies , the transition point usually occurs right around that seven-unit mark. Why seven? Because that is where the administrative burden of individual Landlord Insurance starts to outweigh the flexibility it provides. A master policy allows you to list every property on a single "schedule." Think of it as a spreadsheet that the insurance company actually likes. You get one bill, one point of contact, and most importantly, one set of consistent coverage terms across your entire portfolio.

However, individual policies aren't without their charms. If your portfolio is a "mutt"—meaning you have a mix of short-term Airbnbs, standard long-term rentals, and perhaps a commercial storefront—individual policies might be necessary. Some specialized lenders also have very specific "loss payee" requirements that are easier to satisfy with a standalone Home Insurance style landlord form (DP-3). But for the serious investor looking to scale, the master policy is the path to sanity.

https://irp.cdn-website.com/63be3043/dms3rep/multi/1787321873849-1_1-zNl.png

How does Oklahoma’s weather affect your portfolio insurance?

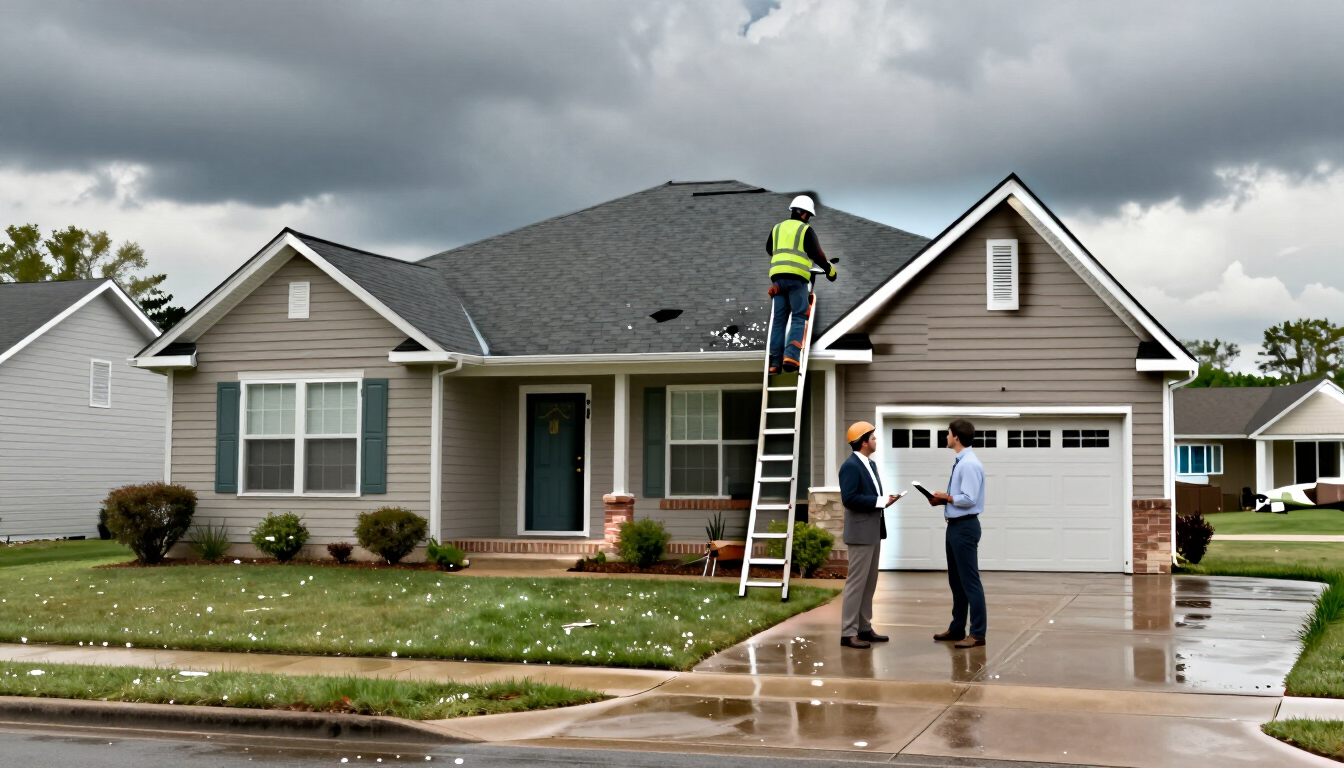
In Oklahoma, we don’t just have weather; we have events. When a massive hailstorm or a tornado rolls through Moore or Piedmont, it doesn't just hit one house—it hits the whole neighborhood. If you have ten individual policies with ten different companies (or even the same company with ten different deductibles), you are in for a logistical nightmare.

With a master policy, you are dealing with a single claim filing for the entire incident. This is crucial for "systemic loss." If a storm damages five of your properties simultaneously, a master policy provides a unified response. Here is why the Oklahoma context matters:

  • Deductible Aggregation: Some master policies allow for a per-occurrence deductible that might cap your out-of-pocket costs if multiple locations are hit by the same storm. Individual policies will always charge you a separate deductible for every single house.
  • Consistency in Roofing Claims: We all know the "Oklahoma Roof Replacement" dance. Having one carrier handle all seven properties ensures you don't get seven different adjusters giving you seven different opinions on whether that hail hit was "functional" or "cosmetic."
  • Standardized Wind/Hail Deductibles: You can set a consistent 1% or 2% wind/hail deductible across the board, making your cash flow much more predictable when the sirens start blaring.

The Logistics of Lost Rent and General Liability

When you are debating a master policy vs individual policies , you have to look beyond the physical bricks and mortar. You have to look at the "invisible" coverages: General Liability (GL) and Loss of Rents.

In a master policy, you often have the benefit of "Blanket Limits." This means your liability coverage isn't just tied to one specific address; it’s a larger pool of protection that covers the entity owning the properties. This is often more cost-effective than buying seven separate $500,000 liability limits. Furthermore, you can easily stack a Business Insurance umbrella over the top of a master policy to ensure that one slip-and-fall doesn't liquidate your entire life's work.

Loss of Rent (Business Income) is another area where master policies shine. In Oklahoma, if a tornado makes three of your units uninhabitable, the "Lost Rent" coverage kicks in to keep your mortgage payments current while the units are being rebuilt. Master policies usually offer 12 to 24 months of actual loss sustained, which is vital given how long construction can take after a major disaster in the Sooner State.

Master Policy vs Individual Policies: The Comparison

To help you decide which path fits your current growth stage, we’ve broken down the key differences between the two structures. Most investors find that once they hit the "7-unit wall," the administrative savings alone justify the switch to a master schedule.

| Feature | Master Policy (Commercial Schedule) | Individual Policies (Personal/Landlord) | Renewal Date | Single date for all properties | Multiple dates throughout the year || Billing | One invoice; easier for bookkeeping | Separate invoices for every property || Liability | Often "Blanket" limits across portfolio | Fixed limits per location || Scalability | Add/Remove properties with a simple endorsement | Requires a full new application per unit || Ideal For | 7+ properties under one entity | 1-6 properties or varied ownership |

Why do Oklahoma investors prefer consolidated billing?

Let's talk about the "Escrow Apocalypse." If you have seven properties with seven different lenders, and each lender is trying to pay a different insurance bill at a different time of year, something is going to get messed up. It’s an mathematical certainty. By moving to a master policy, you can often pull your insurance out of escrow (depending on your LTV) and pay one annual or monthly premium directly.

This gives you total control over your cash flow. No more waiting for a bank in another state to realize they forgot to pay your premium in Yukon, OK. Additionally, having one Umbrella Insurance policy tied to a single master policy is significantly cheaper than trying to link seven disparate individual policies to a single personal umbrella. It’s about building a professional infrastructure for a professional business.

https://irp.cdn-website.com/63be3043/dms3rep/multi/1787321873850-1_1-Lsz.png

Frequently Asked Questions About Portfolio Insurance

Can I add a new rental property to my master policy mid-term?

Yes, adding a property is usually a simple one-page endorsement that pro-rates the premium for the remainder of the policy term, making scaling your business much faster.

Is a master policy cheaper than individual policies in Oklahoma?

While the per-unit price can be lower due to bulk discounting and shared liability, the primary savings usually come from reduced administrative costs and more efficient coverage structures.

Do I need a separate LLC for each property on a master policy?

Not necessarily, but the properties on a single master policy generally need to be owned by the same entity or have common ownership to qualify for the commercial schedule.

How does a master policy handle different roof ages?

Each property on the schedule is still rated based on its individual characteristics, so a brand-new roof will still get a better rate than a 20-year-old one, even on a master policy.

What happens if I sell one property in the middle of the year?

You simply notify your agent to remove that specific address from the schedule, and you will receive a pro-rated credit for the unused premium on that location.

The Bottom Line for Growing Landlords

Ultimately, the choice between a master policy vs individual policies comes down to how you value your time. If you are a hobbyist with two houses, individual policies are perfectly fine. But if you are a real estate investor with 7+ units in Oklahoma, you are running a business, and businesses need commercial-grade tools. A master policy provides the stability, administrative ease, and robust protection required to survive Oklahoma’s volatile weather and the complexities of property management.

Ready to stop drowning in insurance paperwork and start protecting your portfolio like a pro? Whether you need to compare rates or consolidate your current holdings, we are here to help you navigate the unique challenges of the Oklahoma market.

Next Steps for Investors:

  • Review your current renewal dates—if they are scattered, it’s time to consolidate.
  • Check your total liability limits across all entities.
  • Evaluate your current loss of rent coverage to ensure it covers at least 12 months.

Get your portfolio quoted both ways with Miner Family Insurance today and see which structure saves you more time and money.

Oklahoma home with wind and hail deductible buyback coverage
October 5, 2026
Learn how a standalone wind/hail deductible buyback policy can reimburse Oklahoma homeowners after a covered storm, including premiums, examples, and roof ACV limits.
Home insurance myths for Oklahoma homeowners
October 3, 2026
Home insurance myths can leave Oklahoma homeowners underinsured. Learn what coverage really protects against, from replacement cost to flood, wind, liability, and credit.
Oklahoma home insurance non-renewal and roof inspection
September 29, 2026
Learn why Oklahoma insurers non-renew homeowners policies, including roof age, hail claims and catastrophe limits, plus what to do after a non-renewal notice.
Oklahoma home insurance premiums affected by storm risk and rising rebuild costs
September 24, 2026
Why do Oklahoma home insurance premiums rise with zero claims? Learn how rate filings, storms, reinsurance, roofs, credit, and rebuild costs affect your rate.
Independent insurance agent comparing coverage options with Oklahoma shoppers
September 22, 2026
Compare an independent insurance agent vs. a captive agent in Oklahoma, including carrier access, pricing flexibility, switching options, and what to ask before choosing.
Independent insurance agent comparing Oklahoma home insurance options with a homeowner
September 17, 2026
Compare an independent insurance agent with a direct carrier for Oklahoma home insurance, including carrier choice, storm risks, claims support, and coverage questions.
Commercial insurance for Oklahoma landlords reviewing property coverage
September 17, 2026
Learn when Oklahoma landlords need commercial insurance instead of personal coverage, including unit count, ownership, tenants, and entity structure.
Modern multi-family residential building in Oklahoma at sunset representing commercial real estate.
September 8, 2026
Learn exactly when Oklahoma landlords need to switch from personal to commercial insurance. Covers unit counts, LLC ownership, and portfolio growth strategies.
Modern rental homes in Oklahoma representing property investment portfolio protection.
September 4, 2026
Discover why umbrella insurance is essential for Oklahoma landlords and real estate investors. Learn how to protect your rental portfolio from liability risks and lawsuits.
A beautiful modern home in Edmond Oklahoma representing a short-term rental property.
September 1, 2026
Ensure your Oklahoma rental is protected. Discover why Airbnb and VRBO owners need specialized short-term rental insurance to cover liability and storms.
Show More