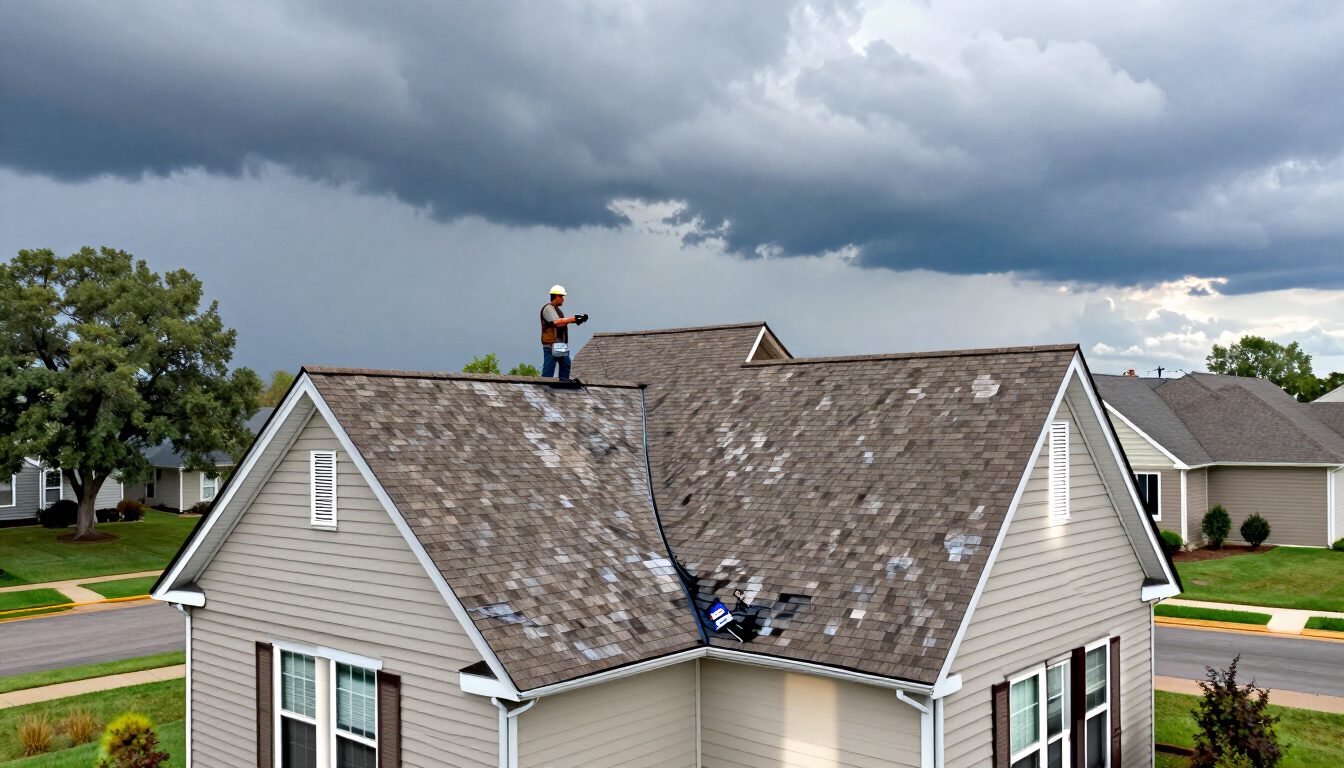
Home insurance in Oklahoma should be arranged as soon as you are seriously considering a home, ideally before making an offer. Compare quotes early, confirm the policy meets your lender's requirements, and review roof age, claims history, and wind and hail deductibles before closing.
When should you get home insurance quotes in Oklahoma?
Start getting home insurance quotes in Oklahoma before you make an offer or at least while you are house hunting. You do not need a finalized closing date to ask an agent for an estimate. Early quotes help you understand the likely insurance cost before you commit to a monthly mortgage payment.
An insurance quote can also reveal issues that affect your decision, such as an older roof, prior property claims, limited wind coverage, or a high deductible. Finding those issues after you sign a purchase contract can create unnecessary pressure.
A practical timeline looks like this:
- While house hunting: Ask for rough estimates on homes you may buy.
- Before making an offer: Request a more detailed quote using the property address.
- After your offer is accepted: Provide the insurer with the inspection report, roof details, and lender information.
- Before closing: Bind the policy and send proof of insurance to your lender.
For a starting point, visit Miner Family Insurance’s
home insurance quote page . Sharing the address and basic property details allows an agent to identify questions early rather than rushing through them at closing.
Need a quote on a tight timeline? Call Miner Family Insurance at (405) 724-2389.
What do Oklahoma lenders require before closing?
Most mortgage lenders require proof of homeowners insurance before they will fund a loan. The policy generally must begin on the closing date and provide enough dwelling coverage to protect the lender’s financial interest in the home.
Your lender may ask for:
- The insurance company’s name and contact information
- The policy number or binder
- The effective date, usually the closing date
- The dwelling coverage limit
- The mortgagee clause with the lender’s exact legal name and address
- Evidence that the first premium has been paid or included in closing funds
The lender’s minimum requirements are not necessarily the same as your ideal protection. A policy can satisfy the lender while still leaving gaps involving personal property, additional living expenses, water backup, service lines, or wind and hail losses.
Send your lender’s insurance instructions to your agent as soon as you receive them. Small errors in the mortgagee clause or effective date can delay approval, and correcting them at the last minute is avoidable.
How does roof age affect home insurance prices?
Roof age is one of the most important factors in an Oklahoma home insurance quote because older roofs are more likely to experience damage or require replacement. Insurers may charge more, restrict coverage, require an inspection, or decline a property with a roof near the end of its expected life.
Ask the seller or listing agent for:
- The roof’s installation date
- The roofing material and manufacturer, if available
- Receipts, warranties, and permits for roof work
- Details about previous repairs or storm damage
- The date and scope of the most recent inspection
A roof that appears acceptable during a casual walkthrough may still need documentation. Some carriers distinguish between full roof replacement and repairs, and some apply different claim settlement terms based on roof age or condition.
Do not assume a new roof automatically means a low premium. Location, construction, replacement cost, deductible choices, claims history, protective devices, and the home’s overall condition also matter.
How does claims history affect your quote?
Claims history can influence both the price and availability of home insurance. Insurers may review claims associated with you as an applicant and claims connected to the property. A history of frequent or severe losses can suggest a higher future risk, even if the damage was repaired.
Ask for a CLUE report or other available loss-history information during the buying process. It may help identify past water, fire, theft, or storm claims that are not obvious from a showing. You should also ask whether previous damage was fully repaired and whether any underlying problem remains.
A single claim does not automatically make a home uninsurable. The effect depends on the type of loss, when it occurred, the amount paid, the repairs completed, and each carrier’s underwriting rules. Be accurate when answering an insurer’s questions; incomplete information can create problems when a policy is issued or a claim is filed.
What are wind and hail deductibles in Oklahoma?
Wind and hail deductibles are the amount you pay before insurance contributes to a covered windstorm or hail claim. In Oklahoma, where severe thunderstorms, straight-line winds, and hail can be significant risks, these deductibles deserve special attention before you choose a policy.
A deductible may be shown as:
- A flat dollar amount, such as $2,500
- A percentage of the dwelling coverage limit, such as 1% or 2%
- A separate deductible that applies only to wind or hail damage
For example, if your dwelling coverage is $300,000 and the wind and hail deductible is 2%, you could be responsible for $6,000 on a covered claim before the policy pays. The exact calculation and policy language vary, so ask the agent to explain it using your estimated coverage limit.
A higher deductible may reduce the premium, but it also means you need more savings available after a storm. Compare the annual premium difference with the amount you could realistically pay out of pocket. Also ask whether roof damage is settled at replacement cost or actual cash value, because that distinction can substantially affect a claim payment.
What information do you need for an Oklahoma home insurance quote?
Providing complete information helps an agent give you a more useful estimate. Gather as much of the following as possible:
- Property address and intended occupancy
- Purchase price and approximate square footage
- Year built, foundation type, and construction materials
- Roof age, material, and condition
- Plumbing, electrical, heating, and air-conditioning updates
- Detached structures such as garages, workshops, pools, or fences
- Prior insurance and claims information
- Desired deductible and any valuable property needing special coverage
The purchase price is not the same as the cost to rebuild the home. Insurance dwelling coverage is generally based on estimated reconstruction cost, not land value or market price. Your agent can help explain why those numbers may differ.
How can you compare Oklahoma home insurance quotes?
Do not compare quotes by premium alone. A lower price may reflect a higher deductible, lower limits, narrower roof coverage, or exclusions that matter in Oklahoma.
Compare these items side by side:
- Dwelling coverage and whether it reflects current reconstruction costs
- Other structures, personal property, and loss-of-use limits
- Wind and hail deductible structure
- Roof claim settlement terms
- Water, sewer backup, equipment breakdown, and other optional coverages
You can also review home insurance coverage information and use the agency’s general insurance FAQs to prepare questions. If you are buying in the Edmond area, local context can be useful; see the Edmond insurance FAQs .
What should you do before closing?
Use this short closing checklist:
- Choose an insurer and confirm the policy’s effective date.
- Verify the lender’s mortgagee clause and coverage requirements.
- Review wind and hail deductibles in dollars, not only percentages.
- Confirm roof coverage, personal property limits, and liability limits.
- Send the binder or proof of insurance to the lender.
- Keep your declarations page and payment confirmation after closing.
If the inspection identifies roof damage, plumbing problems, or electrical concerns, tell your agent. Updated property information can change the quote, but it is better to resolve changes before closing than after a loss.
Frequently asked questions about buying a home in Oklahoma
How soon should I buy home insurance when purchasing a house in Oklahoma?
Begin comparing quotes before making an offer, then finalize coverage after your offer is accepted. Your policy usually needs to be active on the closing date, and your lender generally needs proof before funding the mortgage.
Can I get an Oklahoma home insurance quote before I have a closing date?
Yes. An agent can often provide an initial estimate using the property address and available home details. Once your offer is accepted, update the quote with the inspection results, roof information, lender requirements, and confirmed closing date.
Does an old roof make a house harder to insure in Oklahoma?
It can. An older or poorly documented roof may lead to a higher premium, restricted coverage, an inspection requirement, or fewer available carriers. Ask for roof records and obtain insurance guidance before finalizing the purchase.
Why are wind and hail deductibles important in Oklahoma?
They determine how much you pay for a covered wind or hail claim before insurance pays. A percentage deductible can equal several thousand dollars, so compare the actual dollar amount and choose a deductible you could afford after a storm.
What is the best next step for an Oklahoma home insurance quote?
Request a quote before making an offer and provide the property address, roof age, construction details, and claims information. Miner Family Insurance can help you compare coverage and understand lender requirements through the home insurance quote page .
Make insurance part of your home-buying plan
The best time to address home insurance is before an offer, not the day before closing. Early quotes can uncover roof, claims-history, deductible, and coverage issues while you still have time to compare options. Once your offer is accepted, confirm the lender’s requirements, bind coverage for the closing date, and review the policy beyond its price. If you are buying in Oklahoma, get a free quote from Miner Family Insurance before you make an offer so you can budget with greater confidence and move toward closing without an avoidable insurance surprise.